



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics438 Questions
Exam 2: Thinking Like an Economist620 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand700 Questions
Exam 5: Elasticity and Its Application598 Questions
Exam 6: Supply, Demand, and Government Policies648 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Application: the Costs of Taxation514 Questions
Exam 9: Application: International Trade496 Questions
Exam 10: Measuring a Nations Income522 Questions
Exam 11: Measuring the Cost of Living545 Questions
Exam 12: Production and Growth507 Questions
Exam 13: Saving, Investment, and the Financial System567 Questions
Exam 14: The Basic Tools of Finance513 Questions
Exam 15: Unemployment699 Questions
Exam 16: The Monetary System517 Questions
Exam 17: Money Growth and Inflation487 Questions
Exam 18: Open-Economy Macroeconomics: Basic Concepts522 Questions
Exam 19: A Macroeconomic Theory of the Open Economy484 Questions
Exam 20: Aggregate Demand and Aggregate Supply563 Questions
Exam 21: The Influence of Monetary and Fiscal Policy on Aggregate Demand511 Questions
Exam 22: The Short-Run Trade-Off Between Inflation and Unemployment516 Questions
Exam 23: Six Debates Over Macroeconomic Policy372 Questions
Select questions type


Figure 7-22  -Refer to Figure 7-22. Assume demand increases, which causes the equilibrium price to increase from $50 to $70. The increase in producer surplus due to new producers entering the market would be
 (Multiple Choice)
4.8/5  (76)
(76) Figure 7-18  -Refer to Figure 7-18. Total surplus amounts to $500 if consumer surplus amounts to
 (Multiple Choice)
4.8/5 (87)
(87) Suppose there is an increase in supply that reduces market price. Consumer surplus increases because 1) consumer surplus received by existing buyers increases and 2) new buyers enter the market.
(True/False)
4.8/5 (81)
(81) Table 7-5
For each of three potential buyers of oranges, the table displays the willingness to pay for the first three oranges of the day. Assume Allison, Bob, and Charisse are the only three buyers of oranges, and only three oranges can be supplied per day.
 -Refer to Table 7-5. If the market price of an orange is $0.70, then the market quantity of oranges demanded per day is
 (Multiple Choice)
4.8/5 (72)
(72) Figure 7-23  -Refer to Figure 7-23. At equilibrium, consumer surplus is represented by the area
 (Multiple Choice)
5.0/5 (88)
(88) Table 7-11
The following table represents the costs of five possible sellers.
-Refer to Table 7-11. If the market price is $1,100, the combined total cost of all participating sellers is
(Multiple Choice)
4.8/5 (83)
(83) Figure 7-25 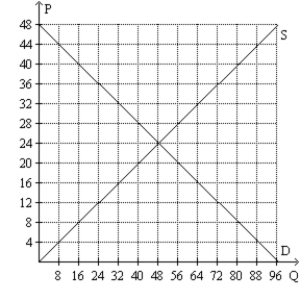 -Refer to Figure 7-25. At the equilibrium price, total surplus is
 (Multiple Choice)
4.8/5 (75)
(75) Suppose the demand for peaches decreases. What will happen to producer surplus in the market for peaches?
(Multiple Choice)
4.9/5 (73)
(73) Figure 7-16  -Refer to Figure 7-16. Sellers will be unwilling to sell more than
 (Multiple Choice)
4.8/5 (76)
(76) Producer surplus measures the benefit to sellers from receiving a price above their costs.
(True/False)
4.8/5 (73)
(73) Figure 7-23
-Refer to Figure 7-23. The equilibrium price is
-Refer to Figure 7-23. The equilibrium price is (Multiple Choice)
4.9/5 (83)
(83) Table 7-13
The numbers reveal the opportunity costs of providing 10 piano lessons of equal quality.
 -Refer to Table 7-13. You wish to purchase 10 piano lessons for yourself and for your brother, so you take bids from each of the sellers. You will take lessons at the same time, so one teacher cannot provide lessons to both of you. You must pay the same price for both sets of lessons, and you will not accept a bid below a seller's cost because you are concerned that the seller will not provide all 10 lessons. What bid will you accept?
 (Multiple Choice)
4.9/5 (66)
(66) Total surplus in a market will increase when the government
(Multiple Choice)
4.9/5 (77)
(77) Scenario 7-1
Suppose market demand is given by the equation  -Refer to Scenario 7-1. If the market equilibrium price falls from $10 to $5, what is the change in total consumer surplus in the market?
 (Essay)
4.7/5 (78)
(78) Scenario 7-2
Suppose market demand and market supply are given by the equations:  -Refer to Scenario 7-2. Suppose a reduction in input prices shifts the market supply curve to
 By how much does total producer surplus increase as a result of this supply shift?
-Refer to Scenario 7-2. Suppose a reduction in input prices shifts the market supply curve to By how much does total producer surplus increase as a result of this supply shift? (Essay)
4.8/5 (76)
(76) Suppose televisions are a normal good and buyers of televisions experience a decrease in income. As a result, consumer surplus in the television market
(Multiple Choice)
4.9/5 (86)
(86) The French expression used by free-market advocates, which literally translates as "allow them to do," is
(Multiple Choice)
4.7/5 (70)
(70) Refer to Figure 7-11. If the supply curve is S', the demand curve is D, and the equilibrium price is $150, what is the producer surplus?
(Multiple Choice)
4.8/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)