



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics438 Questions
Exam 2: Thinking Like an Economist620 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand700 Questions
Exam 5: Elasticity and Its Application598 Questions
Exam 6: Supply, Demand, and Government Policies648 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Application: the Costs of Taxation514 Questions
Exam 9: Application: International Trade496 Questions
Exam 10: Measuring a Nations Income522 Questions
Exam 11: Measuring the Cost of Living545 Questions
Exam 12: Production and Growth507 Questions
Exam 13: Saving, Investment, and the Financial System567 Questions
Exam 14: The Basic Tools of Finance513 Questions
Exam 15: Unemployment699 Questions
Exam 16: The Monetary System517 Questions
Exam 17: Money Growth and Inflation487 Questions
Exam 18: Open-Economy Macroeconomics: Basic Concepts522 Questions
Exam 19: A Macroeconomic Theory of the Open Economy484 Questions
Exam 20: Aggregate Demand and Aggregate Supply563 Questions
Exam 21: The Influence of Monetary and Fiscal Policy on Aggregate Demand511 Questions
Exam 22: The Short-Run Trade-Off Between Inflation and Unemployment516 Questions
Exam 23: Six Debates Over Macroeconomic Policy372 Questions
Select questions type


Allen tutors in his spare time for extra income. Buyers of his service are willing to pay $40 per hour for as many hours Allen is willing to tutor. On a particular day, he is willing to tutor the first hour for $10, the second hour for $18, the third hour for $28, and the fourth hour for $40. Assume Allen is rational in deciding how many hours to tutor. His producer surplus is
(Multiple Choice)
4.8/5  (95)
(95) Kristi and Rebecca sell lemonade on the corner for $0.50 per cup. It costs them $0.10 to make each cup. On a certain day, their producer surplus is $20. How many cups did Kristi and Rebecca sell?
(Multiple Choice)
4.8/5 (81)
(81) Answer each of the following questions about supply and producer surplus.
a. What is producer surplus, and how is it measured?
b. What is the relationship between the cost to sellers and the supply curve?
c. Other things equal, what happens to producer surplus when the price of a good rises?
Illustrate your answer on a supply curve.
(Essay)
4.9/5 (76)
(76) Figure 7-11 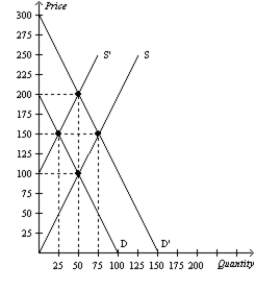 -Refer to Figure 7-11. If the supply curve is S, the demand curve is D, and the equilibrium price is $100, what is the producer surplus?
 (Multiple Choice)
4.9/5 (69)
(69) Figure 7-20  -Refer to Figure 7-20. Total surplus can be measured as the area
 (Multiple Choice)
4.8/5 (84)
(84) If the government removes a binding price ceiling in a market, then the producer surplus in that market will increase.
(True/False)
4.9/5 (77)
(77) Figure 7-27  -Refer to Figure 7-27. Buyers who value this good less than the equilibrium price are represented by which line segment?
 (Multiple Choice)
4.9/5 (96)
(96) Consumer surplus is the amount a buyer is willing to pay for a good minus the amount the buyer actually has to pay for it.
(True/False)
4.8/5 (73)
(73) Figure 7-33  -Refer to Figure 7-33. Suppose demand shifts such that consumers wish to purchase 12 fewer units at every price.
How much is total surplus in this market at the new equilibrium price?
-Refer to Figure 7-33. Suppose demand shifts such that consumers wish to purchase 12 fewer units at every price.
How much is total surplus in this market at the new equilibrium price? (Essay)
4.8/5 (84)
(84) Answer the following questions based on the graph that represents J.R.'s demand for ribs per week at Judy's Rib Shack.
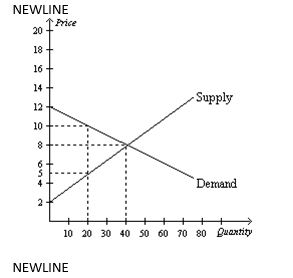 a. At the equilibrium price, how many ribs would J.R. be willing to purchase?
b. How much is J.R. willing to pay for 20 ribs?
c. What is the magnitude of J.R.'s consumer surplus at the equilibrium price?
d. At the equilibrium price, how many ribs would Judy be willing to sell?
e. How high must the price of ribs be for Judy to supply 20 ribs to the market?
f. At the equilibrium price, what is the magnitude of total surplus in the market?
g. If the price of ribs rose to $10, what would happen to J.R.'s consumer surplus?
h. If the price of ribs fell to $5, what would happen to Judy's producer surplus?
i. Explain why the graph that is shown verifies the fact that the market equilibrium quantity) maximizes the sum of producer and consumer surplus.
a. At the equilibrium price, how many ribs would J.R. be willing to purchase?
b. How much is J.R. willing to pay for 20 ribs?
c. What is the magnitude of J.R.'s consumer surplus at the equilibrium price?
d. At the equilibrium price, how many ribs would Judy be willing to sell?
e. How high must the price of ribs be for Judy to supply 20 ribs to the market?
f. At the equilibrium price, what is the magnitude of total surplus in the market?
g. If the price of ribs rose to $10, what would happen to J.R.'s consumer surplus?
h. If the price of ribs fell to $5, what would happen to Judy's producer surplus?
i. Explain why the graph that is shown verifies the fact that the market equilibrium quantity) maximizes the sum of producer and consumer surplus. (Essay)
4.9/5 (87)
(87) Figure 7-15  -Refer to Figure 7-15. When the price rises from P1 to P2, what area represents the increase in producer surplus?
 (Multiple Choice)
5.0/5 (85)
(85) If the government allowed a free market for transplant organs such as kidneys to exist, critics argue that such a market would
(Multiple Choice)
4.9/5 (70)
(70) Denise values a stainless steel dishwasher for her new house at $500, but she succeeds in buying one for $350. Denise's consumer surplus is
(Multiple Choice)
4.8/5 (68)
(68) Table 7-13
The numbers reveal the opportunity costs of providing 10 piano lessons of equal quality.
 -Refer to Table 7-13. The equilibrium market price for 10 piano lessons is $400. What is the total producer surplus in the market?
 (Multiple Choice)
4.9/5 (82)
(82) Figure 7-10  -Refer to Figure 7-10. Which area represents producer surplus when the price is P1?
 (Multiple Choice)
4.8/5 (87)
(87) The lower the price, the lower the consumer surplus, all else equal.
(True/False)
4.8/5 (82)
(82) Motor oil and gasoline are complements. If the price of motor oil increases, consumer surplus in the gasoline market
(Multiple Choice)
4.9/5 (79)
(79) Kristi sells purses. Her cost is $35 per purse. On a certain day, she sells 12 purses, and her producer surplus for that day amounts to $180. Kristi sold each purse for
(Multiple Choice)
4.7/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)