



 Chat with AI
Exam 26: Tax Practice and Ethics

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law211 Questions
Exam 2: Working with the Tax Law102 Questions
Exam 3: Computing the Tax180 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: In General156 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses94 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion120 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses153 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions104 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments111 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges285 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions167 Questions
Exam 15: Taxing Business Income60 Questions
Exam 16: Accounting Periods and Methods88 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure109 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation185 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations71 Questions
Exam 21: Partnerships248 Questions
Exam 22: S Corporations129 Questions
Exam 23: Exempt Entities153 Questions
Exam 24: Multistate Corporate Taxation204 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics184 Questions
Exam 27: The Federal Gift and Estate Taxes141 Questions
Exam 28: Income Taxation of Trusts and Estates161 Questions
Select questions type


Match each of the following tax penalties with the type of tax penalty as specified by the Code. A letter can be used more than once. The correct solution may include more than one letter.
a. Taxpayer penalty
b. Tax preparer penalty
c. Appraiser's penalty
-Negligence.
(Short Answer)
4.8/5  (77)
(77) Which of the following statements does not reflect the rules governing the accuracy-related penalty for negligence?
(Multiple Choice)
4.9/5 (74)
(74) Jake, an individual calendar year taxpayer, incurred the following transactions. 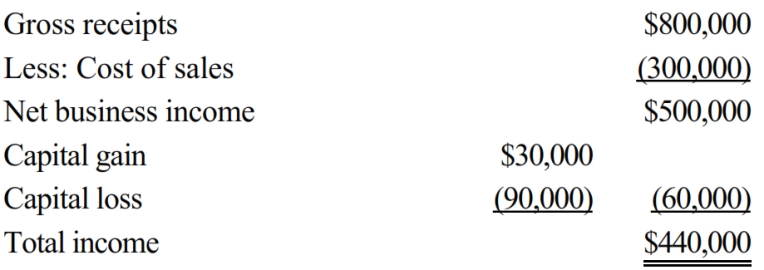 Assuming that any error in timely reporting these amounts was inadvertent, how much omission from gross income would be required before the six-year statute of limitations would apply?
 (Multiple Choice)
4.9/5 (90)
(90) Fiona, a VITA volunteer for her college's tax clinic, is not a tax preparer as defined by the Code. Thus, Fiona is exempted from the Code's tax preparer penalties.
(True/False)
4.8/5 (90)
(90) An individual might be incarcerated upon a conviction for:
(Multiple Choice)
4.8/5 (70)
(70) For each of the indicated tax penalties, indicate the appropriate taxpayer defense. A letter may be used more than once. Not all of the letters need be used.
a. Ignorance of the tax law
b. Reasonable basis
c. Reasonable cause
d. Complexity of the tax law
e. Substantial authority
f. Disclosure on return
-Preparer penalty for reckless conduct.
(Short Answer)
4.8/5 (94)
(94) For each of the indicated tax penalties, indicate the appropriate taxpayer defense. A letter may be used more than once. Not all of the letters need be used.
a. Ignorance of the tax law
b. Reasonable basis
c. Reasonable cause
d. Complexity of the tax law
e. Substantial authority
f. Disclosure on return
-Negligence in filing a return.
(Short Answer)
4.9/5 (81)
(81) The taxpayer or a tax advisor may be subject to penalties if there is a misstatement of the valuation of an item reported on the tax return. Describe how these penalties work.
(Essay)
4.8/5 (92)
(92) The government can appeal a decision of the Tax Court Small Cases Division, but the taxpayer cannot.
(True/False)
4.9/5 (64)
(64) According to the IRS, the annual "Tax Gap" totals over________________ $ billion.
(Short Answer)
4.8/5 (88)
(88) Match each of the following tax penalties with the type of tax penalty as specified by the Code. A letter can be used more than once. The correct solution may include more than one letter.
a. Taxpayer penalty
b. Tax preparer penalty
c. Appraiser's penalty
-Aiding in preparing an improper tax return.
(Short Answer)
4.8/5 (78)
(78) What are the chief responsibilities of the IRS Commissioner, and of the Chief Counsel of the IRS?
(Essay)
4.8/5 (84)
(84) If an ex-employee wants to give information to the IRS about shady tax dealings about the employer, where the disputed amount is $500,000, the best approach is to use the:
(Multiple Choice)
4.9/5 (65)
(65) The IRS is organized according to the industry classification of the taxpayer. One of the operating divisions of the IRS deals exclusively with manufacturing and exporting businesses.
(True/False)
4.9/5 (67)
(67) In a letter ruling, the IRS responds to a taxpayer request concerning the tax treatment of a proposed transaction.
(True/False)
4.9/5 (79)
(79) A tax preparer is in violation of Circular 230 if he or she:
(Multiple Choice)
4.8/5 (84)
(84) A ________________ % penalty may result when the value of an asset contributed to a charity is reported at an amount that exceeds 150% of the correct valuation.
(Short Answer)
4.9/5 (88)
(88) Compute the failure to pay and failure to file penalties for John, who filed his 2018 income tax return on December
14, 2019, paying the $10,000 amount due. On April 1, 2019, John submitted a six-month extension of time in which to file his return? he paid no tax with the extension request. He has no reasonable cause for failing to file his return by October 15, or for failing to pay the tax that was due on April 15, 2019. John's failure to comply with the tax laws was not fraudulent.
(Essay)
4.9/5 (69)
(69) For each of the indicated tax penalties, indicate the appropriate taxpayer defense. A letter may be used more than once. Not all of the letters need be used.
a. Ignorance of the tax law
b. Reasonable basis
c. Reasonable cause
d. Complexity of the tax law
e. Substantial authority
f. Disclosure on return
-Undervaluation of a reported item.
(Short Answer)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)