



 Chat with AI
Exam 22: S Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


How may an S corporation manage its liability for the built-in gains tax?
(Essay)
4.7/5  (74)
(74) When an S corporation liquidates,which of its tax attributes disappear?
(Multiple Choice)
4.8/5 (81)
(81) Explain how the domestic production activities deduction is used for an S corporation.
(Essay)
4.9/5 (74)
(74) On December 31,2009,Erica Sumners owns one share of an S corporation's 10 outstanding shares of stock.The basis of Erica's share is $300.During 2010,the S corporation has no income or deductions,but incurs a loss of $3,650.Using the separate-share approach,determine the amount of the loss allocated to Erica and calculate her stock basis in 2010.
(Essay)
4.8/5 (83)
(83) The Schedule M-3 is the same for a C corporation and an S corporation.
(True/False)
4.9/5 (66)
(66) Samantha owned 1,000 shares in Evita,Inc. ,an S corporation,that uses the calendar year.On October 11,2010,Samantha sells all of her Evita stock.Her basis at the beginning of 2010 was $60,000.Her share of the corporate income for 2010 was $22,000,and she receives a distribution of $37,000 between January 1 and October 11,2010.Her basis at the time of the sale is:
(Multiple Choice)
4.8/5 (74)
(74) Lott Corporation in Macon,Georgia converts to S corporation status in 2010.Lott used the LIFO inventory method in 2009 and had a LIFO inventory of $420,000 (FIFO value of $550,000).How much tax must be added to the 2009 corporate tax liability,assuming that Lott is subject to a 35% tax rate.
(Multiple Choice)
4.8/5 (68)
(68) A distribution of cash or other property by an S corporation to shareholders that does not exceed the balance of AAA during a one-year period following an S election termination receives special capital gain treatment.
(True/False)
4.8/5 (82)
(82) An S shareholder's basis does not include a ratable share of any S corporation liabilities.
(True/False)
4.9/5 (83)
(83) An S shareholder's basis in his or her stock can be reduced below zero.
(True/False)
4.8/5 (75)
(75) The debt basis always is adjusted back to the original amount before any increase is made in the stock basis.
(True/False)
4.8/5 (78)
(78) Compensation for services rendered to an S corporation is not subject to FICA taxes.
(True/False)
4.9/5 (93)
(93) An S corporation must recognize ____________________ but not ____________________ on distributions of appreciated property.
(Short Answer)
4.7/5 (79)
(79) Brew,an S corporation,has gross receipts of $190,000 and gross income of $170,000.Brew has AEP of $22,000 and ordinary income of $29,000.It has passive investment income of $100,000,with $40,000 of expenses directly related to the production of passive investment income.Calculate Brew's excess net passive income and any passive investment income penalty tax.
(Essay)
4.8/5 (70)
(70) Bidden,Inc. ,a calendar year S corporation,incurred the following items.
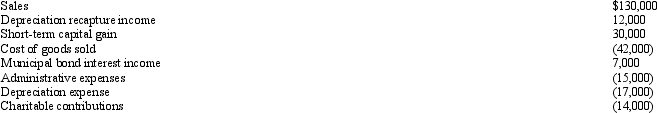 Calculate Bidden's nonseparately computed income.
 (Essay)
4.7/5 (75)
(75) An S shareholder who dies during the corporate tax year must report his or her share of the pro rata income (or loss)up to the date of death on the final individual tax return.
(True/False)
4.8/5 (80)
(80) As a general rule,S corporation treatment is not advantageous when the individual tax rate far exceeds the applicable corporate tax rate.
(True/False)
4.9/5 (65)
(65) Malin,a 51% owner of an S corporation,has a stock basis of zero at the beginning of the year.Malin's basis in a $30,000 loan made to the S corporation and evidenced by a corporate note has been reduced to zero by pass-through losses.During the year,her net share of corporate ordinary income is $12,000.At the end of the year,Malin receives a $14,000 distribution.Determine any taxable income from the distribution.
(Multiple Choice)
4.8/5 (70)
(70) An S corporation does not recognize a loss when distributing assets that are worth less than their basis.
(True/False)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)