



 Chat with AI
Exam 22: S Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


You are given the following facts about a 50% owner of an S corporation,and you are asked to prepare her ending stock basis. 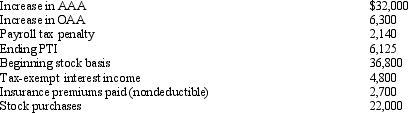
(Multiple Choice)
4.9/5  (81)
(81) You are given the following facts about a one-shareholder S corporation,and you are asked to prepare the shareholder's ending stock basis. 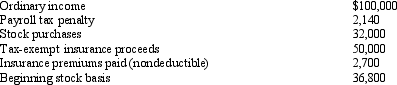
(Multiple Choice)
4.8/5 (82)
(82) An S corporation with earnings and profits can make a taxable dividend distribution by making a AAA bypass election.
(True/False)
4.9/5 (84)
(84) Beginning in 2010,the AAA of Amit,Inc. ,an S corporation,has a balance of $725,000.During the year,the following items occur. 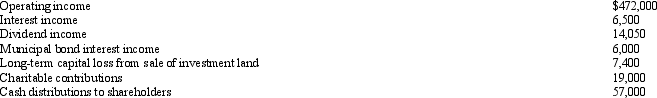 Amit's ending AAA balance is:
 (Multiple Choice)
4.7/5 (94)
(94) S corporation status allows shareholders to realize tax benefits from corporate losses ____________________.
(Short Answer)
4.7/5 (78)
(78) During 2010,Shirley Nutt,the sole shareholder of a calendar year S corporation,received a distribution of $16,000.On December 31,2009,her stock basis was $4,000.The corporation earned $11,000 ordinary income during the year.It has no accumulated E & P.Which statement is correct?
(Multiple Choice)
4.7/5 (74)
(74) You are a 60% owner of an S corporation.Calculate your ending stock basis,based upon these facts.
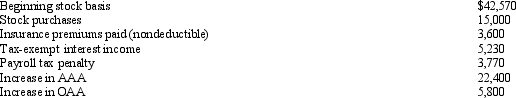
(Essay)
4.8/5 (84)
(84) Tax-exempt income at the corporate level does flow through to the shareholders.
(True/False)
4.8/5 (85)
(85) Persons who were shareholders during any part of the year before the election date,but were not shareholders when the election was made,also must consent to the election for the S election to be effective for the current tax year.
(True/False)
4.9/5 (71)
(71) Since loss property receives a ____________________ in basis without any loss recognition,distributions of loss property should be ____________________.
(Short Answer)
4.9/5 (77)
(77) No maximum or minimum dollar sales or capitalization restrictions apply to S corporations.
(True/False)
4.9/5 (92)
(92) An S corporation is entitled to a deduction for its NOL carryovers.
(True/False)
4.9/5 (66)
(66) Form 1120S provides a shareholder's computation of his or her stock basis.
(True/False)
4.8/5 (76)
(76) Chris,the sole shareholder of Taylor,Inc. ,elects during 2010 to terminate the S election,effective January 1,2011.As of the end of 2010,Taylor,Inc. ,has AAA of $120,000 and OAA of $13,000.Chris receives a cash distribution of $130,000 on January 15,2011.If his stock basis is $220,000 before the distribution,calculate Chris' taxable amount and his ending stock basis.
(Essay)
4.7/5 (80)
(80) An S shareholder's basis is decreased by distributions treated as being paid from AAA.
(True/False)
4.8/5 (74)
(74) For Federal income tax purposes,taxation of S corporations resembles that of partnerships.
(True/False)
4.8/5 (81)
(81) Advise your client how income,expenses,gains and losses are allocated to shareholders.
(Essay)
4.9/5 (85)
(85) Which,if any,of the following items has no effect on the stock basis of an S corporation shareholder?
(Multiple Choice)
4.8/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)