



 Chat with AI
Exam 22: S Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


For a new corporation,a premature S election may not be effective.
(True/False)
4.8/5  (84)
(84) S corporation provides many of the benefits of ____________________ taxation and at the same time gives the owners ____________________ protection from creditors.
(Short Answer)
4.8/5 (75)
(75) Which,if any,of the following can be eligible shareholders of an S corporation?
(Multiple Choice)
4.8/5 (88)
(88) Shareholders may deduct losses in excess of the basis in S corporation stock when shareholder does not have a loan basis.
(True/False)
4.9/5 (100)
(100) All items (e.g. ,income,losses)are allocated to each shareholder based upon ____________________ ownership throughout the year.
(Short Answer)
4.9/5 (66)
(66) On January 1,Bobby and Alice own equally all of the stock of an electing S corporation called Prairie Dirt Delight.The soil company has a $90,000 loss for a non-leap year.On the 219th day of the year,Bobby sells his one-half of the stock to his son,Naresh.How much of the $90,000 loss is allocated to Alice?
(Multiple Choice)
4.9/5 (85)
(85) Compare the distribution of property rules for an S corporation with the corresponding partnership rules.
(Essay)
4.7/5 (87)
(87) If the beginning balance in OAA is $3,900,and the following transactions occur,what is the ending OAA balance? 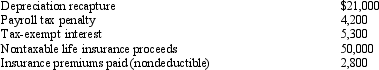
(Multiple Choice)
4.8/5 (78)
(78) It is not beneficial for an S corporation to issue § 1244 stock.
(True/False)
4.8/5 (82)
(82) Any excess of S corporation losses or deductions over the shareholder's combined stock and debt basis is suspended until there is a subsequent stock or debt basis.
(True/False)
4.9/5 (73)
(73) Non-separately computed loss ____________________ a S shareholder's stock basis.
(Short Answer)
4.8/5 (77)
(77) In the case of a complete termination of an S corporation interest,a ____________________ tax year may occur.
(Short Answer)
4.9/5 (84)
(84) Estela,Inc. ,a calendar year S corporation,incurred the following items in 2010.
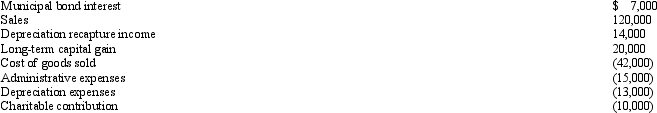 Calculate Estela's nonseparately computed income.
 (Essay)
4.8/5 (77)
(77) An S election made before becoming a corporation is valid the next 22-month tax year.
(True/False)
4.8/5 (86)
(86) Crew Corporation elects S status effective for tax year 2010.As of January 1,2010,Crew's assets were appraised as follows.
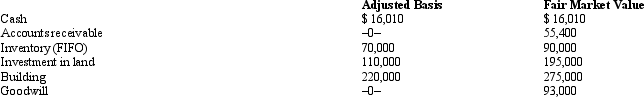 In each of the following situations,calculate any built-in gains tax,assuming that the highest corporate tax rate is 35%.C corporation taxable income would have been $100,000.
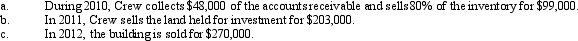
In each of the following situations,calculate any built-in gains tax,assuming that the highest corporate tax rate is 35%.C corporation taxable income would have been $100,000.
(Essay)
4.8/5 (72)
(72) A cash basis calendar year C corporation in Athens,Georgia,has $100,000 of accounts receivable on the date of its conversion to an S corporation on February 14.By the end of the year,$70,000 of these receivables are collected.Calculate any built-in gains tax,assuming that there is sufficient taxable income.
(Multiple Choice)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)