



 Chat with AI
Exam 28: Income Taxation of Trusts and Estates

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


Subchapter J applies a modified ____________________ principle in deriving the tax liability for estates,trusts,and their beneficiaries.

Free
(Short Answer)
4.9/5  (80)
(80) Correct Answer: Verified
flowthrough or passthrough
Which of the following taxpayers use a Schedule K and K-1 to pass through income,loss,and credit amounts to the owners or beneficiaries?
Free
(Multiple Choice)
4.9/5 (85)
(85) Correct Answer:Verified
VerifiedD
In the year in which an estate terminates,its beneficiaries receive and can use as their own any unexpired NOL carryforwards proportionately to the corpus assets that they received.
Free
(True/False)
4.7/5 (92)
(92) Correct Answer:Verified
VerifiedTrue
The decedent's estate must terminate by the third anniversary of the date of death.
(True/False)
4.8/5 (71)
(71) The Roz Trust has distributable net income for the year of $100,000 and no income from tax-exempt sources.Under the terms of the trust instrument,the trustee must distribute $30,000 to Roger and $30,000 to Sally.After paying these amounts,the trustee is empowered to make additional distributions at its discretion.Exercising this authority,the trustee distributes an additional $10,000 to Roger and $30,000 to Sally.How much gross income from the trust must Roger recognize?
(Multiple Choice)
4.8/5 (76)
(76) To reduce trustee commissions,the Emily Trust is operated as though it were two trusts (i.e. ,with 70-year-old Grandma and 7-year old Skippy each holding equal shares).This year the trust generated distributable net income (DNI)of $80,000.The trustee distributed $90,000 to Grandma this year: $40,000 as her one-half share of the entity's income,and $50,000 as a distribution of principal.How much of the year's distributable net income is assigned to Grandma?
(Multiple Choice)
4.8/5 (79)
(79) Summarize the Federal income tax filing requirements that apply to an estate or trust.
(Essay)
4.7/5 (88)
(88) When a trust distributes an in-kind asset with a realized loss,most likely this loss should be allocated to and immediately deducted by the first-tier beneficiaries.
(True/False)
4.8/5 (82)
(82) With respect to a trust,the terms creator,donor,and grantor are synonyms.
(True/False)
4.8/5 (65)
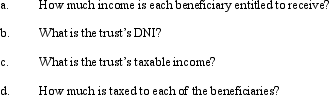
(65) The LMN Trust is a simple trust that correctly uses the calendar year for tax purposes.Its income beneficiaries (Kathie,Lynn,Mark,and Norelle)are entitled to the trust's annual accounting income in shares of one-fourth each.For the current calendar year,the trust has ordinary business income of $30,000,a long-term capital gain of $20,000 (allocable to corpus),and a trustee commission expense of $4,000 (allocable to corpus).Use the format of Figure 28.3 in the text to address the following items.
(Essay)
4.9/5 (65)
(65) The Gable Trust reports $20,000 business income and $10,000 exempt interest income,and it paid a $3,000 fiduciary fee.Gable's distributable net income is computed net of the full $3,000 deduction for the fees.
(True/False)
4.7/5 (73)
(73) The Purple Trust incurred the following items this year.
 Compute Purple's tentative minimum tax for the year.Purple does not have any credits available to reduce the AMT liability.
 (Essay)
4.9/5 (75)
(75) The Roz Trust has distributable net income for the year of $100,000 and no income from tax-exempt sources.Under the terms of the trust instrument,the trustee is required to distribute $30,000 to Roger and $60,000 to Sally.After payment of these amounts,the trustee is empowered to make additional distributions at its discretion.Exercising this authority,the trustee distributes an additional $40,000 to Roger,and $40,000 to Sally.How much income from the trust must Sally recognize?
(Multiple Choice)
5.0/5 (78)
(78) The Jain Trust is required to pay its entire annual accounting income to the Daytona Museum,a qualifying charity.The trust's personal exemption is:
(Multiple Choice)
4.7/5 (75)
(75) Describe how an estate or trust treats "income in respect of a decedent."
(Essay)
4.9/5 (79)
(79) The Roz Trust has distributable net income (DNI)for the year of $100,000 and no income from tax-exempt sources.Under the terms of the trust instrument,the trustee must distribute $80,000 to Roger and $80,000 to Sally.After paying these amounts,the trustee is empowered to make additional distributions at its discretion.Exercising this authority,the trustee distributes an additional $20,000 to Roger and $20,000 to Sally.How much gross income from the trust must Roger recognize?
(Multiple Choice)
4.7/5 (67)
(67) Generally,capital gains are allocated to fiduciary corpus,because they relate to investment assets.
(True/False)
4.8/5 (84)
(84) A complex trust can claim a Year 1 deduction for a gift to charity,where the contribution was made in October of Year 2 out of gross income recognized in Year 1.
(True/False)
4.8/5 (69)
(69) The Cooper Trust is required to distribute $80,000 annually,split equally between its two income beneficiaries,Amber and Byron.If trust income is not sufficient to pay these amounts,the trustee can invade corpus to the extent necessary.During the current year,the trust has DNI of $50,000.Byron receives an additional $20,000 discretionary corpus distribution.
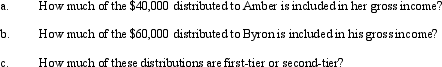
(Essay)
4.8/5 (91)
(91) Once the distributable net income (DNI)of a trust or estate is known,how does the entity compute its deduction for distributions to beneficiaries?
(Essay)
4.8/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)