



 Chat with AI
Exam 18: Corporations: Organization and Capital Structure

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


Hazel transferred the following assets to Starling Corporation. 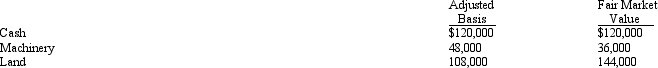 In exchange,Hazel received 50% of Starling Corporation's only class of stock outstanding.The stock has no established value.However,all parties sincerely believe that the value of the stock Hazel received is the equivalent of the value of the assets she transferred.The only other shareholder,Rick,formed Starling Corporation five years ago.
Free
(Multiple Choice)
4.8/5  (84)
(84) Correct Answer: Verified
C
The bona fide business requirement of § 357(b)is easily satisfied as long as the liability arose in the normal course of conducting the business that is incorporated.
Free
(True/False)
4.8/5 (77)
(77) Correct Answer:Verified
VerifiedTrue
Sarah and Emily form Red Corporation with the following investments: Sarah transfers computers worth $200,000 (basis of $80,000),while Emily transfers real estate worth $180,000 (basis of $40,000)and services (worth $20,000)rendered in organizing the corporation.Each is issued 600 shares in Red Corporation.With respect to the transfers:
Free
(Multiple Choice)
4.7/5 (78)
(78) Correct Answer:Verified
VerifiedD
Wade and Paul form Swan Corporation with the following investments.Wade transfers machinery (basis of $40,000 and fair market value of $100,000),while Paul transfers land (basis of $20,000 and fair market value of $90,000)and services rendered (worth $10,000)in organizing the corporation.Each is issued 25 shares in Swan Corporation.With respect to the transfers:
(Multiple Choice)
4.9/5 (78)
(78) Kim,a real estate dealer,and others form Eagle Corporation under § 351.Kim contributes inventory (land held for resale)in return for Eagle stock.The holding period for the stock includes the holding period of the inventory.
(True/False)
4.8/5 (91)
(91) Karen formed Grebe Corporation with an investment of $100,000 cash,for which she received $10,000 in stock and $90,000 in 9% interest-bearing bonds maturing in ten years.A few years later Karen loaned Grebe an additional $40,000 on open account.Grebe becomes insolvent in the current year and is adjudged bankrupt.Karen was the president of Grebe Corporation and was paid an annual salary of $30,000 for the past three years.Karen has no other employment.How will Karen treat her losses for tax purposes?
(Essay)
4.8/5 (80)
(80) Adam transfers cash of $300,000 and land worth $200,000 to Camel Corporation for 100% of the stock in Camel.In the first year of operation,Camel has net taxable income of $70,000.If Camel distributes $50,000 to Adam:
(Multiple Choice)
4.9/5 (78)
(78) Tina incorporates her sole proprietorship with assets having a fair market value of $100,000 and an adjusted basis of $110,000.Even though § 351 applies,Tina may recognize her realized loss of $10,000.
(True/False)
4.9/5 (70)
(70) Similar to the like-kind exchange provision,§ 351 can be partly justified under the wherewithal to pay concept.
(True/False)
4.9/5 (85)
(85) In a § 351 transfer,gain will be recognized to the extent of the greater of realized gain or the boot received.
(True/False)
4.9/5 (83)
(83) When a taxpayer transfers property subject to a mortgage to a controlled corporation in an exchange qualifying under § 351,the transferor shareholder's basis in stock received in the transferee corporation is increased by the amount of the mortgage on the property.
(True/False)
4.8/5 (91)
(91) Amy owns 20% of the stock of Wren Corporation,which she acquired several years ago at a cost of $10,000.Amy is Vice-President of Wren and earns a salary of $80,000 annually.Last year,Wren Corporation was experiencing financial problems,and Amy loaned the corporation $25,000.In the current year,Wren becomes bankrupt,and both her stock investment and the loan become worthless.Amy has a nonbusiness bad debt deduction this year of $25,000.
(True/False)
4.8/5 (73)
(73) Tara incorporates her sole proprietorship,transferring it to newly formed Black Corporation.The assets transferred have an adjusted basis of $240,000 and a fair market value of $300,000.Also transferred was $10,000 in liabilities,$1,000 of which was personal and the balance of $9,000 being business related.In return for these transfers,Tara receives all of the stock in Black Corporation.
(Multiple Choice)
5.0/5 (82)
(82) Joyce,a single taxpayer,transfers property (basis of $120,000 and fair market value of $60,000)to Wren Corporation in exchange for shares of § 1244 stock.As the transfer qualifies under § 351,Joyce takes a $120,000 basis in the Wren stock.In the current year,Joyce sells the Wren Corporation stock for $40,000.What are the consequences of the sale to Joyce?
(Essay)
4.7/5 (79)
(79) Ann,Irene,and Bob incorporate their respective businesses and form Dove Corporation.Ann exchanges her property (basis of $100,000 and fair market value of $400,000)for 200 shares in Dove Corporation on March 3,2008.Irene exchanges her property (basis of $140,000 and fair market value of $600,000)for 300 shares in Dove Corporation on April 10,2008.Bob transfers his property (basis of $250,000 and fair market value of $1,000,000)for 500 shares in Dove Corporation on May 17,2010.Bob's transfer is not part of a prearranged plan with Ann and Irene to incorporate their businesses.What gain,if any,will Bob recognize on the transfer?
(Multiple Choice)
4.8/5 (78)
(78) Four individuals form Chickadee Corporation under § 351.Two of these individuals,Jane and Walt,made the following contributions: 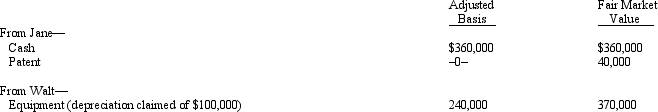 Both Jane and Walt receive stock in Chickadee Corporation equal to the value of their investments.
 (Multiple Choice)
4.7/5 (69)
(69) Nancy,Guy,and Rod form Goldfinch Corporation with the following consideration.
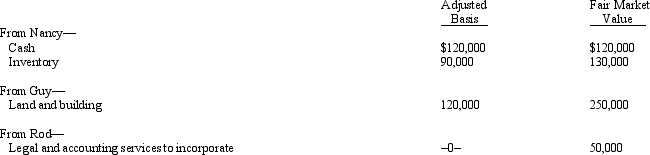 Goldfinch issues its 500 shares of stock as follows: 250 to Nancy,200 to Guy,and 50 to Rod.In addition,Guy gets $50,000 in cash.
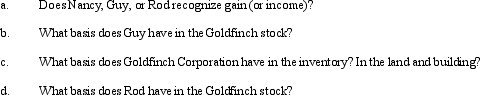
Goldfinch issues its 500 shares of stock as follows: 250 to Nancy,200 to Guy,and 50 to Rod.In addition,Guy gets $50,000 in cash.
(Essay)
5.0/5 (81)
(81) What are the tax consequences if an individual investor incurs a loss on the following:
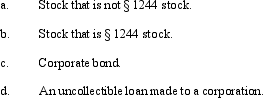
(Essay)
4.8/5 (91)
(91) If a shareholder owns stock received as a gift from her mother,it cannot be § 1244 stock.
(True/False)
4.9/5 (75)
(75) Beth forms Lark Corporation with a transfer of appreciated property in exchange for all of its shares.Shortly thereafter,she transfers half her shares to her son,Ted.The later transfer to Ted could cause the original transfer to be taxable.
(True/False)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)