



 Chat with AI
Exam 18: Corporations: Organization and Capital Structure

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


The use of § 351 is not limited to the initial formation of a corporation,and it can apply to later transfers as well.
(True/False)
4.8/5  (80)
(80) If both §§ 357(b)and (c)apply to the same transfer (i.e. ,the liability is not supported by a bona fide business purpose and also exceeds the basis of the properties transferred),§ 357(b)predominates.
(True/False)
4.9/5 (86)
(86) When forming a corporation,a transferor-shareholder may choose to receive some corporate debt along with stock.Identify some of the issues the transferor must consider when deciding whether debt should be a part of the transaction.
(Essay)
4.8/5 (85)
(85) Kevin and Nicole form Indigo Corporation with the following transfers: inventory from Kevin (basis of $360,000 and fair market value of $400,000)and improved real estate from Nicole (basis of $320,000 and fair market value of $375,000).Nicole,an accountant,agrees to contribute her services (worth $25,000)in organizing Indigo.The corporation's stock is distributed equally to Kevin and Nicole.As a result of these transfers:
(Multiple Choice)
4.7/5 (67)
(67) The receipt of securities (i.e. ,long-term debt)in exchange for the transfer of appreciated property to a controlled corporation results in recognition of realized gain to the transferor.
(True/False)
4.9/5 (82)
(82) Lark City donates land worth $300,000 and cash of $100,000 to Orange Corporation as an inducement to locate in the city.Four months later,Orange purchases additional land and a building at a cost of $500,000 and moves its operations to Lark City.Ann,the sole shareholder,contributes equipment (basis of $70,000 and fair market value of $200,000)to help Orange in its new operations.What are the tax consequences of these transfers to Orange Corporation?
(Essay)
4.8/5 (77)
(77) Art,an unmarried individual,transfers property (basis of $130,000 and fair market value of $120,000)to Condor Corporation in exchange for § 1244 stock.The transfer qualifies as a nontaxable exchange under § 351.Five years later,Art sells the Condor stock for $50,000.With respect to the sale,Art has:
(Multiple Choice)
4.7/5 (73)
(73) Eileen transfers property worth $200,000 (basis of $60,000)to Goldfinch Corporation.In return,she receives 80% of the stock in Goldfinch Corporation (fair market value of $180,000)and a long-term note (fair market value of $20,000)executed by Goldfinch and made payable to Eileen.Eileen recognizes gain on the transfer of:
(Multiple Choice)
4.9/5 (77)
(77) For transfers falling under § 351,what are the holding period rules for stock received by the shareholder and for the assets transferred to the corporation?
(Essay)
4.8/5 (82)
(82) Trish and Ron form Pine Corporation.Trish transfers inventory (basis of $60,000 and fair market value of $110,000)for 50% of the stock in Pine.Ron transfers machinery (basis of $20,000 and fair market value of $60,000)and agrees to serve as manager of Pine Corporation for one year for 50% of the stock.What are the tax consequences to Trish,Ron,and Pine Corporation?
(Essay)
4.9/5 (73)
(73) Blue Corporation made loans to a customer,Cedar Corporation.In the current year,these loans become worthless.
(Multiple Choice)
4.9/5 (76)
(76) Gabriella and Juanita form Luster Corporation,each receiving 50 shares of its stock.Gabriella transfers cash of $50,000,while Juanita transfers a secret process (basis of zero and a fair market value of $50,000).Neither Gabriella nor Juanita recognizes gain as a result of these transfers.
(True/False)
4.8/5 (78)
(78) A shareholder's holding period for stock received under § 351 includes the holding period of the property transferred to the corporation.
(True/False)
4.8/5 (80)
(80) Shawn,a sole proprietor,is engaged in a service business and uses the cash basis of accounting.In the current year,Shawn incorporates his business by forming Aqua Corporation.In exchange for all of its stock,Aqua receives: assets (basis of $380,000 and fair market value of $1.8 million),trade accounts payable of $125,000,and loan due to a bank of $375,000.The proceeds from the bank loan were used by Shawn to provide operating funds for the business.Aqua Corporation assumes all of the liabilities transferred to it.
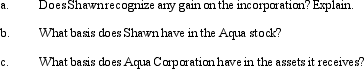
(Essay)
4.9/5 (80)
(80) Stock in Merlin Corporation is held equally by Jane,Eve,and Fred.Merlin seeks additional capital to buy a valuable tract of land that will cost $6,000,000.Jane,Eve,and Fred propose to loan Merlin $2,000,000 each,taking from Merlin a $2,000,000 ten-year note with interest payable annually at five points above the prime rate.Merlin Corporation has current taxable income of $7,000,000.How are the payments on the notes treated for tax purposes?
(Essay)
4.8/5 (72)
(72) When depreciable property is transferred to a controlled corporation under § 351,any recapture potential disappears and does not carry over to the corporation.
(True/False)
4.8/5 (77)
(77) Jane and Walt form Yellow Corporation.Jane transfers equipment worth $950,000 (basis of $200,000)and cash of $50,000 to Yellow Corporation for 50% of its stock.Walt transfers a building and land worth $1,050,000 (basis of $400,000)for 50% of Yellow's stock and $50,000 cash.
(Multiple Choice)
4.9/5 (86)
(86) Carl transfers land to Cardinal Corporation for 90% of the stock in Cardinal Corporation worth $20,000 plus a note payable to Carl in the amount of $40,000 and the assumption by Cardinal Corporation of a mortgage on the land in the amount of $100,000.The land,which has a basis to Carl of $70,000,is worth $160,000.
(Multiple Choice)
4.9/5 (71)
(71) Issues relating to basis arise when a taxpayer is involved in a § 351 transaction.Describe the underlying rules,and the purpose they serve.
(Essay)
4.8/5 (85)
(85) In return for legal services rendered incident to its formation,Crimson Corporation issues stock to Greta,an attorney.Crimson cannot immediately deduct the value of this stock but must treat it as a capital expenditure.
(True/False)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)