



 Chat with AI
Exam 18: Corporations: Organization and Capital Structure

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


A taxpayer transfers assets and liabilities to a corporation in return for its stock.If the liabilities exceed the basis of the assets transferred,the taxpayer will have a negative basis in the stock.
(True/False)
4.7/5  (82)
(82) Leah transfers equipment (basis of $400,000 and fair market value of $500,000)for additional stock in Crow Corporation.After the transfer,Leah owns 80% of Crow's stock.Associated with the equipment is § 1245 depreciation recapture potential of $70,000.As a result of the transfer:
(Multiple Choice)
4.7/5 (74)
(74) Art,an unmarried individual,transfers property (basis of $130,000 and fair market value of $120,000)to Condor Corporation in exchange for § 1244 stock.The transfer qualifies as a nontaxable exchange under § 351 and Art's basis in the Condor stock is $130,000.Five years later,Art sells the Condor stock for $50,000.With respect to the sale,Art has:
(Multiple Choice)
4.8/5 (61)
(61) Gabriella and Juanita form Luster Corporation.Gabriella transfers cash of $50,000 for 50 shares of stock,while Juanita transfers a secret process (basis of zero and fair market value of $50,000)for 50 shares of stock.
(Multiple Choice)
4.9/5 (79)
(79) When consideration is transferred to a corporation in return for stock,the definition of "property" is important because tax deferral treatment of § 351 is available only to taxpayers who transfer property.
(True/False)
4.8/5 (85)
(85) Ronald,a cash basis taxpayer,incorporates his sole proprietorship.He transfers the following items to newly created Robin Corporation. 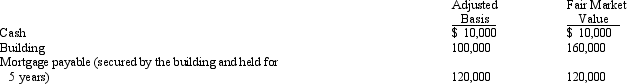 With respect to this transaction:
 (Multiple Choice)
4.8/5 (90)
(90) The receipt of nonqualified preferred stock in exchange for the transfer of appreciated property to a controlled corporation results in recognition of gain to the transferor.
(True/False)
4.9/5 (78)
(78) Earl and Mary form Crow Corporation.Earl transfers property,basis of $200,000 and value of $1,600,000,for 50 shares in Crow Corporation.Mary transfers property,basis of $80,000 and value of $1,480,000,and agrees to serve as manager of Crow for one year;in return Mary receives 50 shares of Crow.The value of Mary's services is $120,000.With respect to the transfers:
(Multiple Choice)
4.8/5 (90)
(90) When a taxpayer incorporates her business,she transfers several liabilities to the corporation.If one of the liabilities is personal in nature,only that liability is treated as boot.
(True/False)
4.8/5 (86)
(86) Sarah and Tony (mother and son)form Dove Corporation with the following investments: cash by Sarah of $55,000;land by Tony (basis of $35,000 and fair market value of $45,000).Dove Corporation issues 200 shares of stock,100 each to Sarah and Tony.Thus,each receives stock in Dove worth $50,000.
(Multiple Choice)
4.9/5 (77)
(77) Juan exchanges property,basis of $200,000 and fair market value of $2.5 million,for 65% of the stock of Green Corporation.The other 35% is owned by Gloria who acquired it several years ago.What are the tax consequences to the parties involved?
(Essay)
4.8/5 (72)
(72) Four years ago,Don,a single taxpayer,acquired stock in a corporation that qualified as a small business corporation under § 1244,at a cost of $60,000.Don wants to give his son,Ron,$20,000 to help finance Ron's college education.The stock is currently worth $20,000.Don is considering selling the stock in the current year for $20,000 and giving the cash to Ron.As an alternative,Don could give the stock to Ron and let Ron sell it for $20,000.Which alternative should Don choose?
(Essay)
4.9/5 (77)
(77) A shareholder contributes land to his wholly owned corporation but receives no stock in return.The corporation has a zero basis in the land.
(True/False)
4.8/5 (79)
(79) Penny,Miesha,and Sabrina transfer property to Owl Corporation for 75% of its stock.Nancy,their attorney,receives 25% of the stock in Owl for legal services rendered in incorporating the business.What are the tax consequences of these transactions? How should this be handled?
(Essay)
4.9/5 (79)
(79) In order to retain the services of Eve,a key employee in Ted's sole proprietorship,Ted contracts with Eve to make her a 30% owner.Ted incorporates the business receiving in return 100% of the stock.Three days later,Ted transfers 30% of the stock to Eve.Under these circumstances,§ 351 will not apply to the incorporation of Ted's business.
(True/False)
4.9/5 (71)
(71) In determining whether § 357(c)applies,assess whether the liabilities involved exceed the bases of all assets a shareholder transfers to the corporation.
(True/False)
4.9/5 (81)
(81) In order to encourage the development of an industrial park,a county donates land to Ecru Corporation.The donation does not result in gross income to Ecru.
(True/False)
4.9/5 (76)
(76) A taxpayer may never recognize a loss on the transfer of property in a transaction subject to § 351.
(True/False)
4.9/5 (66)
(66) To help avoid the thin capitalization problem,it is advisable to make the repayment of the debt contingent upon the corporation's earnings.
(True/False)
4.9/5 (80)
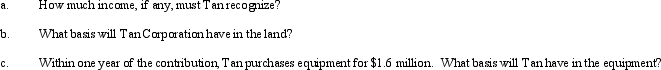
(80) Tan Corporation desires to set up a manufacturing facility in the western part of the United States.After considerable negotiations with Butte,Montana,Tan accepts the following offer: land (fair market value of $4.5 million)and cash of $1.5 million.
(Essay)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)