



 Chat with AI
Exam 22: S Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


Depletion in excess of basis in property causes a(n)____________________ adjustment to an S shareholder's basis.

Free
(Short Answer)
4.7/5  (84)
(84) Correct Answer: Verified
upward or increase
The § 1374 tax is a corporate-level tax on any built-in gain recognized in 2010 when an S corporation disposes of an asset in a taxable disposition within 7 tax years after the date on which the S election took effect.
Free
(True/False)
4.8/5 (74)
(74) Correct Answer:Verified
VerifiedTrue
Randall owns 800 shares in Fabrication,Inc. ,an S corporation in Moss Hill,Texas.In 2010,his basis in his stock is $30,000,before the adjustment for this year's losses.During 2010,Randall's share of the corporation's ordinary loss is $20,000 and his share of its capital loss is $15,000.How much can Randall deduct due to these losses?
Free
(Multiple Choice)
4.9/5 (85)
(85) Correct Answer:Verified
VerifiedC
S corporations are treated much like ____________________ for tax purposes.
(Short Answer)
4.9/5 (88)
(88) A capital loss allocated to a shareholder always reduces the other adjustments account.
(True/False)
4.8/5 (73)
(73) Pass-through S corporation losses can reduce the basis in the shareholder's loan to the entity,but distributions do not.
(True/False)
4.7/5 (72)
(72) Which equity arrangement would stop a corporation from being an S corporation?
(Multiple Choice)
4.9/5 (94)
(94) An S corporation may not have a ____________________ alien shareholder.
(Short Answer)
5.0/5 (77)
(77) Fred is the sole shareholder of an S corporation in Fort Deposit,Alabama.At a time when his stock basis is $10,000,the corporation distributes appreciated property worth $100,000 (basis of $10,000).There is no built-in gain.Fred's taxable gain is:
(Multiple Choice)
4.9/5 (79)
(79) Apple,Inc. ,a cash basis S corporation in Orange,Texas,formerly was a C corporation.Apple has the following assets and liabilities on January 1,2010,the date the S election is made. 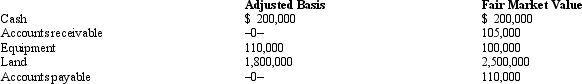 During 2010,Apple collects the accounts receivable and pays the accounts payable.The land is sold for $3 million,and taxable income for the year is $590,000.What is Apple's built-in gains tax?
 (Multiple Choice)
4.9/5 (81)
(81) An S corporation shareholder's basis includes his or her direct investments plus a ratable share of any corporate liabilities.
(True/False)
4.8/5 (84)
(84) Any distribution of cash or property by a corporation that does not exceed the balance of AAA with respect to the stock during a post-termination transition period of approximately one year is applied against and reduces the adjusted basis of the stock.
(True/False)
4.8/5 (84)
(84) Dawn Adams owns 60% of a calendar year S corporation during 2010.Her stock basis on December 31,2009 is $17,000,and her debt basis is $2,000.If the S corporation incurs a $48,000 loss for 2010,what amount may Ms.Adams deduct on her individual tax return?
(Essay)
4.9/5 (87)
(87) An S corporation reports $10,000 DPGR and $7,500 of wages,and the S corporation's QPAI is $2,500.Shelly has a 50% interest in the S corporation.All expenses that reduce DPGR are from wages,and all wages paid relate to DPGR.How much QPAI and wages are allocated to Shelly?
(Multiple Choice)
4.8/5 (85)
(85) An S corporation in Lawrence,Kansas has a recognized built-in gain of $110,000 and taxable income of $98,000.The company has an $8,000 NOL carryforward from a C corporation year,and a $9,000 business credit carryforward from a C corporation year.The built-in gains tax liability is:
(Multiple Choice)
4.9/5 (70)
(70) Net operating losses incurred before an S election do not flow through to the shareholders once the election is in effect.
(True/False)
4.9/5 (67)
(67) A two-or-more member LLC operates under partnership tax principles.
(True/False)
5.0/5 (98)
(98) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)