



 Chat with AI
Exam 22: S Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


Quadrant,Inc. ,is a former C corporation whose first S corporation year began on January 1,2010.At that time,Quadrant had two assets: X,with a value of $1,000 and a basis of $400;and Y,with a value of $400 and a basis of $600.The net unrealized built-in gain as of January 1,2010,is $400 (i.e. ,X's $600 gain less Y's $200 loss).Asset X is sold for $1,200 during 2010,and asset Y is retained.The recognized built-in gain in 2010 is:
(Multiple Choice)
4.8/5  (74)
(74) Which,if any,of the following can be eligible shareholders of an S corporation?
(Multiple Choice)
4.7/5 (88)
(88) If a resident alien shareholder moves outside the U.S. ,the S election is terminated.
(True/False)
4.8/5 (92)
(92) Which statement is incorrect with respect to an S shareholder's consent?
(Multiple Choice)
4.7/5 (76)
(76) On January 2,2009,David loans his S corporation $10,000.By the end of 2009,David's stock basis is zero,and the basis in his note has been reduced to $8,000.During 2010,the company's operating income is $10,000.The company also makes distributions to David of $8,000.Which statement is correct?
(Multiple Choice)
5.0/5 (74)
(74) An item that appears in the "Other Adjustments Account" affects stock basis,but not AAA,such as tax-exempt life insurance proceeds.
(True/False)
4.8/5 (82)
(82) Individuals Adam and Bonnie form an S corporation,with Adam contributing cash of $100,000 for a 50% interest and Bonnie contributing appreciated ordinary income property with an adjusted basis of $20,000 and a fair market value of $100,000.
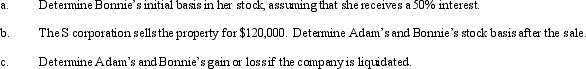
(Essay)
4.9/5 (72)
(72) A C corporation elects S status.The corporation may be subject to a built-in gains tax on which of the following assets?
(Multiple Choice)
4.9/5 (75)
(75) A calendar year C corporation has a $39,000 NOL in 2009,but elects S status for 2010 and generates an NOL of $30,000 in 2010.At all times during 2010,the stock of the corporation was owned by the same 10 shareholders,each of whom owned 10% of the stock.Kris,one of the 10 shareholders,has an adjusted stock basis of $2,300 at the beginning of 2010.What amount of the loss,if any,is deductible by Kris in 2010?
(Multiple Choice)
4.8/5 (70)
(70) Any distribution made by an S corporation during a tax year is taken into account before accounting for the year's losses.
(True/False)
4.9/5 (86)
(86) Any losses that are suspended under the at-risk rules are carried forward and are available during an S corporation's post-termination period.
(True/False)
4.8/5 (70)
(70) Which statement is incorrect with respect to filing for an S election?
(Multiple Choice)
4.8/5 (87)
(87) With respect to passive losses,there are three classes of income,losses,and credits: ____________________,____________________,and passive.
or
(Short Answer)
4.9/5 (77)
(77) During 2010,Lion Corporation incurs the following transactions.  Lion maintains a valid S election and does not distribute any assets (cash or property)to its sole shareholder,Penny.As a result,Penny must recognize:
 (Multiple Choice)
4.8/5 (68)
(68) An S corporation recognizes a gain on any distribution of ____________________ property.
(Short Answer)
4.7/5 (79)
(79) Several individuals acquire assets on behalf of Skip Corporation on May 28,2010,purchased assets on June 3,2010,and begin doing business on June 11,2010.They subscribe to shares of stock,file articles of incorporation for Skip,and become shareholders on June 21,2010.The S election must be filed no later than 2 1/2 months after:
(Multiple Choice)
4.9/5 (73)
(73) Your client is a C corporation that wishes to convert to S status.Advise this corporation with respect to minimizing any § 1374 built-in gains tax.
(Essay)
4.8/5 (75)
(75) The passive loss limitations apply at the S corporation shareholder level.
(True/False)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)