



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes419 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods266 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care334 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade379 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, Production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting276 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: GDP: Measuring Total Production and Income266 Questions
Exam 20: Unemployment and Inflation292 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies268 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run306 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 25: Money, Banks, and the Federal Reserve System280 Questions
Exam 26: Monetary Policy277 Questions
Exam 27: Fiscal Policy303 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System262 Questions
Select questions type


Figure 12-9 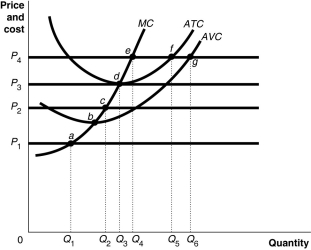 Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Market supply is found by
Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Market supply is found by (Multiple Choice)
4.8/5  (80)
(80) Figure 12-9 Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9. At price P4, the firm would
Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9. At price P4, the firm would (Multiple Choice)
4.9/5 (78)
(78) A firm would decide to shut down if its production resulted in
(Multiple Choice)
4.9/5 (75)
(75) Figure 12-4 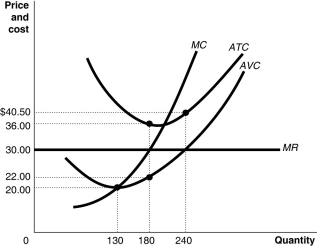 Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-A perfectly competitive firm earns a profit when price is
Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-A perfectly competitive firm earns a profit when price is (Multiple Choice)
4.8/5 (82)
(82) If a perfectly competitive firm raises the price it charges to consumers, which of the following is the most likely outcome?
(Multiple Choice)
4.8/5 (63)
(63) Table 12-2
 Table 12-2 lists the various pounds (lbs.) of apples that Margie Stattler can sell. Assume that Margie operates in a perfectly competitive market.
-Refer to Table 12-2. What is Margie's total revenue if she sells 250 pounds of apples?
Table 12-2 lists the various pounds (lbs.) of apples that Margie Stattler can sell. Assume that Margie operates in a perfectly competitive market.
-Refer to Table 12-2. What is Margie's total revenue if she sells 250 pounds of apples? (Multiple Choice)
4.8/5 (77)
(77) Which of the following describes a situation in which a good or service is produced at the lowest possible cost?
(Multiple Choice)
4.9/5 (86)
(86) Table 12-1
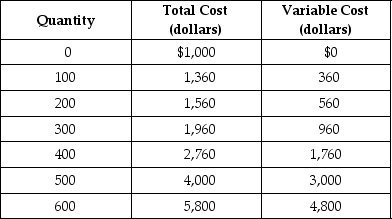 Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1. If the market price of each camera case is $8 and the firm maximizes profit, what is the amount of the firm's profit or loss?
Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1. If the market price of each camera case is $8 and the firm maximizes profit, what is the amount of the firm's profit or loss? (Multiple Choice)
4.8/5 (89)
(89) The demand curve for each seller's product in perfect competition is horizontal at the market price because
(Multiple Choice)
5.0/5 (78)
(78) If in the long run a firm makes zero profit, it should exit the industry.
(True/False)
4.9/5 (79)
(79) Of the following industries, which are perfectly competitive? For those that are not perfectly competitive, explain why.
a. Restaurants
b. Corn
c. College education
d. Local radio and television
(Essay)
4.8/5 (87)
(87) A perfectly competitive wheat farmer in a constant-cost industry produces 3,000 bushels of wheat at a total cost of $36,000. The prevailing market price is $15. What will happen to the market price of wheat in the long run?
(Multiple Choice)
4.9/5 (79)
(79) Assume that the LCD and plasma television sets industry is perfectly competitive. Suppose a producer develops a successful innovation that enables it to lower its cost of production. What happens in the short run and in the long run?
(Multiple Choice)
4.9/5 (73)
(73) Figure 12-9 Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9. At price P4, the firm would produce
Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9. At price P4, the firm would produce (Multiple Choice)
4.7/5 (83)
(83) What is the relationship among the following variables in for a perfectly competitive firm: the market price, average revenue and marginal revenue?
(Multiple Choice)
4.8/5 (73)
(73) Figure 12-6  Figure 12-6 shows the demand, marginal cost (MC) and average total cost (ATC) curves for Jason's House of Apples.
-Refer to Figure 12-6. To maximize his profit, Jason should produce the rate of output indicated by point
Figure 12-6 shows the demand, marginal cost (MC) and average total cost (ATC) curves for Jason's House of Apples.
-Refer to Figure 12-6. To maximize his profit, Jason should produce the rate of output indicated by point (Multiple Choice)
4.8/5 (76)
(76) Suppose Veronica sells teapots in the perfectly competitive teapot market. Her output per day and her costs are as follows:
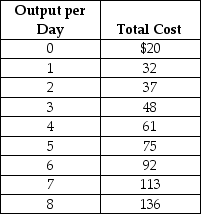 Suppose the current equilibrium price in the teapot market is $20. To maximize profit, how many teapots will Veronica produce, what price will she charge, and how much profit (or loss) will she make? Draw a graph to illustrate your answer. Your graph should include Veronica's demand, ATC, AVC, MC, and MR curves, the price she is charging, the quantity she is producing, and the area representing her profit (or loss).
 (Essay)
4.8/5 (88)
(88) In a decreasing-cost industry, the entry of new firms lowers average cost at each level of output.
(True/False)
4.8/5 (73)
(73) A constant cost, perfectly competitive market is in long-run equilibrium. At present, there are 1,000 firms each producing 400 units of output. The price of the good is $60. Now suppose there is a sudden increase in demand for the industry's product which causes the price of the good to rise to $64. In the new long-run equilibrium, how will the average total cost of producing the good compare to what it was before the price of the good rose?
(Multiple Choice)
4.8/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)