



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes419 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods266 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care334 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade379 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, Production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting276 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: GDP: Measuring Total Production and Income266 Questions
Exam 20: Unemployment and Inflation292 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies268 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run306 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 25: Money, Banks, and the Federal Reserve System280 Questions
Exam 26: Monetary Policy277 Questions
Exam 27: Fiscal Policy303 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System262 Questions
Select questions type


Figure 12-5  Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5. If the market price is $20, what is the amount of the firm's profit?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5. If the market price is $20, what is the amount of the firm's profit? (Multiple Choice)
4.9/5  (70)
(70) Figure 12-2  -Refer to Figure 12-2. What happens if the firm produces more than Q4 units?
 (Multiple Choice)
4.8/5 (72)
(72) Ethan Nicholas, who developed the iShoot application for the iPhone 3G, found that to maintain sales in a profitable competitive market, the price of a product
(Multiple Choice)
4.8/5 (89)
(89) Consider the market for wheat which is a perfectly competitive market. Is the market demand curve the same as the demand curve facing an individual producer? If not, explain how and why they are different? Illustrate your answer graphically.
(Essay)
4.8/5 (66)
(66) Figure 12-9 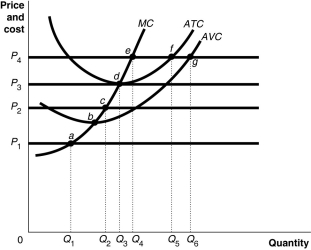 Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9. At price P1, the firm would produce
Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9. At price P1, the firm would produce (Multiple Choice)
5.0/5 (82)
(82) What characteristic of a competitive market has made the "long run pretty short" in the market for iPhone applications?
(Multiple Choice)
4.9/5 (89)
(89) Figure 12-16  -Refer to Figure 12-16. Which panel best represents the perfectly competitive organic produce market in which some firms are earning short-run economic profits, and the Surgeon General announces that switching from non-organic produce to organic produce will add 5 years to the average life span of consumers?
 (Multiple Choice)
4.9/5 (87)
(87) Figure 12-19 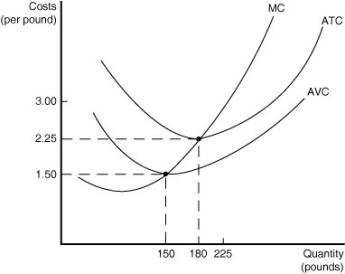 -Refer to Figure 12-19. The figure above shows the cost curves of a perfectly competitive firm in the coffee market. Use the graph in Figure 12-19 to answer the following questions. Assume the market price is $3 per pound.
a. What is the lowest price at which the coffee grower will supply output in the short run?
b. In the diagram draw the firm's demand curve (label this "MR" for marginal revenue).
c. What is the firm's profit-maximizing output?
d. Is the firm earning a profit or a loss? Identify the area in the graph that represents the firm's profit or loss.
e. Explain how entry or exit will occur in the market to ensure that firms will break even in the long run.
-Refer to Figure 12-19. The figure above shows the cost curves of a perfectly competitive firm in the coffee market. Use the graph in Figure 12-19 to answer the following questions. Assume the market price is $3 per pound.
a. What is the lowest price at which the coffee grower will supply output in the short run?
b. In the diagram draw the firm's demand curve (label this "MR" for marginal revenue).
c. What is the firm's profit-maximizing output?
d. Is the firm earning a profit or a loss? Identify the area in the graph that represents the firm's profit or loss.
e. Explain how entry or exit will occur in the market to ensure that firms will break even in the long run. (Essay)
4.9/5 (78)
(78) The long-run supply curve for a perfectly competitive, constant-cost industry
(Multiple Choice)
5.0/5 (100)
(100) If, for a given output level, a perfectly competitive firm's price is less than its average variable cost, the firm
(Multiple Choice)
4.8/5 (80)
(80) An individual seller in perfect competition will not sell at a price lower than the market price because
(Multiple Choice)
4.9/5 (65)
(65) A perfectly competitive firm produces 3,000 units of a good at a total cost of $36,000. The price of each good is $10. Calculate the firm's short-run profit or loss.
(Multiple Choice)
4.9/5 (82)
(82) Assuming a market price of $4, fill in the columns in the following table. What is the profit-maximizing level of production? What are the two ways to determine the profit-maximizing level of production?
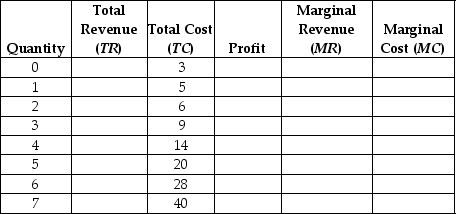
(Essay)
4.8/5 (80)
(80) If a firm's total variable cost exceeds its total revenue, the firm should stop production by shutting down temporarily.
(True/False)
4.9/5 (80)
(80) Figure 12-5 Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5. The firm's manager suggests that the firm's goal should be to maximize average profit. In that case, what is the output level and what is the average profit that will achieve the manager's goal?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5. The firm's manager suggests that the firm's goal should be to maximize average profit. In that case, what is the output level and what is the average profit that will achieve the manager's goal? (Multiple Choice)
4.8/5 (91)
(91) The delivery of first-class mail by the U.S. Postal Service is an example of
(Multiple Choice)
4.9/5 (86)
(86) In early 2007, Pioneer and JVC, two Japanese electronics firms, each announced that their profits were going to be lower than expected because they both had to cut prices for LCD and plasma television sets. Which of the following could explain why these firms did not simply raise their prices and increase their profits?
(Multiple Choice)
4.9/5 (74)
(74) If, as a perfectly competitive industry expands, it can supply larger quantities only at a higher long-run equilibrium price, it is
(Multiple Choice)
4.9/5 (91)
(91) Figure 12-1 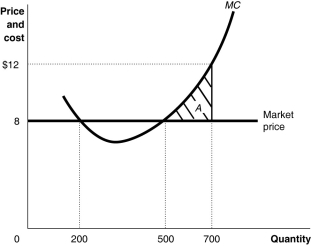 -Refer to Figure 12-1. If the firm is producing 500 units, what is the amount of its profit or loss?
 (Multiple Choice)
4.7/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)