



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes419 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods266 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care334 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade379 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, Production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting276 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: GDP: Measuring Total Production and Income266 Questions
Exam 20: Unemployment and Inflation292 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies268 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run306 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 25: Money, Banks, and the Federal Reserve System280 Questions
Exam 26: Monetary Policy277 Questions
Exam 27: Fiscal Policy303 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System262 Questions
Select questions type


Figure 12-2  -Refer to Figure 12-2. What is the amount of profit if the firm produces Q2 units?
 (Multiple Choice)
4.8/5  (83)
(83) A perfectly competitive industry achieves allocative efficiency because
(Multiple Choice)
4.8/5 (70)
(70) Maximizing average profit is equivalent to maximizing total profit.
(True/False)
4.9/5 (73)
(73) If a firm in a perfectly competitive industry experiences persistent losses, in the long run it should
(Multiple Choice)
4.9/5 (78)
(78) Article Summary
According to the Department of Agriculture, net farm income will grow to a record high of $120.6 billion in 2013, up from the previous high mark in 2011 and after adjusting for inflation, its second highest level since 1973. Net cash income, however, is expected to fall by 10 percent due to unsold inventories. Exports of chickens and milk are expected to rise by 3 percent and 17 percent, respectively.
Source: Ros Krasny, "Farm income poised for record 2013: USDA," Reuters, August 27, 2013.
-Assume that after the record year for U.S. farm income in 2013, farmers are expected to break even in 2014. This means that at the quantity being produced in 2014,
(Multiple Choice)
4.8/5 (82)
(82) A perfectly competitive firm in a constant-cost industry produces 1,000 units of a good at a total cost of $50,000. If the prevailing market price is $48, the number of firms and the industry's output will decrease in the long run.
(True/False)
4.9/5 (75)
(75) Figure 12-10 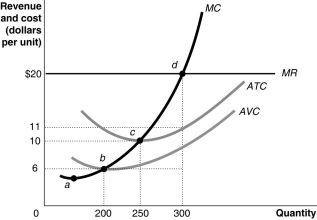 -Refer to Figure 12-10. The firm's short-run supply curve is its
 (Multiple Choice)
4.8/5 (78)
(78) If, for the last bushel of apples produced and sold by an apple farm marginal revenue exceeds marginal cost, then in producing that bushel the farm
(Multiple Choice)
5.0/5 (88)
(88) Apple introduced its iPhone 3G in July 2008 and within a month sales had topped 3 million units. By April 2009, more than 25,000 apps for the iPhone 3G were available in the iTunes store, an indication that in a competitive market,
(Multiple Choice)
4.8/5 (69)
(69) If, for a perfectly competitive firm, price exceeds the marginal cost of production, the firm should
(Multiple Choice)
4.9/5 (86)
(86) Figure 12-1 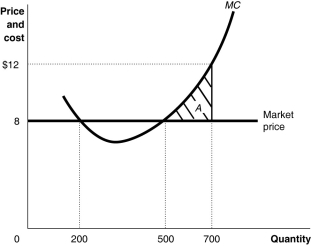 -Refer to Figure 12-1. If the firm is charging a price of $12 per unit,
 (Multiple Choice)
4.8/5 (77)
(77) If price = marginal cost at the output produced by a perfectly competitive firm and the firm is earning an economic profit, then
(Multiple Choice)
4.8/5 (70)
(70) Suppose the equilibrium price in a perfectly competitive industry is $15 and a firm in the industry charges $21. Which of the following will happen?
(Multiple Choice)
4.8/5 (69)
(69) What assumptions are necessary for a market to be perfectly competitive? Explain why each of these assumptions is important.
(Essay)
4.9/5 (72)
(72) Perfect competition is characterized by all of the following except
(Multiple Choice)
4.8/5 (87)
(87) If price is equal to average variable cost, a perfectly competitive firm breaks even.
(True/False)
4.9/5 (69)
(69) Figure 12-1
-Refer to Figure 12-1. If the firm is producing 700 units,
-Refer to Figure 12-1. If the firm is producing 700 units, (Multiple Choice)
5.0/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)