



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes419 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods266 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care334 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade379 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, Production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting276 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: GDP: Measuring Total Production and Income266 Questions
Exam 20: Unemployment and Inflation292 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies268 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run306 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 25: Money, Banks, and the Federal Reserve System280 Questions
Exam 26: Monetary Policy277 Questions
Exam 27: Fiscal Policy303 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System262 Questions
Select questions type


Figure 12-10 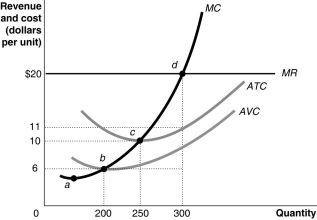 -In the short run, if a firm shuts down, it avoids its variable cost but not its fixed cost.
 (True/False)
4.8/5  (73)
(73) To maximize profit, a firm will produce the level of output where MR = MC. If a firm actually makes a profit depends on the relationship of price to average total cost. What are the three possible relationships between price and average total cost that determine if a firm will make a profit, experience a loss, or break even?
(Essay)
4.8/5 (81)
(81) Figure 12-16  -Refer to Figure 12-16. Which panel best represents the perfectly competitive organic produce market in which some firms are experiencing short-run losses, and consumers are displaying an increased preference for organic produce?
 (Multiple Choice)
4.7/5 (79)
(79) Figure 12-17  The graphs in Figure 12-17 represent the perfectly competitive market demand and supply curves for the apple industry and demand and cost curves for a typical firm in the industry.
-Refer to Figure 12-17. Which of the following statements is true?
The graphs in Figure 12-17 represent the perfectly competitive market demand and supply curves for the apple industry and demand and cost curves for a typical firm in the industry.
-Refer to Figure 12-17. Which of the following statements is true? (Multiple Choice)
4.8/5 (81)
(81) A wheat farmer and a firm in a perfectly competitive market are similar in that
(Multiple Choice)
4.9/5 (69)
(69) Table 12-3
 Arnie sells basketballs in a perfectly competitive market. Table 12-3 summarizes Arnie's output per day (Q), total cost (TC), average total cost (ATC) and marginal cost (MC).
-Refer to Table 12-3. What price (P) will Arnie charge and how much profit will he earn if the market price of basketballs is $12.50?
Arnie sells basketballs in a perfectly competitive market. Table 12-3 summarizes Arnie's output per day (Q), total cost (TC), average total cost (ATC) and marginal cost (MC).
-Refer to Table 12-3. What price (P) will Arnie charge and how much profit will he earn if the market price of basketballs is $12.50? (Multiple Choice)
4.9/5 (96)
(96) Which of the following is the best example of a perfectly competitive firm?
(Multiple Choice)
4.8/5 (84)
(84) If a perfectly competitive firm's total revenue is less than its total variable cost, the firm
(Multiple Choice)
4.9/5 (94)
(94) What is a long-run supply curve? What does a long-run supply curve look like on a perfectly competitive market graph?
(Essay)
4.7/5 (81)
(81) Figure 12-11  -Refer to Figure 12-11. If this is a constant-cost industry, what is the market price in the long-run equilibrium?
 (Multiple Choice)
4.8/5 (67)
(67) Figure 12-14 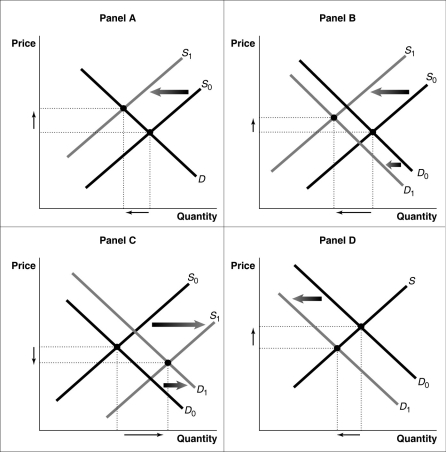 -Refer to Figure 12-14. Consider a typical firm in a perfectly competitive industry which is incurring short-run losses. Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.9/5 (74)
(74) Suppose there are economies of scale in the production of a specialized memory chip that is used in manufacturing microwaves. This suggests that the microwave industry is a decreasing-cost industry.
(True/False)
4.8/5 (89)
(89) If the market price is $40, the average revenue of selling five units is
(Multiple Choice)
4.9/5 (81)
(81) What is meant by productive efficiency? How does a perfectly competitive firm achieve productive efficiency?
(Essay)
4.9/5 (68)
(68) Under what conditions should a competitive firm shut down in the short run?
(Essay)
4.9/5 (76)
(76) Figure 12-9 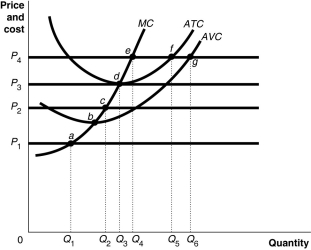 Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9. At price P2, the firm would produce
Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9. At price P2, the firm would produce (Multiple Choice)
4.8/5 (76)
(76) Max Shreck, an accountant, quit his $80,000-a-year job and bought an existing tattoo parlor from its previous owner, Sylvia Sidney. The lease has five years remaining and requires a monthly payment of $4,000. Max's explicit cost amounts to $3,000 per month more than his revenue. Should Max continue operating his business?
(Multiple Choice)
4.9/5 (83)
(83) Which of the following is not an assumption of perfectly competitive markets?
(Multiple Choice)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)