



 Chat with AI
Exam 18: Corporations: Organization and Capital Structure

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


To ease a liquidity problem, all of the shareholders of Osprey Corporation contribute additional cash to its capital.Osprey has no tax consequences from the contribution.
(True/False)
4.8/5  (70)
(70) Shawn transfers property (basis of $40,000 and fair market value of $35,000) to Condor Corporation in exchange for § 1244 stock. The transfer qualifies as a nontaxable exchange under § 351; therefore, Shawn's basis in the Condor stock is $40,000. Five years later, Shawn sells the Condor stock for $25,000. With respect to the sale, Shawn has:
(Multiple Choice)
4.7/5 (87)
(87) Tara incorporates her sole proprietorship, transferring it to newly formed Black Corporation.The assets transferred have an adjusted basis of $240,000 and a fair market value of $300,000.Also transferred was $10,000 in liabilities, $1,000 of which was personal and the balance of $9,000 being business related.In return for these transfers, Tara receives all of the stock in Black Corporation.
(Multiple Choice)
4.8/5 (70)
(70) A shareholder transfers a capital asset to Red Corporation for its stock. If the transfer qualifies under § 351, Red's holding period for the asset begins on the day of the exchange.
(True/False)
4.8/5 (78)
(78) Nancy, Guy, and Rod form Goldfinch Corporation with the following consideration.
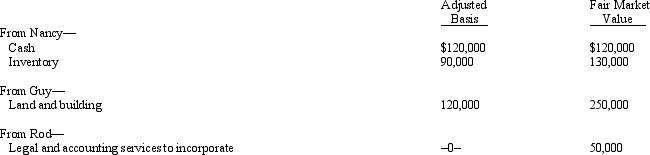 Goldfinch issues its 500 shares of stock as follows: 250 to Nancy, 200 to Guy, and 50 to Rod.In addition, Guy gets $50,000 in cash.
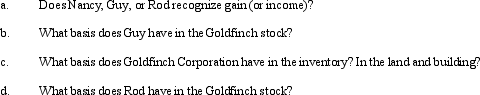
Goldfinch issues its 500 shares of stock as follows: 250 to Nancy, 200 to Guy, and 50 to Rod.In addition, Guy gets $50,000 in cash.
(Essay)
4.7/5 (79)
(79) If a shareholder owns stock received as a gift from her mother, it cannot be § 1244 stock.
(True/False)
4.9/5 (86)
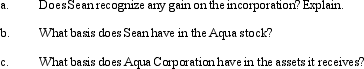
(86) Sean, a sole proprietor, is engaged in a service business and uses the cash basis of accounting.In the current year, Sean incorporates his business by forming Aqua Corporation.In exchange for all of its stock, Aqua receives: assets (basis of $400,000 and fair market value of $2 million), trade accounts payable of $110,000, and loan due to a bank of $390,000.The proceeds from the bank loan were used by Sean to provide operating funds for the business.Aqua Corporation assumes all of the liabilities transferred to it.
(Essay)
4.9/5 (70)
(70) Amy owns 20% of the stock of Wren Corporation, which she acquired several years ago at a cost of $10,000.Amy is Vice-President of Wren and earns a salary of $80,000 annually.Last year, Wren Corporation was experiencing financial problems, and Amy loaned the corporation $25,000.In the current year, Wren becomes bankrupt, and both her stock investment and the loan become worthless.Amy has a nonbusiness bad debt deduction this year of $25,000.
(True/False)
4.8/5 (77)
(77) Five years ago, Joe, a single taxpayer, acquired stock in a corporation that qualified as a small business corporation under § 1244, at a cost of $55,000.Joe wants to give his son, Jake, $15,000 to help finance Jake's college education.The stock is currently worth $15,000.Joe is considering selling the stock in the current year for $15,000 and giving the cash to Jake.As an alternative, Joe could give the stock to Jake and let Jake sell it for $15,000.Which alternative should Joe choose?
(Essay)
4.8/5 (83)
(83) The receipt of nonqualified preferred stock in exchange for the transfer of appreciated property to a controlled corporation results in recognition of gain to the transferor.
(True/False)
4.9/5 (80)
(80) In 2005, Donna transferred assets (basis of $300,000 and fair market value of $250,000) to Egret Corporation in return for 200 shares of § 1244 stock. Due to § 351, the transfer was nontaxable; therefore, Donna's basis in the Egret stock is $300,000. In 2006, Donna sells 100 of these shares to Walter (a family friend) for $100,000. In 2012, Egret Corporation files for bankruptcy, and its stock becomes worthless.
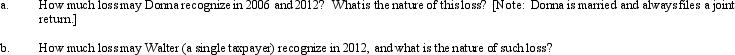
(Essay)
4.9/5 (81)
(81) Rosa, the sole shareholder of Robin Corporation, contributes land (basis of $40,000 and fair market value of $100,000) to the corporation but does not receive additional stock. Neither Rosa nor Robin Corporation will have to recognize gain as a result of this transfer.
(True/False)
4.8/5 (95)
(95) Earl and Mary form Crow Corporation.Earl transfers property, basis of $200,000 and value of $1,600,000, for 50 shares in Crow Corporation.Mary transfers property, basis of $80,000 and value of $1,480,000, and agrees to serve as manager of Crow for one year; in return Mary receives 50 shares of Crow.The value of Mary's services is $120,000.With respect to the transfers:
(Multiple Choice)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)