



 Chat with AI
Exam 18: Corporations: Organization and Capital Structure

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Lark City donates land worth $300,000 and cash of $100,000 to Orange Corporation as an inducement to locate in the city. Four months later, Orange purchases additional land and a building at a cost of $500,000 and moves its operations to Lark City. Ann, the sole shareholder, contributes equipment (basis of $70,000 and fair market value of $200,000) to help Orange in its new operations. What are the tax consequences of these transfers to Orange Corporation?
(Essay)
4.9/5  (70)
(70) When depreciable property is transferred to a controlled corporation under § 351, any recapture potential disappears and does not carry over to the corporation.
(True/False)
4.8/5 (70)
(70) Section 351 (which permits transfers to controlled corporations to be tax deferred) can be justified under the wherewithal to pay concept.
(True/False)
4.7/5 (84)
(84) Sarah and Tony (mother and son) form Dove Corporation with the following investments: cash by Sarah of $65,000; land by Tony (basis of $25,000 and fair market value of $35,000).Dove Corporation issues 400 shares of stock, 200 each to Sarah and Tony.Thus, each receives stock in Dove worth $50,000.
(Multiple Choice)
4.9/5 (78)
(78) George (an 80% shareholder) has made loans to Mountainview Corporation that become worthless in the current year. George is not employed by Mountainview.
(Multiple Choice)
4.8/5 (80)
(80) In order to encourage the redevelopment of its urban center, the city of Birmingham contributes undeveloped land (fair market value of $900,000) and cash of $350,000 to Blue Corporation. Within the year, Blue constructs a new office building at the site at a cost of $850,000.
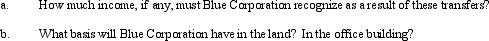
(Essay)
4.9/5 (74)
(74) Kathleen transferred the following assets to Mockingbird Corporation. 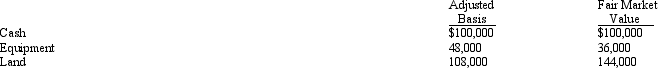 In exchange, Kathleen received 40% of Mockingbird Corporation's only class of stock outstanding.The stock has no established value.However, all parties sincerely believe that the value of the stock Kathleen received is the equivalent of the value of the assets she transferred.The only other shareholder, Rick, formed Mockingbird Corporation five years ago.
 (Multiple Choice)
4.8/5 (82)
(82) Ann transferred land worth $500,000, with a tax basis of $150,000, to Brown Corporation, an existing entity, for 200 shares of its stock.Brown Corporation has two other shareholders, Bill and Bob, each of whom holds 100 shares.With respect to the transfer:
(Multiple Choice)
4.7/5 (87)
(87) A transferor who receives stock for both property and services cannot be included in the control group in determining whether an exchange meets the requirements of § 351.
(True/False)
4.9/5 (88)
(88) Wren Corporation (a minority shareholder in Lark Corporation) has made loans to Lark Corporation that become worthless in the current year.
(Multiple Choice)
4.8/5 (78)
(78) The use of § 351 is not limited to the initial formation of a corporation, and it can apply to later transfers as well.
(True/False)
4.8/5 (69)
(69) Allen transfers marketable securities with an adjusted basis of $120,000, fair market value of $300,000, for 85% of the stock of Heron Corporation.In addition, he receives cash of $40,000.Allen recognizes a capital gain of $40,000 on the transfer.
(True/False)
4.9/5 (72)
(72) Wade and Paul form Swan Corporation with the following investments. Wade transfers machinery (basis of $40,000 and fair market value of $100,000), while Paul transfers land (basis of $20,000 and fair market value of $90,000) and services rendered (worth $10,000) in organizing the corporation. Each is issued 25 shares in Swan Corporation. With respect to the transfers:
(Multiple Choice)
5.0/5 (90)
(90) Eve transfers property (basis of $120,000 and fair market value of $400,000) to Green Corporation for 80% of its stock (worth $350,000) and a long-term note (worth $50,000), executed by Green Corporation and made payable to Eve.As a result of the transfer:
(Multiple Choice)
4.9/5 (76)
(76) What are the tax consequences if an individual investor incurs a loss on the following:
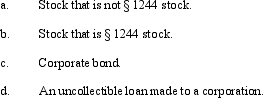
(Essay)
5.0/5 (73)
(73) Lucy and Marta form Blue Corporation. Lucy transfers land (basis of $40,000 and fair market value of $180,000) for 50 shares plus $20,000 cash. Marta transfers $160,000 cash for 50 shares in Blue Corporation.
(Multiple Choice)
4.9/5 (76)
(76) Rick transferred the following assets and liabilities to Warbler Corporation. 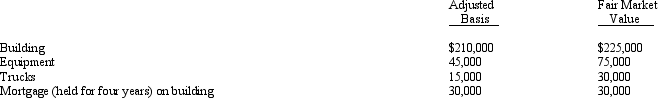 In return, Rick received $75,000 in cash plus 90% of Warbler Corporation's only class of stock outstanding (fair market value of $225,000).
 (Multiple Choice)
4.9/5 (83)
(83) What is the rationale underlying the tax deferral treatment available under § 351?
(Essay)
4.7/5 (84)
(84) When a taxpayer transfers property subject to a mortgage to a controlled corporation in an exchange qualifying under § 351, the transferor shareholder's basis in stock received in the transferee corporation is increased by the amount of the mortgage on the property.
(True/False)
4.7/5 (86)
(86) Adam transfers cash of $300,000 and land worth $200,000 to Camel Corporation for 100% of the stock in Camel.In the first year of operation, Camel has net taxable income of $70,000.If Camel distributes $50,000 to Adam:
(Multiple Choice)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)