



 Chat with AI
Exam 18: Corporations: Organization and Capital Structure

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Dick, a cash basis taxpayer, incorporates his sole proprietorship.He transfers the following items to newly created Orange Corporation. 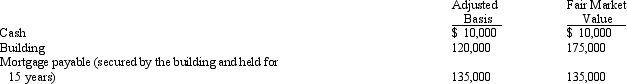 With respect to this transaction:
 (Multiple Choice)
4.8/5  (83)
(83) Dawn, a sole proprietor, was engaged in a service business and reported her income on a cash basis.Later, she incorporates her business and transfers the assets of the business to the corporation in return for all the stock in the corporation plus the corporation's assumption of the liabilities of her proprietorship.All the receivables and the unpaid trade payables are transferred to the newly formed corporation.The assets of the proprietorship had a basis of $105,000 and fair market value of $300,000.The trade accounts payable totaled $25,000.There was a note payable to the bank in the amount of $95,000 that the corporation assumes.The note was issued for the purchase of computers and other business equipment.
(Multiple Choice)
4.9/5 (77)
(77) Penny, Miesha, and Sabrina transfer property to Owl Corporation for 75% of its stock.Nancy, their attorney, receives 25% of the stock in Owl for legal services rendered in incorporating the business.What are the tax consequences of these transactions? How should this transaction have been handled?
(Essay)
4.7/5 (82)
(82) Joe and Kay form Gull Corporation.Joe transfers cash of $250,000 for 200 shares in Gull Corporation.Kay transfers property with a basis of $50,000 and fair market value of $240,000.She agrees to accept 200 shares in Gull Corporation for the property and for providing bookkeeping services to the corporation in its first year of operation.The value of Kay's services is $10,000.With respect to the transfer:
(Multiple Choice)
4.8/5 (94)
(94) Carl transfers land to Cardinal Corporation for 90% of the stock in Cardinal Corporation worth $20,000 plus a note payable to Carl in the amount of $40,000 and the assumption by Cardinal Corporation of a mortgage on the land in the amount of $100,000.The land, which has a basis to Carl of $70,000, is worth $160,000.
(Multiple Choice)
4.7/5 (83)
(83) In determining whether § 357(c) applies, assess whether the liabilities involved exceed the bases of all assets a shareholder transfers to the corporation.
(True/False)
4.9/5 (88)
(88) When forming a corporation, a transferor-shareholder may choose to receive some corporate debt along with stock. Identify some of the issues the transferor must consider when deciding whether debt should be a part of the transaction.
(Essay)
4.7/5 (95)
(95) Similar to like-kind exchanges, the receipt of "boot" under § 351 can cause gain to be recognized.
(True/False)
4.9/5 (70)
(70) Issues relating to basis arise when a taxpayer is involved in a § 351 transaction. Describe the underlying rules, and the purpose they serve.
(Essay)
4.9/5 (79)
(79) Carl and Ben form Eagle Corporation.Carl transfers cash of $50,000 for 50 shares of stock of Eagle.Ben transfers a secret process with a tax basis of zero and a fair market value of $50,000 for the remaining 50 shares in Eagle.Carl will have a tax basis of $50,000 in his stock in Eagle Corporation, but Ben's basis in his stock will be zero.
(True/False)
4.8/5 (84)
(84) In a § 351 transfer, a shareholder receives boot of $10,000 but ends up with a realized loss of $3,000.Only $7,000 of the boot will be taxed to the shareholder.
(True/False)
4.9/5 (64)
(64) Leonard transfers equipment (basis of $40,000 and fair market value of $100,000) for additional stock in Green Corporation. After the transfer, Leonard owns 90% of the stock. Leonard had claimed depreciation of $50,000 on the equipment prior to transferring it to Green Corporation. With respect to the transfer:
(Multiple Choice)
4.7/5 (80)
(80) Four individuals form Chickadee Corporation under § 351.Two of these individuals, Jane and Walt, made the following contributions: 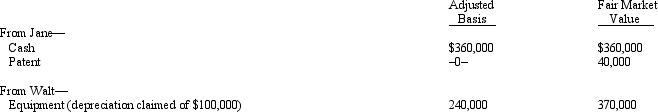 Both Jane and Walt receive stock in Chickadee Corporation equal to the value of their investments.
 (Multiple Choice)
4.8/5 (80)
(80) Kevin and Nicole form Indigo Corporation with the following transfers: inventory from Kevin (basis of $360,000 and fair market value of $400,000) and improved real estate from Nicole (basis of $320,000 and fair market value of $375,000). Nicole, an accountant, agrees to contribute her services (worth $25,000) in organizing Indigo. The corporation's stock is distributed equally to Kevin and Nicole. As a result of these transfers:
(Multiple Choice)
4.9/5 (96)
(96) A secret process and patentable invention both constitute "property" under § 351.
(True/False)
5.0/5 (80)
(80) George transfers cash of $150,000 to Finch Corporation, a newly formed corporation, for 100% of the stock in Finch worth $80,000 and debt in the amount of $70,000, payable in equal annual installments of $7,000 plus interest at the rate of 9% per annum.In the first year of operation, Finch has net taxable income of $40,000.If Finch pays George interest of $6,300 and $7,000 principal payment on the note:
(Multiple Choice)
5.0/5 (75)
(75) Barry and Irv form Rapid Corporation. Barry transfers cash of $150,000 and equipment (basis of $300,000 and fair market value of $350,000) for 50% of Rapid's stock. Irv transfers land and building (basis of $510,000 and fair market value of $425,000) and agrees to manage the business for one year for the other 50% of Rapid's stock. The value of Irv's services for one year is $75,000.
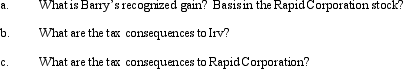
(Essay)
4.9/5 (81)
(81) A person who performs services for a corporation in exchange for stock cannot be treated as a member of the transferring group even if that person also transfers some property to the corporation.
(True/False)
4.8/5 (83)
(83) If a transaction qualifies under § 351, any recognized gain is equal to the value of the boot received.
(True/False)
4.9/5 (78)
(78) Ashley, a 70% shareholder of Wren Corporation, transfers property with a basis of $250,000 and a fair market value of $900,000 to Wren Corporation for additional stock.Ashley owns 78% of Wren after the transfer.Two other shareholders in Wren transfer a nominal amount of property to Wren along with Ashley's transfer so that Ashley and the two shareholders own 90% of the Wren stock after the transfer.Does Ashley have taxable gain on the transfer?
(Essay)
4.8/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)