



 Chat with AI
Exam 17: Tax Practice and Ethics

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Some taxpayers must make quarterly estimated payments of their income tax. Describe the structure of these requirements. In your answer, include both corporate and non-corporate taxpayers.
(Essay)
4.9/5  (70)
(70) A taxpayer penalty may be waived if there is shown to be reasonable cause for the misstatement on the tax return. The courts have applied this standard strictly. List three or more assertions for a waiver of a taxpayer penalty that courts have found not to constitute reasonable cause. Example: Ignorance of the tax law.
(Essay)
4.8/5 (62)
(62) In the case of bad debts and worthless securities, the statute of limitations on claims for refund is three years.
(True/False)
4.8/5 (67)
(67) The accuracy-related penalties typically relate to on the part of the taxpayer, or other understatements of tax.
(Short Answer)
4.7/5 (87)
(87) About % of all Forms 1040 are audited each year. The rate is about ____________________% for large corporations.
(Short Answer)
4.9/5 (83)
(83) Which of the following is subject to tax return preparer penalties?
(Multiple Choice)
4.9/5 (79)
(79) The Four Square Services Corporation estimates that its 2015 taxable income will be $1,000,000. Thus, it is subject to a flat 34% income tax rate and incurs a $340,000 liability. For each of the following independent cases, compute Four Square's minimum quarterly estimated tax payments that will avoid an underpayment penalty.
a. For 2014, taxable income was ($200,000), resulting in a zero income tax liability. Four Square carried back all of this loss to prior years.
b. For 2014, taxable income was $800,000, and tax liability was $272,000.
c. For 2013, taxable income was $2 million, and tax liability was $680,000. For 2014, taxable income was $100,000, and tax liability was $22,250.
(Essay)
4.8/5 (69)
(69) Freddie has been assessed a preparer penalty for willful and reckless conduct. When he completed Peggy's Federal income tax return (she is in the 33% tax bracket), Freddie purposely omitted $100,000 of cash receipts that should have been reported as gross income. Freddie charged Peggy $4,000 to prepare the return. What is Freddie's preparer penalty?
(Multiple Choice)
4.8/5 (79)
(79) Circular 230 requires that the tax practitioner use the "best practices" of the tax profession in carrying out a tax engagement. Specify what some of these best practices entail.
(Essay)
4.9/5 (85)
(85) Mickey, a calendar year taxpayer, was not required to file a Federal income tax return last year because his AGI was negative due to business losses. For this tax year, his AGI is $120,000 and his tax liability is $10,000. To avoid a penalty for tax underpayments for the current year, Mickey must make aggregate estimated tax payments of at least:
(Multiple Choice)
4.8/5 (63)
(63) Jenny prepared Steve's income tax returns for no compensation for 2011 and 2012. Jenny is Steve's mother. In 2014, the IRS notifies Steve that it will audit his returns for 2010-2012. Jenny cannot represent Steve during the audit of the returns, as she is not a "registered tax return preparer."
(True/False)
4.8/5 (83)
(83) An IRS "office audit" takes place at the headquarters office of the corporate taxpayer.
(True/False)
4.8/5 (61)
(61) IRS computers use document matching programs for both individuals and business taxpayers to keep the audit rate low.
(True/False)
4.9/5 (71)
(71) The tax preparer penalty for taking an unreasonable tax return position is the greater of $ or of the tax professional's income from preparing the return.
(Short Answer)
4.9/5 (79)
(79) Match each of the following tax penalties with the type of tax penalty as specified by the Code. A letter can be used more than once. The correct solution may include more than one letter.
a. Taxpayer penalty
b. Tax preparer penalty
c. Appraiser's penalty
-Aiding in preparing an improper tax return.
(Short Answer)
4.9/5 (68)
(68) A(n) must obtain a Preparer Tax Identification Number (PTIN).
(Short Answer)
4.9/5 (92)
(92) Comment on the AICPA's Statements on Standards for Tax Services. To whom do the standards apply? Are they binding or merely advisory?
(Essay)
4.8/5 (81)
(81) The Treasury document regulating the professional conduct of tax return preparers is the Regulation known as
_________________________.
(Short Answer)
4.8/5 (77)
(77) Compute the overvaluation penalty for each of the following independent cases involving the taxpayer's reporting of the fair market value of charitable contribution property. In each case, assume a marginal Federal income tax rate of 35%.
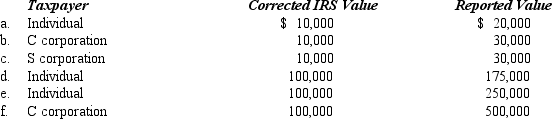
(Essay)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)