



 Chat with AI
Exam 17: Tax Practice and Ethics

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Malik, Inc., a calendar year C corporation subject to a 35% marginal income tax rate, claimed a Form 1120 charitable contribution deduction of $30,000 for a sculpture that the IRS later valued at $10,000. The applicable overvaluation penalty is:
(Multiple Choice)
4.9/5  (69)
(69) The IRS is organized according to the industry classification of the taxpayer. One of the operating divisions of the IRS deals exclusively with manufacturing and exporting businesses.
(True/False)
4.8/5 (81)
(81) Keepert uses "two sets of books." She only reports one-half of her cash sales on the records that she uses to complete her Federal income tax return. The statute of limitations for Keepert's return is six years.
(True/False)
4.8/5 (86)
(86) Circular 230 applies to all paid tax practitioners. But attorneys, CPAs, and enrolled agents are exempt from the Circular 230 rules, because each of the groups has its own code of professional conduct.
(True/False)
4.8/5 (83)
(83) Which statement is incorrect as to the conduct of IRS income tax audits?
(Multiple Choice)
4.9/5 (70)
(70) Which statement is correct as to the conduct of IRS income tax audits?
(Multiple Choice)
4.8/5 (76)
(76) Minnie, your tax client, has decided to dispute the Revenue Agent's Report. List and discuss at least four of your "next steps" as you prepare to represent Minnie concerning her tax issue within the IRS and in the courts.
(Essay)
4.8/5 (74)
(74) Loren Ltd., a calendar year taxpayer, had the following transactions, all of which were properly reported on a timely filed return. Presuming the absence of fraud, how much of an omission from gross income must occur for Loren before the six-year statute of limitations applies? Show your computations.
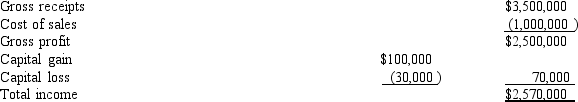
(Essay)
4.7/5 (81)
(81) CPA Norma and her client Colin hold a privilege of confidentiality from the IRS, as to their tax planning discussions about completing Colin's tax returns. The IRS cannot successfully subpoena records concerning these discussions.
(True/False)
4.7/5 (71)
(71) The IRS national office is organized into operating divisions, broadly on the basis of the tax returns that are each division's responsibilities. List at least four the IRS's operating divisions.
(Essay)
4.8/5 (93)
(93) According to the IRS, the annual "Tax Gap" totals about $ billion.
(Short Answer)
4.9/5 (84)
(84) Match each of the following tax penalties with the type of tax penalty as specified by the Code. A letter can be used more than once. The correct solution may include more than one letter.
a. Taxpayer penalty
b. Tax preparer penalty
c. Appraiser's penalty
-Willful and reckless conduct.
(Short Answer)
4.9/5 (74)
(74) A negligence penalty is assessed when the taxpayer is found to have not made a reasonable attempt to comply with the tax law.
(True/False)
4.8/5 (81)
(81) The IRS pays interest on a refund to the taxpayer, unless the IRS's payment is made within
days of the date that a return is filed.
(Short Answer)
4.9/5 (75)
(75) A penalty can be assessed from an appraiser who knew that his/her improper appraisal would be used as part of a tax computation, in the amount of the lesser of % of the tax understatement or
____________________ % of the appraisal fee collected.
(Short Answer)
4.8/5 (73)
(73) The Treasury issues "private letter rulings" and other determinations, usually in response to a taxpayer request. What is the purpose of the rulings program? Answer from both the taxpayer and the government points of view.
(Essay)
4.8/5 (83)
(83) A(n) $ penalty applies if the tax preparer does not sign the client's tax return.
(Short Answer)
4.8/5 (75)
(75) Linwell underpaid his taxes by $250,000. Portions of the underpayment were attributable to negligence ($210,000) and to civil fraud ($40,000). Compute the total penalties incurred.
(Essay)
4.9/5 (82)
(82) Silvio, a cash basis, calendar year taxpayer, filed his income tax return 75 days after the due date. Silvio never extended his return, and with the return he paid the full amount of taxes that were due. What penalties will Silvio incur, and how much is the penalty if his additional tax is $5,000? Disregard any additional interest he must pay.
(Essay)
4.8/5 (88)
(88) Maria's AGI last year was $95,000. To avoid a penalty, her estimated tax payments and withholdings for this year must equal the lesser of ____________________ percent of last year's taxes or ____________________ percent of this year's taxes.
(Short Answer)
4.8/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)