



 Chat with AI
Exam 17: Tax Practice and Ethics

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Maria and Miguel Blanco are in the midst of negotiating a divorce. Because both parties are unwilling to share any current financial information, their joint Form 1040 for 2014 is not filed until October 31, 2015, when the respective divorce attorneys forced them to cooperate. The Blancos should not be subject to any Federal late-filing penalties, because the reasonable cause exception applies to their family discord.
(True/False)
4.9/5  (80)
(80) Faye, a CPA, is preparing Judith's tax return. Last year, Judith's return included dividend income from the P&G Company. This year, Judith reports no such income. Faye should inquire as to whether Judith sold the P&G stock during the year.
(True/False)
4.9/5 (79)
(79) The tax professional can reduce the chances that staff personnel will incur IRS preparer penalties by adopting a "tone at the top" that stresses integrity, diligence, and other elements of an ethical tax practice.
(True/False)
4.7/5 (86)
(86) Maria did not pay her Federal income tax on time. When she eventually filed the return, she reported a balance due. Compute Maria's failure to file penalty in each of the following cases. Disregard any failure to pay penalty.
a. Three months late, $500 additional tax due.
b. Four months late, $2,000 additional tax due.
c. Ten months late, $10,000 additional tax due.
d. Four months late due to fraud by Maria, $10,000 additional tax due.
e. Fifteen months late due to fraud by Maria, $10,000 additional tax due.
(Essay)
4.9/5 (82)
(82) Jaime's negligence penalty will be waived, under the reasonable cause exception. He told the court, "My taxes were wrong because I couldn't understand the tax law."
(True/False)
4.8/5 (89)
(89) Which of the following statements does not reflect the rules governing the accuracy-related penalty for negligence?
(Multiple Choice)
4.7/5 (86)
(86) An individual is not subject to an underpayment penalty until more than $ is due and unpaid through estimated taxes.
(Short Answer)
4.9/5 (85)
(85) Jake, an individual calendar year taxpayer, incurred the following transactions. 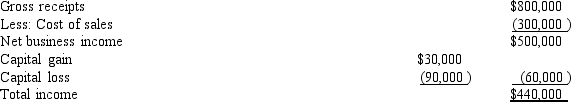 Assuming that any error in timely reporting these amounts was inadvertent, how much omission from gross income would be required before the six-year statute of limitations would apply?
 (Multiple Choice)
4.9/5 (68)
(68) The AICPA's Statements on Standards for Tax Services provide principlesbased guidelines as to how a tax professional should conduct business.
(True/False)
4.8/5 (87)
(87) For each of the indicated tax penalties, indicate the appropriate taxpayer defense. A letter may be used more than once. Not all of the letters might be used.
a. Ignorance of the tax law
b. Reasonable basis
c. Reasonable cause
d. Complexity of the tax law
e. Substantial authority
f. Disclosure on return
-Negligence in filing a return.
(Short Answer)
4.8/5 (82)
(82) For each of the indicated tax penalties, indicate the appropriate taxpayer defense. A letter may be used more than once. Not all of the letters might be used.
a. Ignorance of the tax law
b. Reasonable basis
c. Reasonable cause
d. Complexity of the tax law
e. Substantial authority
f. Disclosure on return
-Failure to deposit withholding tax.
(Short Answer)
4.9/5 (81)
(81) An IRS letter ruling might determine that an employee's compensation is unreasonable in amount.
(True/False)
4.8/5 (73)
(73) In taking a dispute to the Appeals Division, a written protest is required of the taxpayer when the proposed deficiency exceeds $____________________.
(Short Answer)
4.9/5 (75)
(75) In connection with the taxpayer penalty for substantial understatement of tax liability, what defenses (if any) are available?
(Essay)
4.8/5 (81)
(81) Match each of the following tax penalties with the type of tax penalty as specified by the Code. A letter can be used more than once. The correct solution may include more than one letter.
a. Taxpayer penalty
b. Tax preparer penalty
c. Appraiser's penalty
-Fraudulent failure to file a tax return.
(Short Answer)
4.9/5 (87)
(87) Lola, a calendar year taxpayer subject to a 40% marginal Federal gift tax rate, made a gift of a sculpture to Redd, valuing the property at $70,000. The IRS later valued the gift at $100,000. The applicable undervaluation penalty is:
(Multiple Choice)
4.8/5 (90)
(90) Michelle, a calendar year taxpayer subject to a 25% marginal Federal income tax rate, claimed a Form 1040 charitable contribution deduction of $275,000 for a sculpture that the IRS later valued at $200,000. The applicable overvaluation penalty is:
(Multiple Choice)
4.9/5 (81)
(81) The IRS can pay an informant's fee of up to % of the recovered tax, interest, and penalty amounts. The reward can be as high as % for information provided by a "whistle blower."
(Short Answer)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)