



 Chat with AI
Exam 17: Tax Practice and Ethics

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Which of the following statements correctly reflects the rules governing interest to be paid on an individual's Federal tax deficiency or claim for refund?
(Multiple Choice)
4.8/5  (87)
(87) The taxpayer or a tax advisor may be subject to penalties if there is a misstatement of the valuation of an item reported on the tax return. Describe how these penalties work.
(Essay)
4.9/5 (86)
(86) The IRS pays interest on a refund to the taxpayer, unless the IRS's payment is made within ____________________ days of the date that a return is filed.
(Short Answer)
4.9/5 (87)
(87) If the auditor comes to the taxpayer's office to review a tax return, the review is called a(n) ____________________ audit.
(Short Answer)
4.8/5 (81)
(81) Isaiah filed his Federal income tax return on time, but he did not remit the full balance due. Compute Isaiah's failure to pay penalty in each of the following cases. The IRS has not yet issued a deficiency notice.
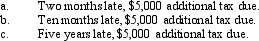
(Essay)
4.8/5 (91)
(91) An "office audit" takes place at the headquarters office of the corporate taxpayer.
(True/False)
4.9/5 (82)
(82) When the IRS issues a notice of tax due, the taxpayer has 30 days to either pay the tax or file a petition with the Tax Court. This is conveyed in the "thirty-day letter."
(True/False)
4.9/5 (76)
(76) Compute the failure to pay and failure to file penalties for John, who filed his 2010 income tax return on December 14, 2011, paying the $10,000 amount due. On April 1, 2011, John submitted a six-month extension of time in which to file his return; he paid no tax with the extension request. He has no reasonable cause for failing to file his return by October 15 or for failing to pay the tax that was due on April 15, 2011. John's failure to comply with the tax laws was not fraudulent.
(Essay)
4.9/5 (73)
(73) A tax preparer is in violation of Circular 230 if he or she:
(Multiple Choice)
4.8/5 (74)
(74) CPA Jennifer has heard about the AICPA's Statements on Standards for Tax Services. Although Jennifer is a licensed CPA in her state, she is not a member of the AICPA. How do the Statements affect Jennifer's tax practice?
(Essay)
4.8/5 (74)
(74) Gloria, a calendar year taxpayer subject to a 35% marginal income tax rate, claimed a Form 1040 charitable contribution deduction of $800,000 for a sculpture that the IRS later valued at $100,000. The applicable overvaluation penalty is:
(Multiple Choice)
4.9/5 (89)
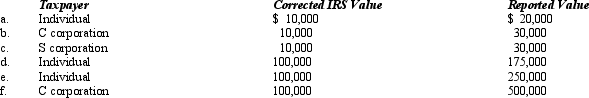
(89) Compute the overvaluation penalty for each of the following independent cases involving the taxpayer's reporting of the fair market value of charitable contribution property. In each case, assume a marginal income tax rate of 35%.
(Essay)
4.8/5 (71)
(71) When a tax issue is taken to court, the burden of proof is on the taxpayer to show that the items reported on the return are correct.
(True/False)
4.9/5 (79)
(79) Ming (a calendar year taxpayer) donates a painting to a local art museum (a qualified charity). The painting cost Ming $2,000 ten years ago and, according to one of Ming's friends (an amateur artist), is worth $40,000. On his income tax return, Ming deducts $40,000 as a Form 1040 charitable contribution. Upon later audit by the IRS, it is determined that the true value of the painting was $30,000. Assuming that Ming is subject to a 30% marginal Federal income tax rate, his penalty for overvaluation is:
(Multiple Choice)
4.8/5 (85)
(85) In the context of civil tax fraud, the burden of proof is on the IRS to show by a "preponderance of the evidence" that the taxpayer had a specific intent to evade a tax.
(True/False)
4.8/5 (76)
(76) A CPA, an attorney, and a(n) ____________________ can represent taxpayers before the IRS.
(Short Answer)
4.8/5 (71)
(71) The rules of Circular 230 need not be followed by which of the following paid tax preparers?
(Multiple Choice)
4.9/5 (72)
(72) One of the four operating divisions of the IRS deals exclusively with manufacturing and exporting businesses.
(True/False)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)