



 Chat with AI
Exam 6: Corporations: Redemptions and Liquidations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


What are the tax consequences of a qualifying stock redemption to the distributing corporation?
(Essay)
4.7/5  (71)
(71) Swan Corporation incurred $10,000 of accounting fees and $15,000 of legal fees in connection with the redemption of stock from its shareholders. None of the expenditures are deductible by Swan.
(True/False)
4.8/5 (85)
(85) Explain the stock attribution rules that apply in the case of stock redemptions.
(Essay)
4.7/5 (89)
(89) A partial liquidation cannot result in sale or exchange treatment to a shareholder if it results in a pro rata stock redemption.
(True/False)
4.7/5 (81)
(81) After a plan of complete liquidation has been adopted, Condor Corporation sells its only asset, land (basis of $220,000), to Eduardo (an unrelated party) for $300,000. Under the terms of the sale, Condor Corporation receives cash of $50,000 and Eduardo's notes for the balance of $250,000. The notes are payable over the next five years ($50,000 per year) and carry an appropriate interest rate. Immediately after the sale, Condor Corporation distributes the cash and notes to Maria, the sole shareholder of Condor Corporation. Maria has a basis of $30,000 in the Condor stock. The installment notes have a value equal to their face amount. If Maria wishes to defer as much gain as possible on the transaction, which of the following is correct?
(Multiple Choice)
4.9/5 (85)
(85) A parent corporation must make the § 338 election by the fifteenth day of the third month following the close of the tax year in which a qualified stock purchase occurs.
(True/False)
5.0/5 (75)
(75) In the current year, Loon Corporation made a distribution in redemption of some of its shares. Loon incurred expenditures in connection with the redemption totaling $35,000 (accounting fees of $9,000, legal fees of $20,000, and brokerage fees of $6,000). The distribution was a qualifying stock redemption. How much of the $35,000 is deductible in the current year?
(Multiple Choice)
4.8/5 (82)
(82) On April 16, 2010, Blue Corporation purchased 15% of the Gold Corporation stock outstanding. Blue Corporation purchased an additional 50% of the stock in Gold on November 23, 2010, and an additional 20% on May 4, 2011. On September 23, 2011, Blue Corporation purchased the remaining 15% of Gold Corporation stock outstanding.
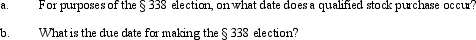
(Essay)
4.7/5 (86)
(86) Five years ago, Eleanor transferred property she had used in her sole proprietorship to Blue Corporation for 1,000 shares of Blue Corporation in a transaction that qualified under § 351. The assets had a tax basis to her of $100,000 and a fair market value of $270,000 on the date of the transfer. In the current year, Blue Corporation ( E & P $800,000) redeems 250 shares from Eleanor for $220,000 in a transaction that qualifies for sale or exchange treatment. With respect to the redemption, Eleanor will have a:
(Multiple Choice)
4.8/5 (82)
(82) Legal dissolution under state law is not required for a liquidation to be complete for tax purposes.
(True/False)
4.9/5 (76)
(76) The stock of Tan Corporation (E & P of $1.3 million) is owned as follows: 90% by Egret Corporation (basis of $520,000), and 10% by Zoe (basis of $55,000). Both shareholders acquired their shares in Tan more than six years ago. In the current year, Tan Corporation liquidates and distributes land (fair market value of $1.1 million, basis of $750,000) and equipment (fair market value of $700,000, basis of $410,000) to Egret Corporation, and securities (fair market value of $200,000, basis of $150,000) to Zoe. What are the tax consequences of these distributions to Egret, to Tan, and to Zoe?
(Essay)
4.8/5 (69)
(69) Mary and Jane, unrelated taxpayers, own Gray Corporation's stock equally. One year before the complete liquidation of Gray, Mary transfers land (basis of $420,000, fair market value of $350,000) to Gray Corporation as a contribution to capital. Assume that Mary also contributed other property in the same transaction having a basis of $20,000 and fair market value of $95,000. In liquidation, Gray distributes the land to Jane. At the time of the liquidation, the land is worth $290,000.
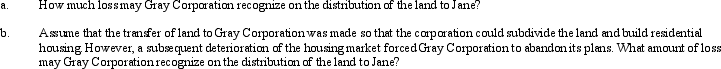
(Essay)
4.9/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)