



 Chat with AI
Exam 11: Perfect Competition

Exam 1: Getting Started337 Questions
Exam 2: The Us and Global Economies201 Questions
Exam 3: The Economic Problem273 Questions
Exam 4: Demand and Supply322 Questions
Exam 5: Elasticities of Demand and Supply335 Questions
Exam 6: Efficiency and Fairness of Markets352 Questions
Exam 7: Government Actions in Markets349 Questions
Exam 8: Global Markets in Action276 Questions
Exam 9: Externalities: Pollution, Education, and Health Care290 Questions
Exam 10: Production and Cost266 Questions
Exam 11: Perfect Competition275 Questions
Exam 12: Monopoly377 Questions
Exam 13: Monopolistic Competition and Oligopoly316 Questions
Exam 14: Gdp: a Measure of Total Production and Income253 Questions
Exam 15: Jobs and Unemployment283 Questions
Exam 16: The Cpi and the Cost of Living263 Questions
Exam 17: Potential Gdp and Economic Growth328 Questions
Exam 18: Money and the Monetary System360 Questions
Exam 19: Aggregate Supply and Aggregate Demand301 Questions
Exam 20: Fiscal Policy and Monetary Policy223 Questions
Select questions type


Quantity (dozens of roses a week) Price (dollars per dozen roses) 1 12 2 12 3 12 4 12
-Pete is a perfectly competitive rose grower. The above table gives quantities and the price for which Pete can sell his roses.
a. What is Pete's total revenue if he sells 1 dozen roses?
2 dozen roses?
3 dozen roses?
4 dozen roses?
b. What is the marginal revenue of the 2nd dozen roses sold?
Of the 3rd dozen?
Of the 4th dozen?
(Essay)
4.9/5  (86)
(86)  The figure above shows some of a firm's cost curves and its marginal revenue curve.
-Based on the figure above, if the firm produces 10 cans per day, the firm ________ maximizing its profit and is ________.
The figure above shows some of a firm's cost curves and its marginal revenue curve.
-Based on the figure above, if the firm produces 10 cans per day, the firm ________ maximizing its profit and is ________. (Multiple Choice)
4.8/5 (83)
(83) A market is initially in a long-run equilibrium and there is a permanent increase in demand. After the new long-run equilibrium is reached, there
(Multiple Choice)
4.8/5 (78)
(78) For a perfectly competitive corn grower in Nebraska, the marginal revenue curve is
(Multiple Choice)
4.8/5 (84)
(84) As a perfectly competitive firm's output increases, its total revenue ________ and its total cost ________.
(Multiple Choice)
4.9/5 (83)
(83) For a perfectly competitive syrup producer whose average total cost curve does not change, an economic profit could turn into an economic loss if the
(Multiple Choice)
4.9/5 (89)
(89)  The figure above shows the cost curves and marginal revenue curve for a perfectly competitive firm.
-The firm in the figure above is ________ that is equal to ________.
The figure above shows the cost curves and marginal revenue curve for a perfectly competitive firm.
-The firm in the figure above is ________ that is equal to ________. (Multiple Choice)
4.7/5 (90)
(90)  -The above figure illustrates a perfectly competitive firm. Curve A represents the
 (Multiple Choice)
4.8/5 (81)
(81) Pumpkin growing is a perfectly competitive industry. Suppose that pumpkin growers are all incurring an economic loss. What happens as time passes?
What is the long-run equilibrium outcome?
(Essay)
4.9/5 (69)
(69) The U-pick berry market is perfectly competitive. Suppose that all U-pick blueberry farms have the same cost curves and all are making an economic profit. What happens as time passes?
What is the long-run equilibrium outcome?
(Essay)
4.8/5 (75)
(75) Quantity (bushels of rutabagas) Total revenue (dollars) Total cost (dollars) 0 0 12 1 10 22 2 20 28 3 30 30 4 40 31 5 50 34 6 60 45 7 70 59 8 80 80
-The above table has the total revenue and total cost schedule for Omar, a perfectly competitive grower of rutabagas. When Omar maximizes his profit, Omar's profit equals
(Multiple Choice)
4.8/5 (78)
(78) If the market price is lower than a perfectly competitive firm's average total cost, the firm will
(Multiple Choice)
4.8/5 (67)
(67) To eliminate losses in a perfectly competitive market, firms exit the industry. This exit results in
(Multiple Choice)
4.8/5 (80)
(80) Suppose a perfectly competitive market is in long-run equilibrium and then there is a permanent increase in the demand for that product. The new long-run equilibrium will have
(Multiple Choice)
4.8/5 (91)
(91) The characteristics that describe a perfectly competitive industry include
(Multiple Choice)
4.8/5 (89)
(89) What is the shape of the demand curve faced by the perfectly competitive firm, and why?
(Essay)
4.8/5 (77)
(77) 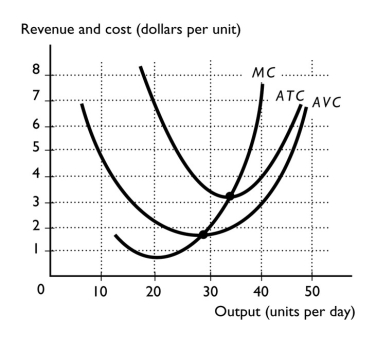 -The above figure shows the cost curves of a profit-maximizing perfectly competitive firm. If the price equals $7,
a. how much will the firm produce?
b. how much is the firm's average total, average variable, and marginal costs?
c. how much is the firm's total, total variable, and total fixed costs?
d. how much is the firm's total revenue and economic profit?
e. what will happen in this market in the long run?
-The above figure shows the cost curves of a profit-maximizing perfectly competitive firm. If the price equals $7,
a. how much will the firm produce?
b. how much is the firm's average total, average variable, and marginal costs?
c. how much is the firm's total, total variable, and total fixed costs?
d. how much is the firm's total revenue and economic profit?
e. what will happen in this market in the long run? (Essay)
4.8/5 (91)
(91) ________ a large number of firms competing by making similar but slightly different products.
(Multiple Choice)
5.0/5 (84)
(84) Suppose the price of a can was $5.10. In this case, to maximize its profit the firm illustrated in the figure above would
(Multiple Choice)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)