



 Chat with AI
Exam 11: Perfect Competition

Exam 1: Getting Started337 Questions
Exam 2: The Us and Global Economies201 Questions
Exam 3: The Economic Problem273 Questions
Exam 4: Demand and Supply322 Questions
Exam 5: Elasticities of Demand and Supply335 Questions
Exam 6: Efficiency and Fairness of Markets352 Questions
Exam 7: Government Actions in Markets349 Questions
Exam 8: Global Markets in Action276 Questions
Exam 9: Externalities: Pollution, Education, and Health Care290 Questions
Exam 10: Production and Cost266 Questions
Exam 11: Perfect Competition275 Questions
Exam 12: Monopoly377 Questions
Exam 13: Monopolistic Competition and Oligopoly316 Questions
Exam 14: Gdp: a Measure of Total Production and Income253 Questions
Exam 15: Jobs and Unemployment283 Questions
Exam 16: The Cpi and the Cost of Living263 Questions
Exam 17: Potential Gdp and Economic Growth328 Questions
Exam 18: Money and the Monetary System360 Questions
Exam 19: Aggregate Supply and Aggregate Demand301 Questions
Exam 20: Fiscal Policy and Monetary Policy223 Questions
Select questions type


Suppose a perfectly competitive firm's minimum average variable cost is $3 when it produces 50. If the price is $2 and the firm's marginal cost is $2, the firm should
(Multiple Choice)
4.8/5  (82)
(82) Firms exit a competitive market when they incur an economic loss. In the long run, this exit means that the economic losses of the surviving firms
(Multiple Choice)
4.8/5 (67)
(67) Consider a short-run equilibrium in a perfectly competitive market. Suppose that the firms' average total cost and marginal cost schedules differ. In the short run,
(Multiple Choice)
4.9/5 (86)
(86) If concerns about mad-cow disease impose economic losses on the perfectly competitive cattle ranchers, exit by the ranchers combined with no further changes in the demand for beef will force the price of beef to
(Multiple Choice)
4.8/5 (74)
(74) Which of the following will increase a perfectly competitive seller's short-run supply and shift the firm's short-run supply curve rightward?
(Multiple Choice)
4.9/5 (72)
(72)  -The above figure shows a perfectly competitive firm. If the market price is $5 per unit, the firm
 (Multiple Choice)
4.9/5 (73)
(73) Suppose that a perfectly competitive firm's marginal revenue equals $12 when it sells 10 units of output. If the marginal cost of producing the 10th unit is $14, to maximize its profit the firm should
(Multiple Choice)
4.8/5 (71)
(71)  -The above figure shows a perfectly competitive firm. If the market price is $5, the firm
 (Multiple Choice)
4.8/5 (73)
(73) As a result of firms leaving the perfectly competitive frozen yogurt market in the early 2000s, the market
(Multiple Choice)
4.9/5 (88)
(88) Shama is producing candles in a perfectly competitive market. When she produces 500 candles, her total cost is $250. If she produces one additional candle, her total cost increases to $260. In order to maximize her profit, she should produce the additional candle
(Multiple Choice)
5.0/5 (67)
(67) For the perfectly competitive broccoli producers in California, the market demand curve for broccoli is
(Multiple Choice)
4.9/5 (84)
(84) 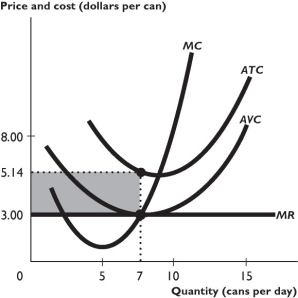 The above figure shows some a firm's cost curves and its marginal revenue curve.
-Based on the figure above, what is the price of a can?
The above figure shows some a firm's cost curves and its marginal revenue curve.
-Based on the figure above, what is the price of a can? (Multiple Choice)
4.9/5 (79)
(79) How does the demand for any one seller's product in perfect competition compare to the market demand for that product?
(Multiple Choice)
4.8/5 (80)
(80) Quantity (bushels of rutabagas) Total revenue (dollars) Total cost (dollars) 0 0 12 1 10 22 2 20 28 3 30 30 4 40 31 5 50 34 6 60 45 7 70 59 8 80 80
-The above table has the total revenue and total cost schedule for Omar, a perfectly competitive grower of rutabagas. When Omar produces 2 bushels of rutabagas, his total profit equals
(Multiple Choice)
4.8/5 (91)
(91) Under what conditions would a perfectly competitive cotton farmer who is incurring an economic loss temporarily stay in business?
(Multiple Choice)
4.7/5 (81)
(81) A perfectly competitive firm will shut down when the price is just below the minimum point on the
(Multiple Choice)
4.8/5 (91)
(91) When one firm sells a good or service that has no close substitutes and a barrier blocks the entry of new firms, what type of market is this?
(Multiple Choice)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)