



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models234 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance264 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology, Production, and Costs328 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting274 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets259 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


In the long run, perfectly competitive firms earn zero economic profit.Why do firms enter an industry when they know that in the long-run they will not earn any profit?
(Essay)
4.8/5  (70)
(70) If a firm in a perfectly competitive industry experiences persistent losses, in the long run it should
(Multiple Choice)
4.9/5 (86)
(86) If, for the last unit of a good produced by a perfectly competitive firm, MR > MC, then in producing it, the firm
(Multiple Choice)
4.9/5 (87)
(87) Figure 12-10
 -Refer to Figure 12-10.The firm's short-run supply curve is its
 (Multiple Choice)
4.9/5 (75)
(75) Table 12-1
 Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases.Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.If the market price of each camera case is $8, what is the firm's total revenue?
Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases.Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.If the market price of each camera case is $8, what is the firm's total revenue? (Multiple Choice)
5.0/5 (94)
(94) A perfectly competitive firm produces 3,000 units of a good at a total cost of $36,000.The fixed cost of production is $20,000.The price of each good is $10.Should the firm continue to produce in the short run?
(Multiple Choice)
5.0/5 (83)
(83) In long-run perfectly competitive equilibrium, which of the following is false?
(Multiple Choice)
4.9/5 (85)
(85) For a given quantity, the total profit of a perfectly competitive firm is equal to the vertical distance between the firm's total revenue curve and its total cost curve.
(True/False)
5.0/5 (68)
(68) In August 2008, Ethan Nicholas developed the iShoot application for the Apple iPhone 3G, and within five months had earned $800,000 from this program.By May 2009, Nicholas had dropped the price from $4.99 to $1.99 in an attempt to maintain sales.This example indicates that in a competitive market
(Multiple Choice)
4.8/5 (86)
(86) In a graph that illustrates a perfectly competitive firm, marginal revenue is
(Multiple Choice)
4.8/5 (85)
(85) In the short run, a profit-maximizing firm will shut down if its total revenue is greater than its variable costs.
(True/False)
4.8/5 (80)
(80) Figure 12-2
 -Refer to Figure 12-2.What happens if the firm produces more than Q₄ units?
 (Multiple Choice)
4.7/5 (83)
(83) How are market price, average revenue, and marginal revenue related for a perfectly competitive firm and why?
(Essay)
4.9/5 (78)
(78) A perfectly competitive firm produces 3,000 units of a good at a total cost of $36,000.The price of each good is $10.Calculate the firm's short-run profit or loss.
(Multiple Choice)
4.8/5 (96)
(96) Molly Sharp is producing a documentary about the plight of the six-toed ferrets of Sri Lanka.Molly has spent $125,000 of her own money on this project and the documentary is now complete.Molly just found out that no studio is willing to release her documentary and she must now shop it to cable television networks, where she knows she will not be able to recoup her investment.Which of the following statements regarding Molly Sharp's documentary is true?
(Multiple Choice)
4.9/5 (77)
(77) Figure 12-18
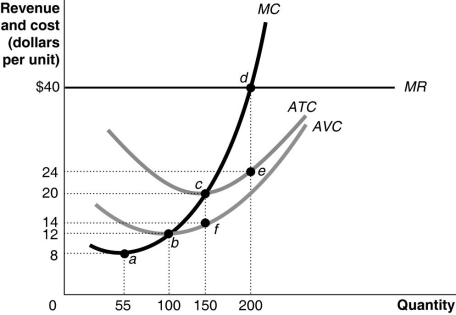 -Use the figure above to answer the following questions.
a.How can you determine that the figure represents a graph of a perfectly competitive firm? Be specific; indicate which curve gives you the information and how you use this information to arrive at your conclusion.
b.What is the market price?
c.What is the profit-maximizing output?
d.What is total revenue at the profit-maximizing output?
e.What is the total cost at the profit-maximizing output?
f.What is the profit or loss at the profit-maximizing output?
g.What is the firm's total fixed cost?
h.What is the total variable cost?
i.Identify the firm's short-run supply curve.
j.Is the industry in a long-run equilibrium?
k.If it is not in long-run equilibrium, what will happen in this industry to restore long-run equilibrium?
l.In long-run equilibrium, what is the firm's profit maximizing quantity?
-Use the figure above to answer the following questions.
a.How can you determine that the figure represents a graph of a perfectly competitive firm? Be specific; indicate which curve gives you the information and how you use this information to arrive at your conclusion.
b.What is the market price?
c.What is the profit-maximizing output?
d.What is total revenue at the profit-maximizing output?
e.What is the total cost at the profit-maximizing output?
f.What is the profit or loss at the profit-maximizing output?
g.What is the firm's total fixed cost?
h.What is the total variable cost?
i.Identify the firm's short-run supply curve.
j.Is the industry in a long-run equilibrium?
k.If it is not in long-run equilibrium, what will happen in this industry to restore long-run equilibrium?
l.In long-run equilibrium, what is the firm's profit maximizing quantity? (Essay)
4.8/5 (84)
(84) Which of the following is not true for a firm in perfect competition?
(Multiple Choice)
4.8/5 (79)
(79) If in a perfectly competitive industry, the market price facing a firm is below its average total cost but above average variable cost at the output where marginal cost equals marginal revenue
(Multiple Choice)
4.7/5 (74)
(74) A constant-cost, perfectly competitive market is in long-run equilibrium.At present, there are 1,000 firms each producing 400 units of output.The price of the good is $60.Now suppose there is a sudden increase in demand for the industry's product which causes the price of the good to rise to $64.In the new long-run equilibrium, how will the average total cost of producing the good compare to what it was before the price of the good rose?
(Multiple Choice)
4.8/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)