



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models234 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance264 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology, Production, and Costs328 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting274 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets259 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


A perfectly competitive firm's horizontal demand curve implies that the firm does not have to lower its price to sell more output.
(True/False)
4.9/5  (87)
(87) If, for the last bushel of apples produced and sold by an apple farm marginal revenue exceeds marginal cost, then in producing that bushel the farm
(Multiple Choice)
4.9/5 (70)
(70) If the market price is $40 in a perfectly competitive market, the marginal revenue from selling the fifth unit is
(Multiple Choice)
4.8/5 (73)
(73) In the mid-1990s, cattle ranchers in the United States kept raising cattle even though prices were at a ten-year low and below average total cost.What is the likely explanation for this?
(Multiple Choice)
4.8/5 (65)
(65) Figure 12-9
 Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9.At price P₁, the firm would produce
Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9.At price P₁, the firm would produce (Multiple Choice)
4.7/5 (91)
(91) Figure 12-1
 -Refer to Figure 12-1.If the firm is producing 700 units
 (Multiple Choice)
4.8/5 (78)
(78) Suppose Veronica sells teapots in the perfectly competitive teapot market.Her output per day and her costs are as follows:
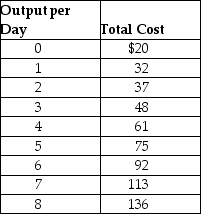 Suppose the current equilibrium price in the teapot market is $20.To maximize profit, how many teapots will Veronica produce, what price will she charge, and how much profit (or loss)will she make? Draw a graph to illustrate your answer.Your graph should include Veronica's demand, ATC, AVC, MC, and MR curves, the price she is charging, the quantity she is producing, and the area representing her profit (or loss).
 (Essay)
4.8/5 (66)
(66) Figure 12-2
 -Refer to Figure 12-2.The firm breaks even at an output level of
 (Multiple Choice)
4.7/5 (87)
(87) For a perfectly competitive firm, which of the following is not true at profit maximization?
(Multiple Choice)
4.9/5 (72)
(72) The supply curve of a perfectly competitive firm in the short run is
(Multiple Choice)
4.8/5 (85)
(85) A perfectly competitive wheat farmer in a constant-cost industry produces 1,000 bushels of wheat at a total cost of $50,000.The prevailing market price is $48.What will happen to the market price of wheat in the long run?
(Multiple Choice)
4.7/5 (69)
(69) Table 12-2
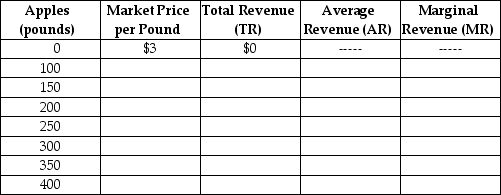 Table 12-2 lists the various pounds (lbs.)of apples that Margie Stattler can sell.Assume that Margie operates in a perfectly competitive market.
-Refer to Table 12-2.How many pounds of apples should Margie sell to maximize her profit?
Table 12-2 lists the various pounds (lbs.)of apples that Margie Stattler can sell.Assume that Margie operates in a perfectly competitive market.
-Refer to Table 12-2.How many pounds of apples should Margie sell to maximize her profit? (Multiple Choice)
4.9/5 (66)
(66) Figure 12-5
 Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.What is the amount of the firm's fixed cost of production?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.What is the amount of the firm's fixed cost of production? (Multiple Choice)
4.8/5 (71)
(71) If a typical firm in a perfectly competitive industry is earning profits, then
(Multiple Choice)
4.9/5 (75)
(75) The long-run supply curve for a perfectly competitive, constant-cost industry
(Multiple Choice)
4.8/5 (84)
(84) The price of a seller's product in perfect competition is determined by
(Multiple Choice)
4.8/5 (83)
(83) The marginal revenue curve for a perfectly competitive firm
(Multiple Choice)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)