



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models234 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance264 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology, Production, and Costs328 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting274 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets259 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


If firms do not earn economic profits in a competitive equilibrium, why would the firms choose to stay in business?
(Essay)
4.8/5  (81)
(81) Figure 12-2
 -Refer to Figure 12-2.Why is the total revenue curve a ray from the origin?
 (Multiple Choice)
4.8/5 (80)
(80) Which of the following is the best example of a perfectly competitive industry?
(Multiple Choice)
4.8/5 (92)
(92) Figure 12-9
 Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9.At price P₁, the firm would
Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9.At price P₁, the firm would (Multiple Choice)
4.7/5 (82)
(82) Maximizing average profit is equivalent to maximizing total profit.
(True/False)
4.8/5 (78)
(78) Figure 12-11
 -Refer to Figure 12-11.Suppose the prevailing price is $20 and the firm is currently producing 1,350 units.In the long-run equilibrium, the firm represented in the diagram
 (Multiple Choice)
4.9/5 (79)
(79) Figure 12-9
Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9.At price P₂, the firm would produce
Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9.At price P₂, the firm would produce (Multiple Choice)
4.9/5 (78)
(78) A perfectly competitive firm breaks even at a price equal to its minimum average total cost.
(True/False)
4.8/5 (83)
(83) What is a long-run supply curve? What does a long-run supply curve look like on a perfectly competitive market graph?
(Essay)
4.9/5 (66)
(66) If a perfectly competitive firm achieves productive efficiency then
(Multiple Choice)
4.8/5 (76)
(76) Table 12-3
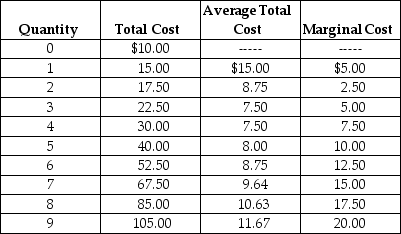 Arnie sells basketballs in a perfectly competitive market.Table 12-3 summarizes Arnie's output per day (Q), total cost (TC), average total cost (ATC)and marginal cost (MC).
-Refer to Table 12-3.What price (P)will Arnie charge and how much profit will he earn if the market price of basketballs is $12.50?
Arnie sells basketballs in a perfectly competitive market.Table 12-3 summarizes Arnie's output per day (Q), total cost (TC), average total cost (ATC)and marginal cost (MC).
-Refer to Table 12-3.What price (P)will Arnie charge and how much profit will he earn if the market price of basketballs is $12.50? (Multiple Choice)
4.9/5 (66)
(66) In a decreasing-cost industry, the entry of new firms lowers average cost at each level of output.
(True/False)
4.9/5 (77)
(77) Suppose there are economies of scale in the production of a specialized memory chip that is used in manufacturing microwaves.This suggests that the microwave industry is a decreasing-cost industry.
(True/False)
4.7/5 (83)
(83) Which of the following offers the best reason why restaurants are not considered to be perfectly competitive firms?
(Multiple Choice)
4.9/5 (86)
(86) In the short run, if price falls below a firm's minimum average total cost, the firm should shut down.
(True/False)
4.7/5 (94)
(94) A perfectly competitive firm will maximize its profit at the rate of output where the vertical distance between its total revenue curve and total cost curve is the largest.This is the same rate of output where
(Multiple Choice)
4.9/5 (92)
(92) Figure 12-1
 -Refer to Figure 12-3.If the firm is producing 500 units
 (Multiple Choice)
4.9/5 (80)
(80) Figure 12-1
-Refer to Figure 12-3.If the firm is charging a price of $12 per unit
-Refer to Figure 12-3.If the firm is charging a price of $12 per unit (Multiple Choice)
4.8/5 (91)
(91) The short-run supply curve for a perfectly competitive firm is that part of the firm's marginal cost curve that lies above the minimum point of its average variable cost curve.
(True/False)
4.9/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)