



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models234 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance264 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology, Production, and Costs328 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting274 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets259 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


A perfectly competitive firm in a constant-cost industry produces 1,000 units of a good at a total cost of $50,000.If the prevailing market price is $48, the number of firms and the industry's output will decrease in the long run.
(True/False)
4.7/5  (89)
(89) Jason, a high-school student, mows lawns for families in his neighborhood.The going rate is $12 for each lawn-mowing service.Jason would like to charge $20 because he believes he has more experience mowing lawns than the many other teenagers who also offer the same service.If the market for lawn mowing services is perfectly competitive, what would happen if Jason raised his price?
(Multiple Choice)
4.9/5 (81)
(81) A perfectly competitive firm has to charge the same price as every other firm in the market.Therefore, the firm
(Multiple Choice)
4.7/5 (84)
(84) Figure 12-5
 Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the firm's fixed cost increases by $1,000 due to a new environmental regulation, what happens in the diagram above?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the firm's fixed cost increases by $1,000 due to a new environmental regulation, what happens in the diagram above? (Multiple Choice)
4.8/5 (84)
(84) What is always true at the quantity where a firm's average total cost equals average revenue?
(Multiple Choice)
4.8/5 (68)
(68) Which of the following does not hold true for a perfectly competitive firm in long-run equilibrium?
(Multiple Choice)
4.8/5 (68)
(68) Figure 12-8
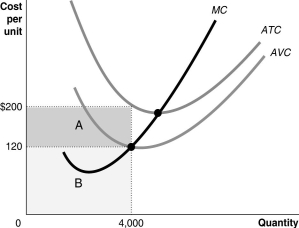 -Refer to Figure 12-8.Suppose the firm produces 4,000 units.What does the shaded area labeled B represent?
 (Multiple Choice)
4.9/5 (77)
(77) Figure 12-17
 The graphs in Figure 12-17 represent the perfectly competitive market demand and supply curves for the apple industry and demand and cost curves for a typical firm in the industry.
-Refer to Figure 12-17.The graphs depicts a short-run equilibrium.How will this differ from the long-run equilibrium? (Assume this is a constant-cost industry.)
The graphs in Figure 12-17 represent the perfectly competitive market demand and supply curves for the apple industry and demand and cost curves for a typical firm in the industry.
-Refer to Figure 12-17.The graphs depicts a short-run equilibrium.How will this differ from the long-run equilibrium? (Assume this is a constant-cost industry.) (Multiple Choice)
4.9/5 (81)
(81) Consider the market for wheat which is a perfectly competitive market.Is the market demand curve the same as the demand curve facing an individual producer? If not, explain how and why they are different? Illustrate your answer graphically.
(Essay)
4.8/5 (61)
(61) Figure 12-8
-Refer to Figure 12-8.Suppose the market price is $120.Which of the following is true?
-Refer to Figure 12-8.Suppose the market price is $120.Which of the following is true? (Multiple Choice)
4.8/5 (81)
(81) At the profit-maximizing level of output for a perfectly competitive firm
(Multiple Choice)
4.9/5 (75)
(75) Which of the following describes the difference between the market demand curve for a perfectly competitive industry and the demand curve for a firm in this industry?
(Multiple Choice)
4.9/5 (82)
(82) To maximize profit, a firm will produce the level of output where MR = MC.If a firm actually makes a profit depends on the relationship of price to average total cost.What are the three possible relationships between price and average total cost that determine if a firm will make a profit, experience a loss, or break even?
(Essay)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)