



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models234 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance264 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology, Production, and Costs328 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting274 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets259 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


Assume that price is greater than average variable cost.If a perfectly competitive firm is producing at an output where price is $114 and the marginal cost is $102, then the firm is probably producing more than its profit-maximizing quantity.
(True/False)
5.0/5  (63)
(63) Assume that the tuna fishing industry is perfectly competitive.Which of the following best characterizes the industry if, as demand for tuna increases, fishing boats have to go farther into the ocean to harvest tuna?
(Multiple Choice)
4.9/5 (71)
(71) Letters are used to represent the terms used to answer this question: price (P), quantity of output (Q), total cost (TC)and average total cost (ATC).Which of the following equations is equal to a firm's average profit?
(Multiple Choice)
4.9/5 (76)
(76) Table 12-1
 Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases.Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.If the market price of each camera case is $8 and the firm maximizes profit, what is the amount of the firm's profit or loss?
Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases.Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.If the market price of each camera case is $8 and the firm maximizes profit, what is the amount of the firm's profit or loss? (Multiple Choice)
4.8/5 (76)
(76) In early 2007, Pioneer and JVC, two Japanese electronics firms, each announced that their profits were going to be lower than expected because they both had to cut prices for LCD and plasma television sets.Which of the following could explain why these firms did not simply raise their prices and increase their profits?
(Multiple Choice)
4.9/5 (86)
(86) Table 12-1
Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases.Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.The firm will not produce in the short run if the output price falls below
Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases.Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.The firm will not produce in the short run if the output price falls below (Multiple Choice)
4.7/5 (68)
(68) Figure 12-4
 Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30, the firm's profit-maximizing output level is
Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30, the firm's profit-maximizing output level is (Multiple Choice)
4.7/5 (91)
(91) Some markets have many buyers and sellers but fall into the category of monopolistic competition rather than perfect competition.The most common reason for this is
(Multiple Choice)
4.8/5 (80)
(80) Fill in the columns in the following table and use the values in the table to determine the profit-maximizing level of output.
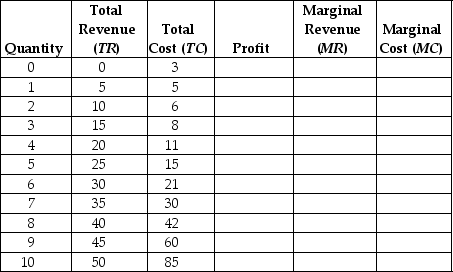
(Essay)
4.8/5 (82)
(82) Allocative efficiency is achieved in an industry when firms supply those goods and services that provide consumers with a marginal benefit equal to the marginal cost of producing those goods and services.
(True/False)
4.8/5 (79)
(79) Figure 12-5
 Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.What is the minimum price the firm requires to produce output?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.What is the minimum price the firm requires to produce output? (Multiple Choice)
4.9/5 (88)
(88) The market demand curve for a perfectly competitive industry is the horizontal summation of each individual firm's demand curve.
(True/False)
4.8/5 (75)
(75) If the market price is $25, the average revenue of selling five units is
(Multiple Choice)
4.8/5 (76)
(76) Ted's Pancake Kitchen suffers a short-run loss.When should Ted decide to shut down rather than continue to produce?
(Multiple Choice)
4.9/5 (85)
(85) What assumptions are necessary for a market to be perfectly competitive? Explain why each of these assumptions is important.
(Essay)
4.9/5 (73)
(73) Figure 12-17
 The graphs in Figure 12-17 represent the perfectly competitive market demand and supply curves for the apple industry and demand and cost curves for a typical firm in the industry.
-Refer to Figure 12-17.Which of the following statements is true?
The graphs in Figure 12-17 represent the perfectly competitive market demand and supply curves for the apple industry and demand and cost curves for a typical firm in the industry.
-Refer to Figure 12-17.Which of the following statements is true? (Multiple Choice)
4.7/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)