



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models234 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance264 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology, Production, and Costs328 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting274 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets259 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


Which of the following is a characteristic of a firm in a perfectly competitive market?
(Multiple Choice)
4.8/5  (80)
(80) If a perfectly competitive firm's price is above its average total cost, the firm
(Multiple Choice)
4.9/5 (75)
(75) The price a perfectly competitive firm receives for its output
(Multiple Choice)
4.9/5 (73)
(73) Figure 12-10
 -Refer to Figure 12-10.The total cost at the profit-maximizing output level equals
 (Multiple Choice)
5.0/5 (95)
(95) Figure 12-5
 Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the market price is $20, what is the amount of the firm's profit?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the market price is $20, what is the amount of the firm's profit? (Multiple Choice)
5.0/5 (83)
(83) Figure 12-14
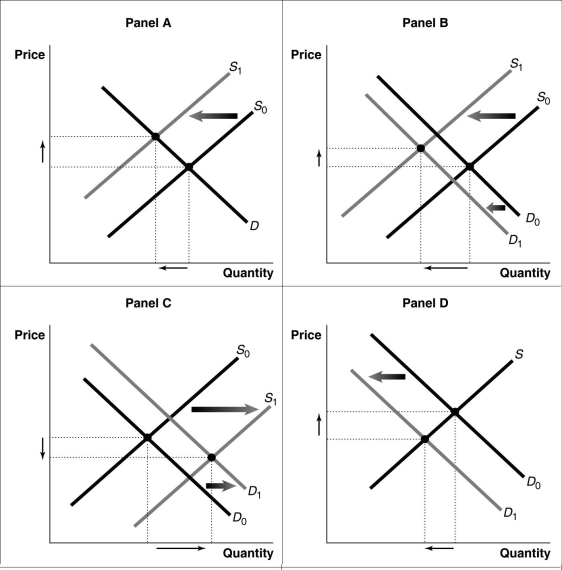 -Refer to Figure 12-14.Consider a typical firm in a perfectly competitive industry which is incurring short-run losses.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.7/5 (82)
(82) The demand curve for an individual seller's product in perfect competition is
(Multiple Choice)
4.9/5 (77)
(77) What is meant by allocative efficiency? How does a perfectly competitive firm achieve allocative efficiency?
(Essay)
4.9/5 (81)
(81) What is meant by productive efficiency? How does a perfectly competitive firm achieve productive efficiency?
(Essay)
4.8/5 (89)
(89) If price = marginal cost at the output produced by a perfectly competitive firm and the firm is earning an economic profit, then
(Multiple Choice)
4.8/5 (82)
(82) A perfectly competitive industry achieves allocative efficiency because
(Multiple Choice)
4.9/5 (88)
(88) A firm's total profit can be calculated as all of the following except
(Multiple Choice)
4.9/5 (75)
(75) A firm could continue to operate for years without ever earning a profit as long as it is producing an output where
(Multiple Choice)
4.9/5 (84)
(84) In analyzing the decision to shut down in the short run we assume that the firm's fixed costs are
(Multiple Choice)
4.9/5 (86)
(86) Why are individual buyers and sellers in perfect competition called price takers?
(Essay)
4.9/5 (73)
(73) The demand curve for each seller's product in perfect competition is horizontal at the market price because
(Multiple Choice)
4.8/5 (80)
(80) Assume the market for cage-free eggs is perfectly competitive.All else equal, as farmers find it less profitable to produce and sell cage-free eggs in this market
(Multiple Choice)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)