



 Chat with AI
Exam 11: Monopoly

Exam 1: What Is Economics232 Questions
Exam 2: The Economy: Myth and Reality155 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice255 Questions
Exam 4: Supply and Demand: an Initial Look313 Questions
Exam 5: Consumer Choice: Individual and Market Demand206 Questions
Exam 6: Demand and Elasticity214 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis221 Questions
Exam 8: Output, Price, and Profit: the Importance of Marginal Analysis194 Questions
Exam 9: Securities: Business Finance and the Economy: the Tail That Wags the Dog203 Questions
Exam 10: The Firm and the Industry Under Perfect Competition212 Questions
Exam 11: Monopoly208 Questions
Exam 12: Between Competition and Monopoly230 Questions
Exam 13: Limiting Market Power: Regulation and Antitrust155 Questions
Exam 14: The Case for Free Markets: the Price System225 Questions
Exam 15: The Shortcomings of Free Markets219 Questions
Exam 16: Externalities, the Environment, and Natural Resources222 Questions
Exam 17: Taxation and Resource Allocation221 Questions
Exam 18: Pricing the Factors of Production233 Questions
Exam 19: Labor and Entrepreneurship: the Human Inputs271 Questions
Exam 20: Poverty, Inequality, and Discrimination172 Questions
Exam 21: Is Useconomic Leadership Threatened75 Questions
Exam 22: An Introduction to Macroeconomics216 Questions
Exam 23: The Goals of Macroeconomic Policy212 Questions
Exam 24: Economic Growth: Theory and Policy228 Questions
Exam 25: Aggregate Demand and the Powerful Consumer219 Questions
Exam 26: Demand-Side Equilibrium: Unemployment or Inflation216 Questions
Exam 27: Bringing in the Supply Side: Unemployment and Inflation228 Questions
Exam 28: Managing Aggregate Demand: Fiscal Policy210 Questions
Exam 29: Money and the Banking System224 Questions
Exam 30: Monetary Policy: Conventional and Unconventional210 Questions
Exam 31: He Financial Crisis and the Great Recession66 Questions
Exam 32: The Debate Over Monetary and Fiscal Policy219 Questions
Exam 33: Budget Deficits in the Short and Long Run215 Questions
Exam 34: The Trade-Off Between Inflation and Unemployment219 Questions
Exam 35: International Trade and Comparative Advantage223 Questions
Exam 36: The International Monetary System: Order or Disorder218 Questions
Exam 37: Exchange Rates and the Macroeconomy219 Questions
Select questions type


Since the Red Cross supplies 95 percent of the blood in the United States, it can be considered a monopolist.Assume that it, in fact, operates like a monopolist.The Red Cross currently charges hospitals and other users $21 for a pint of blood.In order to increase the supply of blood, the government offers the Red Cross a $10 million, lump-sum subsidy.How much more blood supply will the subsidy generate?
(Multiple Choice)
4.9/5  (77)
(77) At his current level of output, a monopolist has an MR of $10, an MC of $6, and an economic profit of zero.If the market demand curve is downward sloping and his marginal cost curve upward sloping, the monopolist
(Multiple Choice)
4.8/5 (86)
(86) A monopolist firm may be more innovative than a competitive firm.
(True/False)
4.9/5 (81)
(81) Monopolies are always large firms with great economies of scale.
(True/False)
4.8/5 (65)
(65) An increase in fixed cost will, in the long run, alter the industry output of
(Multiple Choice)
4.8/5 (74)
(74) Price discrimination allows a monopolist to make higher profits.
(True/False)
4.8/5 (84)
(84) Figure 11-9
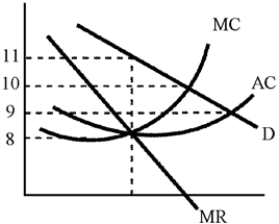 -In Figure 11-9, how much more than the short-run competitive price will the profit-maximizing monopolist charge?
 (Multiple Choice)
4.8/5 (80)
(80) Assume that a firm has measured demand carefully and thinks that the following table accurately displays this.The total cost has been measured and can be given as TC = 20 + Q + Q₂ where Q is the level of output.Complete the table and determine the profit-maximizing level of output.
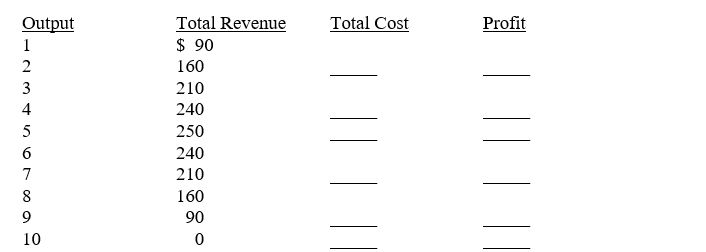
(Essay)
4.9/5 (73)
(73)
 -In Table 11-2, the price at the profit-maximizing output is how much?
 (Multiple Choice)
4.9/5 (84)
(84) Figure 11-5
 -In Figure 11-5, Crown Theater, a monopolist movie theater, will make a profit of ____ at its profit-maximizing price and quantity of theater tickets.
 (Multiple Choice)
4.8/5 (87)
(87) In cases of natural monopoly, it is best to have only one firm producing all of the output in a market.
(True/False)
4.7/5 (89)
(89) ____ mean that the costs involved cannot be recouped for a considerable period of time.
(Multiple Choice)
4.9/5 (76)
(76) Under what conditions might a monopoly be more efficient than a perfectly competitive firm?
(Essay)
4.9/5 (80)
(80) In perfect competition, one result of the model was that there were no economic profits in the long run.In a monopoly, the firm typically earns a positive economic profit.Why is there this difference?
(Essay)
4.7/5 (82)
(82) Bargain airline fares in which airlines charge varying rates to passengers for the same flight and service is an example of
(Multiple Choice)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)