



 Chat with AI
Exam 9: A: Price Takers and the Competitive Process

Exam 1: The Economic Approach210 Questions
Exam 2: A: Some Tools of the Economist224 Questions
Exam 2: B: Some Tools of the Economist33 Questions
Exam 3: A: Supply, Demand, and the Market Process225 Questions
Exam 3: B: Supply, Demand, and the Market Process180 Questions
Exam 4: A: Supply and Demand: Applications and Extensions233 Questions
Exam 4: B: Supply and Demand: Applications and Extensions98 Questions
Exam 5: Difficult Cases for the Market and the Role of Government168 Questions
Exam 6: The Economics of Collective Decision-Making180 Questions
Exam 7: Consumer Choice and Elasticity223 Questions
Exam 8: A: Costs and the Supply of Goods223 Questions
Exam 8: B: Costs and the Supply of Goods8 Questions
Exam 9: A: Price Takers and the Competitive Process237 Questions
Exam 9: B: Price Takers and the Competitive Process23 Questions
Exam 10: Price-Searcher Markets With Low Entry Barriers216 Questions
Exam 11: A: Price-Searcher Markets With High Entry Barriers229 Questions
Exam 11: B: Price-Searcher Markets With High Entry Barriers25 Questions
Exam 12: The Supply of and Demand for Productive Resources200 Questions
Exam 13: Earnings, Productivity, and the Job Market109 Questions
Exam 14: Investment, the Capital Market, and the Wealth of Nations129 Questions
Exam 15: Income Inequality and Poverty136 Questions
Exam 16: Appendix: Government Spending and Taxation79 Questions
Exam 17: Appendix: the Economics of Social Security54 Questions
Exam 18: Appendix: the Stock Market: Its Function, Performance, and Potential As an Investment Opportunity70 Questions
Exam 19: Appendix: Great Debates in Economics: Keynes Versus Hayek8 Questions
Exam 20: Appendix: the Crisis of 2008: Causes and Lessons for the Future64 Questions
Exam 21: Appendix: Lessons From the Great Depression60 Questions
Exam 22: Appendix: the Economics of Healthcare68 Questions
Exam 23: Appendix:education: Problems and Performance60 Questions
Exam 24: Appendix: Earnings Differences Between Men and Women47 Questions
Exam 26: Appendix: the Question of Resource Exhaustion61 Questions
Exam 25: Appendix: Do Labor Unions Increase the Wages of Workers74 Questions
Exam 27: Appendix: Difficult Environmental Cases and the Role of Government63 Questions
Select questions type


The textile industry is composed of a large number of small firms. In recent years, these firms have suffered economic losses, and many sellers have left the industry. Economic theory suggests that if technology, imports, and other factors remain constant, these conditions will
(Multiple Choice)
4.8/5  (64)
(64) If marginal revenue exceeds marginal cost at the current level of output, profit will increase when output is expanded because
(Multiple Choice)
4.7/5 (83)
(83) If profit-seeking entrepreneurs are going to be successful, they must
(Multiple Choice)
4.9/5 (83)
(83) If a restaurant in a summer tourist area is highly profitable during the summer months but unable to cover even its variable costs during the winter months, the restaurant should
(Multiple Choice)
5.0/5 (73)
(73) Which of the following best describes the series of events shown in the figure? The original conditions prior to the change are shown by D₀ and S₀ (point A), and SLR is the market long-run supply curve. 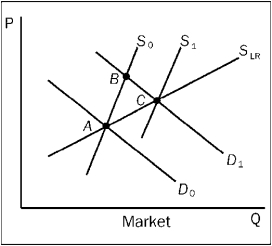
(Multiple Choice)
4.8/5 (76)
(76) In the short run, a firm that is a price taker will stay in business as long as
(Multiple Choice)
4.7/5 (81)
(81) Figure 9-6
 -When the market price in Figure 9-6 is $20, the firm's maximum profit will be approximately
 (Multiple Choice)
4.9/5 (75)
(75) If firms in a price-taker industry were forced to install antipollution devices that increased their production costs, we should expect
(Multiple Choice)
4.8/5 (81)
(81) Scenario 9-1
Assume a certain competitive price-taker firm is producing Q = 1,000 units of output. At Q = 1,000, the firm's marginal cost equals $15 and its average total cost equals $11. The firm sells its output for $12 per unit.
-Refer to Scenario 9-1. At Q = 1,000, the firm's profit amounts to
(Multiple Choice)
4.8/5 (86)
(86) If factor prices rise as demand increases and the firms expand output, the long-run market supply curve will be upward sloping. In terms of economics, this describes
(Multiple Choice)
4.7/5 (75)
(75) If a price taker in a competitive market is going to maximize profits, he must
(Multiple Choice)
4.9/5 (78)
(78) Which of the following is a residual reward that accrues to business decision makers who use resources so as to increase their value?
(Multiple Choice)
4.9/5 (74)
(74) If the ice cream industry is a competitive price-taker market and all ice cream producers are earning zero economic profit, what will be the impact of an increase in the demand for ice cream?
(Multiple Choice)
4.8/5 (90)
(90) When a firm in a price-taker industry is in long-run equilibrium, the market price equals
(Multiple Choice)
4.8/5 (77)
(77) When firms have an incentive to exit a competitive price-taker market, their exit will
(Multiple Choice)
4.7/5 (83)
(83) Figure 9-17
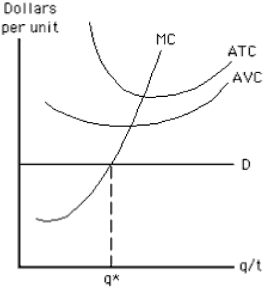 -Which of the following statements about the competitive price-taker firm represented in Figure 9-17 is false?
 (Multiple Choice)
4.8/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)