



 Chat with AI
Exam 9: A: Price Takers and the Competitive Process

Exam 1: The Economic Approach210 Questions
Exam 2: A: Some Tools of the Economist224 Questions
Exam 2: B: Some Tools of the Economist33 Questions
Exam 3: A: Supply, Demand, and the Market Process225 Questions
Exam 3: B: Supply, Demand, and the Market Process180 Questions
Exam 4: A: Supply and Demand: Applications and Extensions233 Questions
Exam 4: B: Supply and Demand: Applications and Extensions98 Questions
Exam 5: Difficult Cases for the Market and the Role of Government168 Questions
Exam 6: The Economics of Collective Decision-Making180 Questions
Exam 7: Consumer Choice and Elasticity223 Questions
Exam 8: A: Costs and the Supply of Goods223 Questions
Exam 8: B: Costs and the Supply of Goods8 Questions
Exam 9: A: Price Takers and the Competitive Process237 Questions
Exam 9: B: Price Takers and the Competitive Process23 Questions
Exam 10: Price-Searcher Markets With Low Entry Barriers216 Questions
Exam 11: A: Price-Searcher Markets With High Entry Barriers229 Questions
Exam 11: B: Price-Searcher Markets With High Entry Barriers25 Questions
Exam 12: The Supply of and Demand for Productive Resources200 Questions
Exam 13: Earnings, Productivity, and the Job Market109 Questions
Exam 14: Investment, the Capital Market, and the Wealth of Nations129 Questions
Exam 15: Income Inequality and Poverty136 Questions
Exam 16: Appendix: Government Spending and Taxation79 Questions
Exam 17: Appendix: the Economics of Social Security54 Questions
Exam 18: Appendix: the Stock Market: Its Function, Performance, and Potential As an Investment Opportunity70 Questions
Exam 19: Appendix: Great Debates in Economics: Keynes Versus Hayek8 Questions
Exam 20: Appendix: the Crisis of 2008: Causes and Lessons for the Future64 Questions
Exam 21: Appendix: Lessons From the Great Depression60 Questions
Exam 22: Appendix: the Economics of Healthcare68 Questions
Exam 23: Appendix:education: Problems and Performance60 Questions
Exam 24: Appendix: Earnings Differences Between Men and Women47 Questions
Exam 26: Appendix: the Question of Resource Exhaustion61 Questions
Exam 25: Appendix: Do Labor Unions Increase the Wages of Workers74 Questions
Exam 27: Appendix: Difficult Environmental Cases and the Role of Government63 Questions
Select questions type


Refer to Scenario 9-1. At Q = 999, the firm's total cost amounts to
(Multiple Choice)
4.9/5  (64)
(64) Suppose that sharply lower coffee prices lead to a decrease in the demand for tea. Tea price decreases, and the tea producers experience short-run economic losses. If the tea industry is a price-taker market, after sufficient time is allowed for the market to adjust fully to the decrease in the demand for tea, one would expect the tea industry's output to
(Multiple Choice)
4.8/5 (79)
(79) A price-taker firm is currently producing 50 units of output at an average total cost of $3 per unit. If the market price is $7, then the firm's total economic profit is
(Multiple Choice)
4.9/5 (75)
(75) The schedule of total cost for a firm in a price-taker market is given in the table. If the market price for this product is $50, which of the following output levels should this firm produce if it wants to maximize its profit? 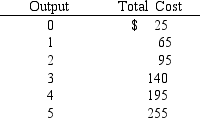
(Multiple Choice)
4.8/5 (75)
(75) If the expansion of output in an industry leads to unchanged resource prices, the industry is most likely to be
(Multiple Choice)
4.7/5 (79)
(79) For a firm in a price-taker market, the firm's demand curve is
(Multiple Choice)
4.9/5 (85)
(85) If resource prices rise and the per-unit cost of producing a product increases as the firms in an industry expand output in response to an increase in demand, the long-run market supply curve for the product will
(Multiple Choice)
4.7/5 (83)
(83) In the short run, a profit-maximizing firm in a price-taker market will definitely stop production if
(Multiple Choice)
4.9/5 (84)
(84) Figure 9-1
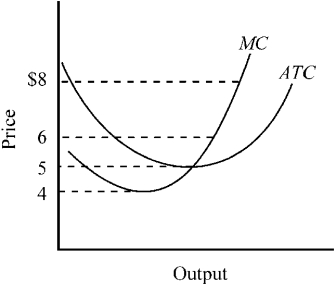 -Figure 9-1 shows the marginal and average total cost curves for a firm producing product A. What would be the minimum price this firm could charge and still continue to supply A to the market in the long run?
 (Multiple Choice)
4.8/5 (77)
(77) "Competitive price-taker markets" and "purely competitive markets" are
(Multiple Choice)
4.8/5 (82)
(82) Figure 9-18
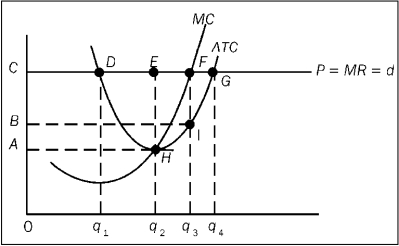 -Refer to Figure 9-18. Given the current market conditions, in the long run,
 (Multiple Choice)
4.9/5 (72)
(72) In price-taker markets, individual firms have no control over price. Therefore, the firm's marginal revenue curve is
(Multiple Choice)
4.9/5 (91)
(91) Figure 9-13
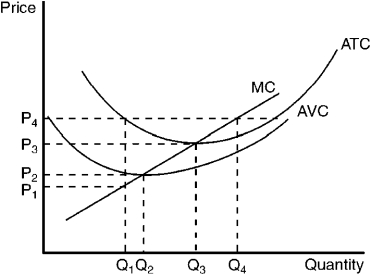 -Refer to Figure 9-13. When price rises from P₂ to P₃, the firm finds that
 (Multiple Choice)
4.8/5 (75)
(75) The long-run supply curve for a product differs from the short-run supply curve in that the long-run supply curve is usually
(Multiple Choice)
4.9/5 (89)
(89) Figure 9-5
 -If the market price in Figure 9-5 fell to $2.50, what should the firm do?
 (Multiple Choice)
4.8/5 (74)
(74) If occupational safety laws were changed so that firms no longer had to take expensive steps to meet regulatory requirements, we would expect
(Multiple Choice)
5.0/5 (78)
(78) Figure 9-9
 -The average total cost (ATC) and marginal costs (MC) of a firm producing in a price-taker industry are depicted in Figure 9-9. If the current market price of the firm's product is $50, what output should this firm produce per day?
 (Multiple Choice)
4.9/5 (84)
(84) If a product is manufactured under conditions of constant cost, an increase in the demand for the product will increase
(Multiple Choice)
4.7/5 (82)
(82) Suppose antitheft auto alarms are produced in a price-taker market that is initially in long-run equilibrium. It is estimated that only 23 percent of all autos have alarms. Due to rising auto theft, Congress mandates alarms in every vehicle. Assume complete compliance. If the industry is an increasing cost industry, price will
(Multiple Choice)
4.9/5 (88)
(88) Suppose the minimum average total cost (ATC) of a firm competing in a competitive price-taker market was $1.00 per unit and that the firm's minimum average variable cost (AVC) was $.80 per unit. If the market price was $.75 per unit, a profit-seeking firm would
(Multiple Choice)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)