



 Chat with AI
Exam 10: The Firm and the Industry Under Perfect Competition

Exam 1: What Is Economics261 Questions
Exam 2: The Economy: Myth and Reality185 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice290 Questions
Exam 4: Supply and Demand: an Initial Look337 Questions
Exam 5: Consumer Choice: Individual and Market Demand243 Questions
Exam 6: Demand and Elasticity254 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis260 Questions
Exam 8: Output, Price, and Profit: the Importance of Marginal Analysis234 Questions
Exam 9: The Financial Markets and the Economy: the Tail That Wags the Dog227 Questions
Exam 10: The Firm and the Industry Under Perfect Competition253 Questions
Exam 11: The Case for Free Markets: the Price System259 Questions
Exam 12: Monopoly244 Questions
Exam 13: Between Competition and Monopoly254 Questions
Exam 14: Limiting Market Power: Antitrust and Regulation155 Questions
Exam 15: The Shortcomings of Free Markets219 Questions
Exam 16: Externalities, Externaliteis, the Environment, and Natural Resources222 Questions
Exam 17: Taxation and Resource Allocation221 Questions
Exam 18: Pricing the Factors of Production233 Questions
Exam 19: Labor and Entrepreneurship: the Human Inputs271 Questions
Exam 20: Poverty, Inequality, and Discrimination171 Questions
Exam 21: International Trade and Comparative Advantage226 Questions
Exam 22: Contemporary Issues in the Us Economy23 Questions
Select questions type


Figure 10-2
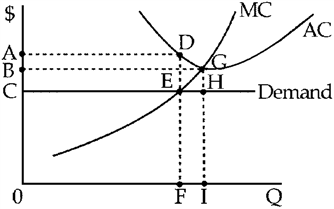 Figure 10-2 shows demand and short-run cost curves for a perfectly competitive firm. At its profit-maximizing level of output, the firm's short-run TC is represented by area
 (Multiple Choice)
4.8/5  (76)
(76) The long run for the industry is defined as a period of time long enough for
(Multiple Choice)
4.8/5 (77)
(77) When new farmers enter the wheat industry, the equilibrium price of wheat
(Multiple Choice)
4.9/5 (77)
(77) For a perfectly competitive firm, the short-run supply curve has an output level that is
(Multiple Choice)
4.8/5 (81)
(81) Perfect competition is characterized by numerous products with well-known brand names.
(True/False)
4.9/5 (81)
(81) The short-run supply curve of the perfectly competitive firm is the firm's
(Multiple Choice)
4.8/5 (80)
(80) Subsidizing firms that pollute will reduce pollution in the long run.
(True/False)
4.8/5 (76)
(76) It pays the firm to produce only if total variable costs exceed total revenue.
(True/False)
4.8/5 (72)
(72) In a long-run equilibrium in a perfectly competitive market, firms are selling at a price equal to average cost.
(True/False)
4.8/5 (81)
(81) The short-run supply curve for the perfectly competitive firm is that part of the marginal cost curve that lies above the average fixed cost curve.
(True/False)
4.7/5 (73)
(73) If the objective of economic policy is to decrease the amount of pollution by an industry in the long run, the
(Multiple Choice)
5.0/5 (73)
(73) Perfect competition forms one extreme of the market structure spectrum.
(True/False)
4.8/5 (79)
(79) Firms entering a perfectly competitive industry will cause the price of the product to
(Multiple Choice)
4.8/5 (91)
(91) Figure 10-1
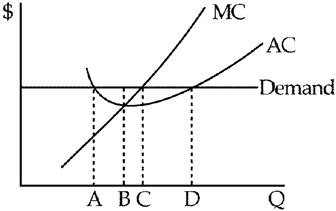 Suppose a perfectly competitive firm's situation is shown in Figure 10-1 and the firm is currently producing at B. What should the firm do in this situation?
 (Multiple Choice)
4.7/5 (89)
(89) Which of the following is a characteristic of perfect competition?
(Multiple Choice)
4.7/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)