



 Chat with AI
Exam 10: The Firm and the Industry Under Perfect Competition

Exam 1: What Is Economics261 Questions
Exam 2: The Economy: Myth and Reality185 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice290 Questions
Exam 4: Supply and Demand: an Initial Look337 Questions
Exam 5: Consumer Choice: Individual and Market Demand243 Questions
Exam 6: Demand and Elasticity254 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis260 Questions
Exam 8: Output, Price, and Profit: the Importance of Marginal Analysis234 Questions
Exam 9: The Financial Markets and the Economy: the Tail That Wags the Dog227 Questions
Exam 10: The Firm and the Industry Under Perfect Competition253 Questions
Exam 11: The Case for Free Markets: the Price System259 Questions
Exam 12: Monopoly244 Questions
Exam 13: Between Competition and Monopoly254 Questions
Exam 14: Limiting Market Power: Antitrust and Regulation155 Questions
Exam 15: The Shortcomings of Free Markets219 Questions
Exam 16: Externalities, Externaliteis, the Environment, and Natural Resources222 Questions
Exam 17: Taxation and Resource Allocation221 Questions
Exam 18: Pricing the Factors of Production233 Questions
Exam 19: Labor and Entrepreneurship: the Human Inputs271 Questions
Exam 20: Poverty, Inequality, and Discrimination171 Questions
Exam 21: International Trade and Comparative Advantage226 Questions
Exam 22: Contemporary Issues in the Us Economy23 Questions
Select questions type


Profits or losses must be temporary for perfectly competitive firms. Why?
(Essay)
4.8/5  (88)
(88) An increase in market demand will cause an increase in industry output in the long run because
(Multiple Choice)
4.8/5 (92)
(92) Richard Bland quit his job as an accounting professor to start his own restaurant. He gave up a salary of $50,000 per year and withdrew $100,000 in bank CDs earning 5 percent to buy a building and equipment. In the restaurant's first year it had direct expenses of $75,000 and revenues of $150,000. The restaurant's economic profit was
(Multiple Choice)
4.9/5 (87)
(87) The process of adjustment to a new long-run equilibrium in a perfectly competitive industry is not complete if
(Multiple Choice)
4.9/5 (87)
(87) Give a complete but concise definition of the following terms.
a. perfect competition
b. perfectly competitive firm's demand curve
c. shutdown point
d. long-run equilibrium in perfect competition
(Essay)
4.8/5 (84)
(84) Which of the following markets most closely resembles the characteristics of a perfectly competitive market?
(Multiple Choice)
4.9/5 (85)
(85) The short-run equilibrium output of a competitive firm is found by equating marginal cost with price.
(True/False)
4.8/5 (76)
(76) In a market with perfectly competitive firms, the market demand curve is usually ____ and the demand curve facing each individual firm ____.
(Multiple Choice)
4.8/5 (75)
(75) The entry of firms into a perfectly competitive industry causes the supply curve to
(Multiple Choice)
4.7/5 (79)
(79) Which of the following is not a characteristic of perfect competition?
(Multiple Choice)
4.8/5 (71)
(71) Perfectly competitive markets feature relatively high barriers to entry.
(True/False)
4.9/5 (77)
(77) A perfectly competitive firm is a "price taker" because it cannot sell its product for more than the market price.
(True/False)
4.9/5 (83)
(83) A perfectly competitive firm should continue to expand output whenever
(Multiple Choice)
4.8/5 (75)
(75) Firms in perfectly competitive markets are confined to making profits in the short run, but never a loss.
(True/False)
4.7/5 (85)
(85) The entry of new firms into a perfectly competitive market shifts the demand curve outward.
(True/False)
4.8/5 (81)
(81) The market for toothpaste is a good example of perfect competition.
(True/False)
4.8/5 (79)
(79) Figure 10-6
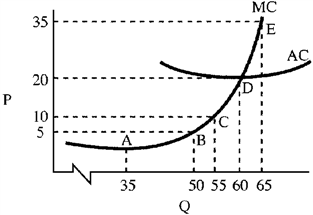 In Figure 10-6, the price at long-run equilibrium is
 (Multiple Choice)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)