



 Chat with AI
Exam 10: The Firm and the Industry Under Perfect Competition

Exam 1: What Is Economics261 Questions
Exam 2: The Economy: Myth and Reality185 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice290 Questions
Exam 4: Supply and Demand: an Initial Look337 Questions
Exam 5: Consumer Choice: Individual and Market Demand243 Questions
Exam 6: Demand and Elasticity254 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis260 Questions
Exam 8: Output, Price, and Profit: the Importance of Marginal Analysis234 Questions
Exam 9: The Financial Markets and the Economy: the Tail That Wags the Dog227 Questions
Exam 10: The Firm and the Industry Under Perfect Competition253 Questions
Exam 11: The Case for Free Markets: the Price System259 Questions
Exam 12: Monopoly244 Questions
Exam 13: Between Competition and Monopoly254 Questions
Exam 14: Limiting Market Power: Antitrust and Regulation155 Questions
Exam 15: The Shortcomings of Free Markets219 Questions
Exam 16: Externalities, Externaliteis, the Environment, and Natural Resources222 Questions
Exam 17: Taxation and Resource Allocation221 Questions
Exam 18: Pricing the Factors of Production233 Questions
Exam 19: Labor and Entrepreneurship: the Human Inputs271 Questions
Exam 20: Poverty, Inequality, and Discrimination171 Questions
Exam 21: International Trade and Comparative Advantage226 Questions
Exam 22: Contemporary Issues in the Us Economy23 Questions
Select questions type


A perfectly competitive firm will not operate where MC = MR but at MC = AC.
(True/False)
5.0/5  (82)
(82) We don't need to draw separate curves for demand, average revenue, and marginal revenue curves for a perfectly competitive firm. Why?
(Essay)
4.8/5 (104)
(104) For a perfectly competitive firm, the long-run supply curve is the long-run average cost curve.
(True/False)
4.9/5 (79)
(79) For a perfectly competitive firm, marginal revenue equals average revenue because the
(Multiple Choice)
4.9/5 (83)
(83) Perfectly competitive markets are not the best at producing the goods that are desired by consumers.
(True/False)
4.8/5 (79)
(79) Why does the supply curve of the perfectly competitive industry shift to the right whenever a new firm enters the industry?
(Essay)
4.8/5 (70)
(70) In a long-run equilibrium in a perfectly competitive market, the average firm earns positive economic profits.
(True/False)
4.7/5 (89)
(89) The number of firms in a perfectly competitive industry is not fixed in the long run.
(True/False)
4.8/5 (77)
(77) The perfectly competitive firm's short-run shutdown rule is to shut down immediately if
(Multiple Choice)
4.9/5 (94)
(94) Figure 10-4
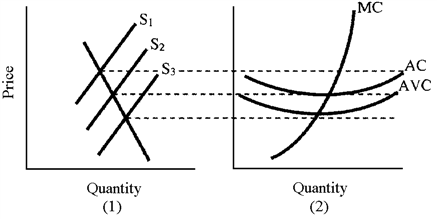 Figure 10-4 shows the industry's supply and demand curves in panel (1)and the cost curves of a firm in the industry in panel (2). At S2, the firm is
 (Multiple Choice)
5.0/5 (85)
(85) Long-run average cost of the perfectly competitive firm includes the
(Multiple Choice)
4.7/5 (103)
(103) Economic profit equals gross earnings minus the firm's direct costs.
(True/False)
4.9/5 (73)
(73) Which of the following is a characteristic of a perfectly competitive market?
(Multiple Choice)
4.8/5 (88)
(88) To own a taxicab in New York City, you must own a medallion. New York City regulates the number of official cabs by limiting the number of medallions. Explain why the New York cab industry is not competitive by reviewing the four conditions necessary for competition. NYC violates which one?
(Essay)
4.9/5 (85)
(85) The implications of the zero economic profit condition in a perfectly competitive market implies that the opportunity cost of capital is integrated into the firm's cost relationships.
(True/False)
4.8/5 (74)
(74) Illustrate the cost curves and average revenue (demand)curve for the perfectly competitive firm in long-run equilibrium.
(Essay)
4.9/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)