



 Chat with AI
Exam 10: The Firm and the Industry Under Perfect Competition

Exam 1: What Is Economics261 Questions
Exam 2: The Economy: Myth and Reality185 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice290 Questions
Exam 4: Supply and Demand: an Initial Look337 Questions
Exam 5: Consumer Choice: Individual and Market Demand243 Questions
Exam 6: Demand and Elasticity254 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis260 Questions
Exam 8: Output, Price, and Profit: the Importance of Marginal Analysis234 Questions
Exam 9: The Financial Markets and the Economy: the Tail That Wags the Dog227 Questions
Exam 10: The Firm and the Industry Under Perfect Competition253 Questions
Exam 11: The Case for Free Markets: the Price System259 Questions
Exam 12: Monopoly244 Questions
Exam 13: Between Competition and Monopoly254 Questions
Exam 14: Limiting Market Power: Antitrust and Regulation155 Questions
Exam 15: The Shortcomings of Free Markets219 Questions
Exam 16: Externalities, Externaliteis, the Environment, and Natural Resources222 Questions
Exam 17: Taxation and Resource Allocation221 Questions
Exam 18: Pricing the Factors of Production233 Questions
Exam 19: Labor and Entrepreneurship: the Human Inputs271 Questions
Exam 20: Poverty, Inequality, and Discrimination171 Questions
Exam 21: International Trade and Comparative Advantage226 Questions
Exam 22: Contemporary Issues in the Us Economy23 Questions
Select questions type


In the short run, the lowest price that a perfectly competitive firm will accept without closing its doors is found by examining the average variable cost curve.
(True/False)
4.8/5  (85)
(85) Sally Rand owns a ceiling fan company. She sells 1,000 ceiling fans at $50 each. Each fan costs her $20. She uses her own money to buy the fans; she withdraws the money from her savings account where it earns 5 percent interest. Before going into the ceiling fan business, she worked as a fan-dancer at $25,000 a year. Should Sally remain in business?
(Essay)
4.8/5 (84)
(84) The strength of the competition faced by a company can profoundly affect its
(Multiple Choice)
4.9/5 (70)
(70) What is the relationship between the long-run industry supply curve and the short-run supply curve in a perfectly competitive market?
(Essay)
4.9/5 (72)
(72) Show what happens to the industry equilibrium when new firms enter a perfectly competitive market in the long run.
(Essay)
4.9/5 (68)
(68) Exhibit 10-1 A perfectly competitive producer has the following short-run average cost curve and marginal cost curve: SR AC = 2Q + 3
MC = 4Q + 3
Where costs are measured in dollars and Q represents the firm's output in units.
If the market price of wangdoodles is $15 each, the profit-maximizing producer whose short-run cost curves are given in Exhibi should produce ____ wangdoodles.
(Multiple Choice)
4.9/5 (87)
(87) A perfectly competitive firm may, under some circumstances, be able to affect the market price.
(True/False)
4.9/5 (83)
(83) If the opportunity cost of capital is below the rate of return to capital in the perfectly competitive beauty salon industry,
(Multiple Choice)
4.9/5 (76)
(76) Perfect competition displays the market mechanism at its best in many respects, yet most markets in operation today are monopolistic or oligopolistic, composed of a few large firms. Should government regulation break up those large firms into several smaller firms to try to achieve perfect competition? Why or why not?
(Essay)
4.9/5 (93)
(93) Which of the following most resembles a perfectly competitive market?
(Multiple Choice)
4.7/5 (88)
(88) Figure 10-5
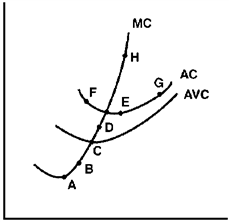 Figure 10-5 shows supply and demand conditions in a perfectly competitive industry and for a firm in that industry. At point C, the firm would
 (Multiple Choice)
4.8/5 (90)
(90) What is the nature of the elasticity of the demand curve faced by perfectly competitive firm?
(Multiple Choice)
4.9/5 (74)
(74) Which of the following decisions cannot be taken by a firm in a perfectly competitive market?
(Multiple Choice)
4.8/5 (79)
(79) In the short run, a perfectly competitive firm can make a profit, a loss, or go out of business.
(True/False)
4.9/5 (79)
(79) In the short run, a firm may have accounting losses and remain in operation.
(True/False)
4.9/5 (71)
(71) A perfectly competitive firm's short-run supply is infinite at the market price.
(True/False)
4.8/5 (63)
(63) A firm that is operating at a loss may continue to operate for a while because of costs that it will still have to pay even if production ceases.
(True/False)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)