



 Chat with AI
Exam 10: The Firm and the Industry Under Perfect Competition

Exam 1: What Is Economics261 Questions
Exam 2: The Economy: Myth and Reality185 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice290 Questions
Exam 4: Supply and Demand: an Initial Look337 Questions
Exam 5: Consumer Choice: Individual and Market Demand243 Questions
Exam 6: Demand and Elasticity254 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis260 Questions
Exam 8: Output, Price, and Profit: the Importance of Marginal Analysis234 Questions
Exam 9: The Financial Markets and the Economy: the Tail That Wags the Dog227 Questions
Exam 10: The Firm and the Industry Under Perfect Competition253 Questions
Exam 11: The Case for Free Markets: the Price System259 Questions
Exam 12: Monopoly244 Questions
Exam 13: Between Competition and Monopoly254 Questions
Exam 14: Limiting Market Power: Antitrust and Regulation155 Questions
Exam 15: The Shortcomings of Free Markets219 Questions
Exam 16: Externalities, Externaliteis, the Environment, and Natural Resources222 Questions
Exam 17: Taxation and Resource Allocation221 Questions
Exam 18: Pricing the Factors of Production233 Questions
Exam 19: Labor and Entrepreneurship: the Human Inputs271 Questions
Exam 20: Poverty, Inequality, and Discrimination171 Questions
Exam 21: International Trade and Comparative Advantage226 Questions
Exam 22: Contemporary Issues in the Us Economy23 Questions
Select questions type


A firm in short-run equilibrium always earns positive profits if
(Multiple Choice)
4.9/5  (93)
(93) In perfect competition, there are differences in the products sold by various firms.
(True/False)
4.9/5 (78)
(78) A firm that knows the market price for its product and its costs can determine how much output that they wish to produce.
(True/False)
4.9/5 (65)
(65) The long-run supply curve of an industry equals the industry's
(Multiple Choice)
4.9/5 (70)
(70) When the market is in long-run equilibrium in a perfectly competitive market, this implies that in the long run means
(Multiple Choice)
4.9/5 (77)
(77) In long-run equilibrium, the perfectly competitive firm produces
(Multiple Choice)
4.8/5 (57)
(57) Figure 10-2
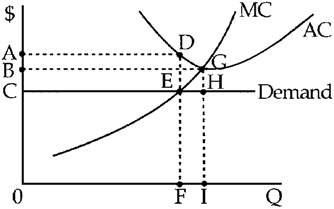 Figure 10-2 shows demand and short-run cost curves for a perfectly competitive firm. In the short run, this firm would
 (Multiple Choice)
4.9/5 (69)
(69) In the short run, a perfectly competitive firm can either make a profit or exit the market.
(True/False)
4.9/5 (79)
(79) Table 10-1 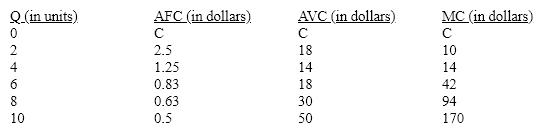 In Table 10-1 the short-run cost schedules of a perfectly competitive firm are shown. Suppose that the market price of output is $20, the firm will produce ____ units and earn a profit of ____.
 (Multiple Choice)
4.8/5 (70)
(70) Explain the reasoning behind the shutdown rules. When is it appropriate to operate with a loss?
(Essay)
4.7/5 (67)
(67) The perfectly competitive firm has no influence over price because
(Multiple Choice)
4.9/5 (72)
(72) Define the following terms and explain their importance to the study of economics.
a. marginal cost
b. marginal revenue
c. short-run equilibrium
d. supply curve of the firm
e. economic profit
(Essay)
4.8/5 (83)
(83) A perfectly competitive firm has a horizontal demand curve because it can sell as much as it wants at the market price.
(True/False)
4.8/5 (84)
(84) Which of the following statements concerning equilibrium in the long run is not true?
(Multiple Choice)
4.9/5 (81)
(81) Figure 10-8
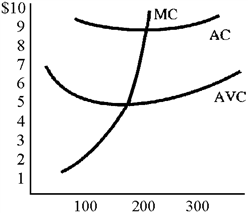 In the short run, the firm in Figure 10-8 will shut down if the price falls below
 (Multiple Choice)
4.9/5 (75)
(75) Which requirement for perfect competition rules out trade associations or other collusive arrangements in which firms work together to influence price?
(Multiple Choice)
4.8/5 (93)
(93) The result that perfectly competitive firms produce at the lowest per-unit cost is derived from the assumptions of
(Multiple Choice)
4.9/5 (82)
(82) Draw a graph illustrating the relationship between the demand curve of the perfectly competitive firm and the perfectly competitive industry. Label all curves and axes correctly.
(Essay)
4.8/5 (82)
(82) The exit of existing firms from an industry will very likely
(Multiple Choice)
4.8/5 (97)
(97) A subsidy to firms intended to reduce pollution in an industry would
(Multiple Choice)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)