



 Chat with AI
Exam 11: The Case for Free Markets: the Price System

Exam 1: What Is Economics254 Questions
Exam 2: The Economony: Myth and Reality184 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice278 Questions
Exam 4: Supply and Demand: an Initial Look297 Questions
Exam 5: Consumer Choice: Individual and Market Demand213 Questions
Exam 6: Demand and Elasticity247 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis246 Questions
Exam 8: Output, Price, and Profit: the Importance of Marginal Analysis232 Questions
Exam 9: The Financial Markets and the Economy: the Tail That Wags the Dog225 Questions
Exam 10: The Firm and the Industry Under Perfect Competition219 Questions
Exam 11: The Case for Free Markets: the Price System251 Questions
Exam 12: Monopoly236 Questions
Exam 13: Between Competition and Monopoly248 Questions
Exam 14: Limiting Market Power: Antitrust and Regulation152 Questions
Exam 15: The Shortcomings of Free Markets210 Questions
Exam 16: The Economics of the Environment, and Natural Resources218 Questions
Exam 17: Taxation and Resource Allocation218 Questions
Exam 18: Pricing the Factors of Production230 Questions
Exam 19: Labor and Entrepreneurship: the Human Inputs267 Questions
Exam 20: Poverty, Inequality, and Discrimination167 Questions
Exam 21: An Introduction to Macroeconomics212 Questions
Exam 22: The Goals of Macroeconomic Policy212 Questions
Exam 23: Economic Growth: Theory and Policy226 Questions
Exam 24: Aggregate Demand and the Powerful Consumer216 Questions
Exam 25: Demand-Side Equilibrium: Unemployment or Inflation215 Questions
Exam 26: Bringing in the Supply Side: Unemployment and Inflation228 Questions
Exam 27: Managing Aggregate Demand: Fiscal Policy207 Questions
Exam 28: Money and the Banking System222 Questions
Exam 29: Monetary Policy: Conventional and Unconventional208 Questions
Exam 30: The Financial Crisis and the Great Recession64 Questions
Exam 31: The Debate Over Monetary and Fiscal Policy216 Questions
Exam 32: Budget Deficits in the Short and Long Run214 Questions
Exam 33: The Trade-Off Between Inflation and Unemployment218 Questions
Exam 34: International Trade and Comparative Advantage215 Questions
Exam 35: The International Monetary System: Order or Disorder216 Questions
Exam 36: Exchange Rates and the Macroeconomy215 Questions
Exam 37: Contemporary Issues in the Useconomy23 Questions
Select questions type


Goods are distributed efficiently if everyone gets an equal share of each good.
(True/False)
5.0/5  (84)
(84) Politicians and citizens may often choose policies that reduce economic efficiency because they are perceived as "fairer."
(True/False)
4.9/5 (83)
(83) The slope of a typical production possibilities frontier reflects the fact that
(Multiple Choice)
4.8/5 (97)
(97) Prices set too low can actually be against the public interest.
(True/False)
4.9/5 (71)
(71) The coordination task of any economy that answers the question of how output shall be divided among consumers may best be described as
(Multiple Choice)
5.0/5 (85)
(85) An efficient allocation of resources is demonstrated by a point
(Multiple Choice)
4.9/5 (77)
(77) Scarcity limits the volume of goods that an economic system can produce but does not limit the production of services.
(True/False)
5.0/5 (82)
(82) Prices influence the distribution of income by making the distribution fairer.
(True/False)
5.0/5 (70)
(70) Using prices to promote efficiency in the utilization of bridges,
(Multiple Choice)
4.7/5 (80)
(80) Figure 11-1
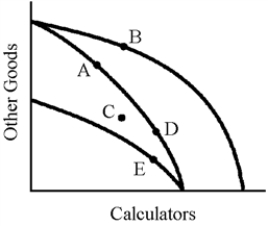 -In Figure 11-1, a cost-reducing technological breakthrough in calculator production would cause which movement?
 (Multiple Choice)
4.9/5 (71)
(71) In order for a central planner to achieve the invisible-hand type efficiency of a free market, the planner would
(Multiple Choice)
4.8/5 (80)
(80) In a market system, the primary instruments used to coordinate economic activity are
(Multiple Choice)
4.8/5 (80)
(80) Marxists and leaders of communist economies actually often admire the market mechanism for its
(Multiple Choice)
4.8/5 (82)
(82) MC and MU are set equal to one another in a market economy because
(Multiple Choice)
4.7/5 (77)
(77) Uncoordinated decisions in perfect competition lead to mass confusion and inefficiency.
(True/False)
4.8/5 (92)
(92) Any increase in efficiency increases only profits of producers, with no increase in output.
(True/False)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)