



 Chat with AI
Exam 11: The Case for Free Markets: the Price System

Exam 1: What Is Economics254 Questions
Exam 2: The Economony: Myth and Reality184 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice278 Questions
Exam 4: Supply and Demand: an Initial Look297 Questions
Exam 5: Consumer Choice: Individual and Market Demand213 Questions
Exam 6: Demand and Elasticity247 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis246 Questions
Exam 8: Output, Price, and Profit: the Importance of Marginal Analysis232 Questions
Exam 9: The Financial Markets and the Economy: the Tail That Wags the Dog225 Questions
Exam 10: The Firm and the Industry Under Perfect Competition219 Questions
Exam 11: The Case for Free Markets: the Price System251 Questions
Exam 12: Monopoly236 Questions
Exam 13: Between Competition and Monopoly248 Questions
Exam 14: Limiting Market Power: Antitrust and Regulation152 Questions
Exam 15: The Shortcomings of Free Markets210 Questions
Exam 16: The Economics of the Environment, and Natural Resources218 Questions
Exam 17: Taxation and Resource Allocation218 Questions
Exam 18: Pricing the Factors of Production230 Questions
Exam 19: Labor and Entrepreneurship: the Human Inputs267 Questions
Exam 20: Poverty, Inequality, and Discrimination167 Questions
Exam 21: An Introduction to Macroeconomics212 Questions
Exam 22: The Goals of Macroeconomic Policy212 Questions
Exam 23: Economic Growth: Theory and Policy226 Questions
Exam 24: Aggregate Demand and the Powerful Consumer216 Questions
Exam 25: Demand-Side Equilibrium: Unemployment or Inflation215 Questions
Exam 26: Bringing in the Supply Side: Unemployment and Inflation228 Questions
Exam 27: Managing Aggregate Demand: Fiscal Policy207 Questions
Exam 28: Money and the Banking System222 Questions
Exam 29: Monetary Policy: Conventional and Unconventional208 Questions
Exam 30: The Financial Crisis and the Great Recession64 Questions
Exam 31: The Debate Over Monetary and Fiscal Policy216 Questions
Exam 32: Budget Deficits in the Short and Long Run214 Questions
Exam 33: The Trade-Off Between Inflation and Unemployment218 Questions
Exam 34: International Trade and Comparative Advantage215 Questions
Exam 35: The International Monetary System: Order or Disorder216 Questions
Exam 36: Exchange Rates and the Macroeconomy215 Questions
Exam 37: Contemporary Issues in the Useconomy23 Questions
Select questions type


The laissez-faire system relies on the price mechanism to allocate resources.
(True/False)
4.8/5  (83)
(83) Society might argue that there are cases in which it is appropriate to resist price increases in situations where scarcity is serious.Included would be the case of
(Multiple Choice)
4.9/5 (71)
(71) If arrival and departure delays are frequent early in the morning and late afternoons, but there are no delays during the evening hours, we can conclude that the airport authority
(Multiple Choice)
4.9/5 (83)
(83) After the Arab oil embargoes, there was concern about the impact of higher gas prices on the low-income worker.The government imposed price controls on oil to protect the poor from this situation.Explain the inefficiency of this price ceiling and how taxes, rather than prices, could be used to solve the problem.
(Essay)
4.9/5 (75)
(75) Before a market allocation of goods on the production possibilities curve can be judged efficient, one must evaluate "what" goods the market produced.
(True/False)
4.9/5 (84)
(84) The task of deciding which consumer gets each of the goods produced in a free-market economy is solved by
(Multiple Choice)
4.9/5 (67)
(67) Central planning is an efficient method for making coordination decisions.
(True/False)
4.8/5 (91)
(91) Figure 11-1
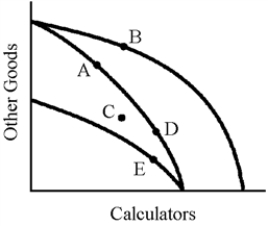 -In Figure 11-1, what can be concluded about the economy if production moves from Point D to Point A?
 (Multiple Choice)
4.8/5 (84)
(84) A factory in a centrally planned economy produces 1,000 left shoes and no right shoes.No corresponding factory produces only right shoes.This outcome is an example of inefficiency in
(Multiple Choice)
4.9/5 (90)
(90) In a free market, a given unit of an input will be used by the firm that
(Multiple Choice)
4.8/5 (78)
(78) Scarcity is illustrated graphically by a production possibilities frontier.
(True/False)
4.8/5 (73)
(73) Command economies are able to achieve greater allocative efficiency than market economies.
(True/False)
4.9/5 (82)
(82) The producer's surplus is equal to the difference between how much the seller can charge for a product and how much the consumer is willing to purchase it for.
(True/False)
4.7/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)