



 Chat with AI
Exam 35: International Trade and Comparative Advantage

Exam 1: What Is Economics?227 Questions
Exam 2: The Economy: Myth and Reality150 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice250 Questions
Exam 4: Supply and Demand: An Initial Look308 Questions
Exam 5: Consumer Choice: Individual and Market Demand202 Questions
Exam 6: Demand and Elasticity209 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis216 Questions
Exam 8: Output, Price, and Profit: The Importance of Marginal Analysis189 Questions
Exam 9: Securities: Business Finance, and the Economy: The Tail that Wags the Dog?198 Questions
Exam 10: The Firm and the Industry under Perfect Competition208 Questions
Exam 11: Monopoly203 Questions
Exam 12: Between Competition and Monopoly225 Questions
Exam 13: Limiting Market Power: Regulation and Antitrust152 Questions
Exam 14: The Case for Free Markets I: The Price System220 Questions
Exam 15: The Shortcomings of Free Markets212 Questions
Exam 16: The Market's Prime Achievement: Innovation and Growth110 Questions
Exam 17: Externalities, the Environment, and Natural Resources217 Questions
Exam 18: Taxation and Resource Allocation219 Questions
Exam 19: Pricing the Factors of Production228 Questions
Exam 20: Labor and Entrepreneurship: The Human Inputs223 Questions
Exam 21: Poverty, Inequality, and Discrimination167 Questions
Exam 22: An Introduction to Macroeconomics211 Questions
Exam 23: The Goals of Macroeconomic Policy207 Questions
Exam 24: Economic Growth: Theory and Policy223 Questions
Exam 25: Aggregate Demand and the Powerful Consumer214 Questions
Exam 26: Demand-Side Equilibrium: Unemployment or Inflation?210 Questions
Exam 27: Bringing in the Supply Side: Unemployment and Inflation?223 Questions
Exam 28: Managing Aggregate Demand: Fiscal Policy205 Questions
Exam 29: Money and the Banking System219 Questions
Exam 30: Monetary Policy: Conventional and Unconventional205 Questions
Exam 31: The Financial Crisis and the Great Recession61 Questions
Exam 32: The Debate over Monetary and Fiscal Policy214 Questions
Exam 33: Budget Deficits in the Short and Long Run210 Questions
Exam 34: The Trade-Off between Inflation and Unemployment214 Questions
Exam 35: International Trade and Comparative Advantage226 Questions
Exam 36: The International Monetary System: Order or Disorder?213 Questions
Exam 37: Exchange Rates and the Macroeconomy214 Questions
Select questions type


Many countries impose tariffs or quotas to protect the domestic industry from competition.
(True/False)
4.7/5  (85)
(85) ____ is a doctrine that holds that exports are good for a country, whereas imports are harmful.
(Multiple Choice)
4.8/5 (84)
(84) After the American Civil War, many prominent Southerners lamented the fact that the South "overproduced" cotton and "underproduced" food.In fact, the South did import a very large percentage of its food.Nevertheless, rather than reduce cotton production and grow more food, Southern farmers did the opposite because
(Multiple Choice)
4.9/5 (88)
(88) Labor is defined as cheap only if its productivity is very low.
(True/False)
4.9/5 (84)
(84) Figure 18-5
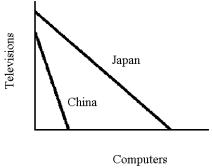 -From the graph in Figure 18-5 (curves show output per unit of labor input), one can infer that
 (Multiple Choice)
5.0/5 (73)
(73) An export subsidy helps reduce the selling price of a product by allowing individual producers to charge less and still cover all of their production costs.
(True/False)
4.9/5 (88)
(88) A country has an absolute advantage over another in the production of widgets if it can produce
(Multiple Choice)
4.8/5 (77)
(77) Quotas and tariffs provide the same outcome: restriction of international trade and higher prices for consumers.
(True/False)
4.7/5 (81)
(81) An import quota will ordinarily raise the price of the good in the importing country.
(True/False)
4.8/5 (89)
(89) If two countries have production possibilities curves with different slopes, there is no possibility for gains from trade.
(True/False)
4.8/5 (78)
(78) Figure 18-10
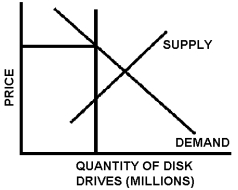 -Figure 18-10 shows the effect on the market for disk drives of a(n)
 (Multiple Choice)
5.0/5 (76)
(76) Opening trade between a nation that has "cheap labor" and one that has "expensive labor" will
(Multiple Choice)
4.9/5 (75)
(75) Assume that a country imposes a tariff in order to gain a price advantage on an item.What is the typical response from the exporting country?
(Multiple Choice)
4.8/5 (84)
(84) Table 18-4
Quantity Quantity Quantity Quantity Price per Demanded Supplied Demanded Supplied TV in United States in United States Japan Japan 100 100 10 100 25 200 85 20 85 50 300 70 30 70 70 400 60 40 60 80 500 50 50 50 90 600 40 60 40 100 700 30 70 30 110 800 30 80 20 120
-Table 18-4 presents the demand and supply schedules for television sets in Japan and the United States.If Japan and the United States trade with each other, what will be the equilibrium price in the world market for television sets?
(Multiple Choice)
4.7/5 (91)
(91) One of the main reasons that people want to limit imports is the
(Multiple Choice)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)