



 Chat with AI
Exam 35: International Trade and Comparative Advantage

Exam 1: What Is Economics?227 Questions
Exam 2: The Economy: Myth and Reality150 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice250 Questions
Exam 4: Supply and Demand: An Initial Look308 Questions
Exam 5: Consumer Choice: Individual and Market Demand202 Questions
Exam 6: Demand and Elasticity209 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis216 Questions
Exam 8: Output, Price, and Profit: The Importance of Marginal Analysis189 Questions
Exam 9: Securities: Business Finance, and the Economy: The Tail that Wags the Dog?198 Questions
Exam 10: The Firm and the Industry under Perfect Competition208 Questions
Exam 11: Monopoly203 Questions
Exam 12: Between Competition and Monopoly225 Questions
Exam 13: Limiting Market Power: Regulation and Antitrust152 Questions
Exam 14: The Case for Free Markets I: The Price System220 Questions
Exam 15: The Shortcomings of Free Markets212 Questions
Exam 16: The Market's Prime Achievement: Innovation and Growth110 Questions
Exam 17: Externalities, the Environment, and Natural Resources217 Questions
Exam 18: Taxation and Resource Allocation219 Questions
Exam 19: Pricing the Factors of Production228 Questions
Exam 20: Labor and Entrepreneurship: The Human Inputs223 Questions
Exam 21: Poverty, Inequality, and Discrimination167 Questions
Exam 22: An Introduction to Macroeconomics211 Questions
Exam 23: The Goals of Macroeconomic Policy207 Questions
Exam 24: Economic Growth: Theory and Policy223 Questions
Exam 25: Aggregate Demand and the Powerful Consumer214 Questions
Exam 26: Demand-Side Equilibrium: Unemployment or Inflation?210 Questions
Exam 27: Bringing in the Supply Side: Unemployment and Inflation?223 Questions
Exam 28: Managing Aggregate Demand: Fiscal Policy205 Questions
Exam 29: Money and the Banking System219 Questions
Exam 30: Monetary Policy: Conventional and Unconventional205 Questions
Exam 31: The Financial Crisis and the Great Recession61 Questions
Exam 32: The Debate over Monetary and Fiscal Policy214 Questions
Exam 33: Budget Deficits in the Short and Long Run210 Questions
Exam 34: The Trade-Off between Inflation and Unemployment214 Questions
Exam 35: International Trade and Comparative Advantage226 Questions
Exam 36: The International Monetary System: Order or Disorder?213 Questions
Exam 37: Exchange Rates and the Macroeconomy214 Questions
Select questions type


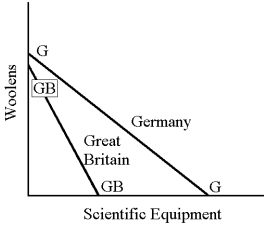 -In Figure 18-1,

Any restriction of international trade that is accomplished by a quota can also be accomplished by a tariff.
(True/False)
4.9/5  (72)
(72) If England uses one week's time to produce ten yards of cloth or two barrels of wine and Portugal uses one week's time to produce twelve yards of cloth or six barrels of wine, England has the comparative advantage in both goods.
(True/False)
4.9/5 (78)
(78) A tariff on imports affects foreign suppliers ____; a quota affects foreign suppliers ____.
(Multiple Choice)
4.8/5 (82)
(82) "The United States has more oil in Alaska than there is oil in Kuwait.Therefore, the United States should stop importing oil." Evaluate this statement using economic analysis.
(Essay)
4.8/5 (77)
(77) Is the call for protection on the basis of "infant industry" valid?
(Multiple Choice)
4.8/5 (86)
(86) Table 18-4
Quantity Quantity Quantity Quantity Price per Demanded Supplied Demanded Supplied TV in United States in United States Japan Japan 100 100 10 100 25 200 85 20 85 50 300 70 30 70 70 400 60 40 60 80 500 50 50 50 90 600 40 60 40 100 700 30 70 30 110 800 30 80 20 120
-Table 18-4 presents the demand and supply schedules for television sets in Japan and the United States.If there is no trade between these countries, what are the equilibrium price and quantity in the United States?
(Multiple Choice)
4.8/5 (69)
(69) Which of the following might lead a nation to engage in international trade?
(Multiple Choice)
4.9/5 (91)
(91) A country's comparative advantage can be illustrated by the graph of the production possibilities frontier.
(True/False)
4.8/5 (74)
(74) Figure 18-5
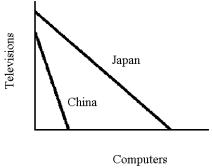 -From the graph in Figure 18-5 (curves show output per unit of labor input), one can infer that
 (Multiple Choice)
4.9/5 (80)
(80) A tariff is a limitation on the amount of a good that can be imported.
(True/False)
4.8/5 (87)
(87) The economic effects of a quota are identical to those of a tariff.
(True/False)
4.8/5 (84)
(84) According to the ____ view, a nation's wealth consists of the amount of gold or other monies at its command.
(Multiple Choice)
4.8/5 (79)
(79) Table 18-2
Output Per Unit Labor Input Cloth 20 24 Wine 2 12
-Using the data from Table 18-2, suppose England transfers 2 units of labor from wine to cloth and Portugal transfers 1 unit from cloth to wine.The combined production of wine and cloth will be increased by
(Multiple Choice)
4.9/5 (77)
(77) Both tariffs and quotas will restrict supplies coming into the country from abroad.
(True/False)
5.0/5 (73)
(73) Carefully define the following terms and explain their importance to the study of economics.
a.specialization
b.absolute advantage
c.comparative advantage
d.quota
e.trade adjustment assistance
(Essay)
5.0/5 (84)
(84) One nation can gain from an exchange only at the expense of another.
(True/False)
4.9/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)