



 Chat with AI
Exam 5: Consumer Choice: Individual and Market Demand

Exam 1: What Is Economics?227 Questions
Exam 2: The Economy: Myth and Reality150 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice250 Questions
Exam 4: Supply and Demand: An Initial Look308 Questions
Exam 5: Consumer Choice: Individual and Market Demand202 Questions
Exam 6: Demand and Elasticity209 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis216 Questions
Exam 8: Output, Price, and Profit: The Importance of Marginal Analysis189 Questions
Exam 9: Securities: Business Finance, and the Economy: The Tail that Wags the Dog?198 Questions
Exam 10: The Firm and the Industry under Perfect Competition208 Questions
Exam 11: Monopoly203 Questions
Exam 12: Between Competition and Monopoly225 Questions
Exam 13: Limiting Market Power: Regulation and Antitrust152 Questions
Exam 14: The Case for Free Markets I: The Price System220 Questions
Exam 15: The Shortcomings of Free Markets212 Questions
Exam 16: The Market's Prime Achievement: Innovation and Growth110 Questions
Exam 17: Externalities, the Environment, and Natural Resources217 Questions
Exam 18: Taxation and Resource Allocation219 Questions
Exam 19: Pricing the Factors of Production228 Questions
Exam 20: Labor and Entrepreneurship: The Human Inputs223 Questions
Exam 21: Poverty, Inequality, and Discrimination167 Questions
Exam 22: An Introduction to Macroeconomics211 Questions
Exam 23: The Goals of Macroeconomic Policy207 Questions
Exam 24: Economic Growth: Theory and Policy223 Questions
Exam 25: Aggregate Demand and the Powerful Consumer214 Questions
Exam 26: Demand-Side Equilibrium: Unemployment or Inflation?210 Questions
Exam 27: Bringing in the Supply Side: Unemployment and Inflation?223 Questions
Exam 28: Managing Aggregate Demand: Fiscal Policy205 Questions
Exam 29: Money and the Banking System219 Questions
Exam 30: Monetary Policy: Conventional and Unconventional205 Questions
Exam 31: The Financial Crisis and the Great Recession61 Questions
Exam 32: The Debate over Monetary and Fiscal Policy214 Questions
Exam 33: Budget Deficits in the Short and Long Run210 Questions
Exam 34: The Trade-Off between Inflation and Unemployment214 Questions
Exam 35: International Trade and Comparative Advantage226 Questions
Exam 36: The International Monetary System: Order or Disorder?213 Questions
Exam 37: Exchange Rates and the Macroeconomy214 Questions
Select questions type


A consumer will consume the combination of goods at the crossing point of a budget line and indifference curve.
(True/False)
5.0/5  (89)
(89) An individual's demand curve for a good is ____ her marginal utility curve for the good.
(Multiple Choice)
4.7/5 (66)
(66) If a good has "snob appeal," consumers may purchases less when the price falls.
(True/False)
4.7/5 (85)
(85) Total utility always decreases when additional amounts of a commodity are consumed.
(True/False)
4.7/5 (85)
(85) The resolution of Adam Smith's diamond-water puzzle is based on the distinction between marginal and total utility.
(True/False)
4.7/5 (72)
(72) If total utility declines as an additional unit of a commodity is purchased,
(Multiple Choice)
4.8/5 (69)
(69) Figure 5-12
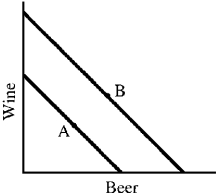 -In Figure 5-12, the move in the consumer equilibrium from A to B shows that
 (Multiple Choice)
5.0/5 (73)
(73) A decrease in the price of one good results in a parallel shift in the budget line.
(True/False)
4.8/5 (78)
(78) As a rule, as a consumer acquires more and more of a good, the marginal utility declines.
(True/False)
4.9/5 (69)
(69) The marginal rate of substitution represents the maximum amount of one commodity a consumer is willing to give up in exchange for one more unit of another commodity.
(True/False)
4.9/5 (77)
(77) The law of diminishing marginal utility is consistent with the consumer behavior that produces a negatively sloped demand curve.
(True/False)
4.9/5 (98)
(98) Because the consumer's budget is limited, purchase decisions among available goods must of necessity be interdependent.
(True/False)
4.9/5 (86)
(86) Figure 5-14
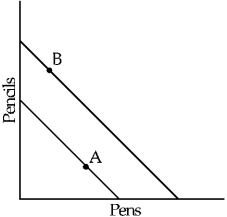 -Martha initially buys the combination of pens and pencils shown as A in Figure 5-14.After the prices of both goods change, she buys combination B.It must be true that
 (Multiple Choice)
5.0/5 (63)
(63) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)