



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics220 Questions
Exam 2: Thinking Like an Economist284 Questions
Exam 3: Interdependence and the Gains From Trade192 Questions
Exam 4: The Market Forces of Supply and Demand277 Questions
Exam 5: Elasticity and Its Application222 Questions
Exam 6: Supply, Demand, and Government Policies321 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets218 Questions
Exam 8: Applications: The Costs of Taxation203 Questions
Exam 9: Application: International Trade214 Questions
Exam 10: Externalities204 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System225 Questions
Exam 13: The Costs of Production261 Questions
Exam 14: Firms in Competitive Markets243 Questions
Exam 15: Monopoly231 Questions
Exam 16: Monopolistic Competition246 Questions
Exam 17: Oligopoly204 Questions
Exam 18: The Markets for the Factors of Production232 Questions
Exam 19: Earnings and Discrimination230 Questions
Exam 20: Income Inequality and Poverty194 Questions
Exam 21: The Theory of Consumer Choice209 Questions
Exam 22: Frontiers in Microeconomics185 Questions
Exam 23: Measuring a Nations Income231 Questions
Exam 24: Measuring the Cost of Living214 Questions
Exam 25: Production and Growth187 Questions
Exam 26: Saving, Investment, and the Financial System225 Questions
Exam 27: Tools of Finance198 Questions
Exam 28: Unemployment and Its Natural Rate361 Questions
Exam 29: The Monetary System210 Questions
Exam 30: Money Growth and Inflation201 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts194 Questions
Exam 32: A Macroeconomic Theory of the Open Economy188 Questions
Exam 33: Aggregate Demand and Aggregate Supply189 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand207 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment223 Questions
Exam 36: Six Debates Over Macroeconomic Policy154 Questions
Select questions type


A firm sells 100 units of output and its total revenue is $800. The firm's average revenue amounts to __________.
(Short Answer)
4.9/5  (79)
(79) For an individual firm operating in a competitive market, marginal revenue equals
(Multiple Choice)
4.9/5 (77)
(77) A firm operating in a perfectly competitive industry will continue to operate if it earns zero economic profits because it is likely to be earning positive accounting profits.
(True/False)
5.0/5 (68)
(68) A competitive firm's short-run supply curve intersects its average-total-cost curve at the point (Q = 450, P = $22). What is the value of marginal cost at Q = 450?
(Essay)
4.9/5 (85)
(85) A firm is currently producing 100 units of output per day. The manager reports to the owner that producing the 100th unit costs the firm $5. The firm can sell the 100th unit for $5. The firm should continue to produce 100 units in order to maximize its profits (or minimize its losses).
(True/False)
4.9/5 (82)
(82) For a firm, marginal revenue minus marginal cost is equal to
(Multiple Choice)
4.8/5 (81)
(81) The stable, long-run equilibrium in a competitive market occurs when the market price equals the lowest point on a firm's average total cost curve.
(True/False)
4.8/5 (78)
(78) Figure 14-1
Suppose that a firm in a competitive market has the following cost curves: 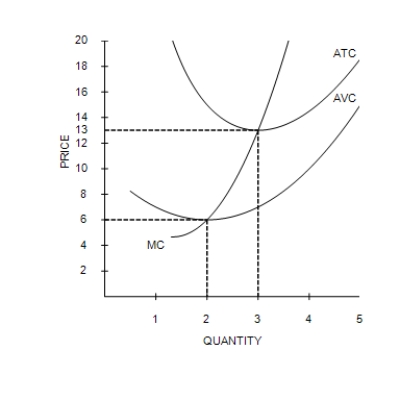
-Refer to Figure 14-1. The firm's short-run supply curve is its marginal cost curve above
-Refer to Figure 14-1. The firm's short-run supply curve is its marginal cost curve above (Multiple Choice)
4.8/5 (92)
(92) A competitive firm is maximizing its profit by selling 150 units of output. The firm's marginal cost is $8 and its average total cost is $6. The firm's profit amounts to __________.
(Short Answer)
4.8/5 (71)
(71) Suppose a firm is considering producing zero units of output. We call this exiting an industry in the short run and shutting down in the long run.
(True/False)
4.8/5 (78)
(78) The supply curve of a firm in a competitive market is the average variable cost curve above the minimum of marginal cost.
(True/False)
4.9/5 (64)
(64) A popular resort restaurant will maximize profits if it chooses to stay open during the less-crowded "off season" when its total revenues exceed its fixed costs.
(True/False)
4.8/5 (87)
(87) Scenario 14-2
The information below applies to a competitive firm that sells its output for $45 per unit.
• When the firm produces and sells 120 units of output, its average total cost is $23.5.
• When the firm produces and sells 121 units of output, its average total cost is $23.65.
-Refer to Scenario 14-2. Suppose the firm is currently producing and selling 120 units of output. Should the firm increase its output to 121 units?
(Multiple Choice)
4.9/5 (80)
(80) Cold Duck Airlines flies between Tacoma and Portland. The company leases planes on a year-long contract at a cost that averages $600 per flight. Other costs (fuel, flight attendants, etc.) amount to $550 per flight. Currently, Cold Duck's revenues are $1,000 per flight. All prices and costs are expected to continue at their present levels. If it wants to maximize profit, Cold Duck Airlines should
(Multiple Choice)
4.9/5 (81)
(81) If a firm in a perfectly competitive market triples the quantity of output sold, then total revenue will
(Multiple Choice)
4.9/5 (76)
(76) A firm operating in a perfectly competitive market may earn positive, negative, or zero economic profit in the short run.
(True/False)
4.8/5 (76)
(76) When an individual firm in a competitive market decreases its production, it is likely that the market price will rise.
(True/False)
4.9/5 (80)
(80) If a firm can influence the market price of the good it sells, then it is said to have __________.
(Short Answer)
4.9/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)