



 Chat with AI
Exam 18: Accounting for Income Taxes

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


At the beginning of 2016, Jasper Company had a deferred tax asset of $7,000 related to the warranty liability on its balance sheet. At the end of 2016, the company estimates that its ending warranty liability is $40,000. Taxable income is $60,000, and the tax rate is 40%.
Required:
a. Prepare the journal entry to record income taxes for the year.
b. Assume the company decides at the end of the year that it is "more likely than not" that $11,000 of the deductible temporary difference will not be realized. Prepare the appropriate journal entry.
c. Show how the deferred tax asset would be reported on the balance sheet for
2016.
(Essay)
4.8/5  (87)
(87) In accounting for income taxes, percentage depletion in excess of cost depletion is an example of
(Multiple Choice)
5.0/5 (85)
(85) The Flintstone Company incurred the following expenses in 2016, which are reported differently for financial reporting purposes and taxable income: 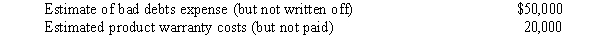 If the tax rate is 40%, what is the total temporary difference?
 (Multiple Choice)
4.9/5 (75)
(75) A company determines whether to recognize an uncertain tax position by evaluating whether the tax position will
"more likely than not" be upheld during a tax audit by the IRS, based on the technical merits of the position.
(True/False)
4.8/5 (69)
(69) The new presentation requirements for deferred tax assets and liabilities require that
(Multiple Choice)
4.9/5 (77)
(77) In order to implement the FASB's objectives what four principles must a corporation apply to account for its income taxes?
(Essay)
4.9/5 (78)
(78) If a corporation recognizes an operating loss carryforward in the year of the loss, the corporation will deduct the tax benefit from its operating loss.
(True/False)
5.0/5 (93)
(93) What disclosures are required for "uncertain tax positions" where the position is "more likely than not" of being upheld during a tax audit by the IRS?
(Essay)
4.7/5 (79)
(79) Rehobeth Company's taxable income and other financial data for 2016 are presented below: 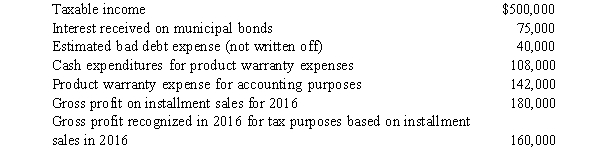 Required:
a. Calculate Rehobeth Company's 2016 pretax financial income.
b. For each item, explain why there is a difference, if any exists, between how it is treated for taxable income purposes and pretax financial income.
Required:
a. Calculate Rehobeth Company's 2016 pretax financial income.
b. For each item, explain why there is a difference, if any exists, between how it is treated for taxable income purposes and pretax financial income. (Essay)
4.9/5 (84)
(84) All of the following are income tax disclosures required by GAAP except:
(Multiple Choice)
4.9/5 (87)
(87) Interperiod income tax allocation is based on the assumption that
(Multiple Choice)
4.8/5 (83)
(83) In 2016, Waterford Corporation reported pretax financial income of $400,000. Included in that pretax financial income was $150,000 of nontaxable life insurance proceeds received as a result of the death of an officer; $120,000 of warranty expenses accrued but unpaid as of December 31, 2016; and $10,000 of bad debts estimated to be uncollectible but not written off as of December 31, 2016). Assuming that no income taxes were previously paid during the year and an income tax rate of 30%, what is the amount of income taxes payable on December 31, 2016?
(Multiple Choice)
4.8/5 (67)
(67) Income taxes for financial accounting purposes are apportioned to each of the following items except
(Multiple Choice)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)