



 Chat with AI
Exam 19: Accounting for Post-Retirement Benefits

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


In deciding how to recognize prior period cost, accounting regulators opted to recognize the liability and reduce other comprehensive income, then amortize the prior service cost as a component of pension expense. The liability is reduced and other comprehensive income is increased as the prior service amount is amortized. This method was chosen in response to constituent arguments even though it violates the matching concept .

Free
(True/False)
4.8/5  (83)
(83) Correct Answer: Verified
True
To improve usefulness of defined pension plans, GAAP requires disclosure of reconciliations of the beginning and ending amounts of the projected benefit obligation, including the amounts of the service cost, interest cost, actuarial gains and losses, benefits paid, and plan amendments.
Free
(True/False)
4.8/5 (82)
(82) Correct Answer:Verified
VerifiedTrue
What disclosures are required by GAAP about a company's defined benefit pension plan?
(Essay)
4.9/5 (84)
(84) Which of the following statements is true regarding a defined contribution pension plan?
(Multiple Choice)
4.7/5 (75)
(75) Exhibit 19-02
The Sophia Company adopted a defined benefit pension plan on January 1, 2015, and prior service credit was granted to employees. The present value of those benefits was calculated to be $1,245,300 at that date. The service cost is funded in full at the end of each year, plus an additional amount of $225,000 is funded each year-end. The unrecognized prior service cost is being amortized by the straight-line method over the remaining 10-year service life of the company's active employees. Additional information relating to the company's pension plan is presented below: 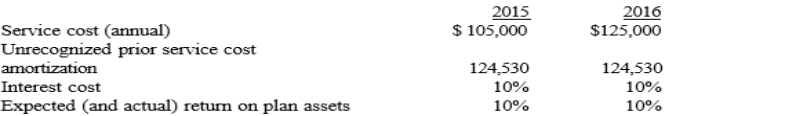 -Refer to Exhibit 19-02. What is the pension expense for 2015?
 (Multiple Choice)
4.8/5 (76)
(76) Disclosures for a defined benefit pension plan should include which of the following? I. number of beneficiaries
II. reconciliation of the ending value of the projected benefit obligation
III. reconciliation of the ending fair value of the plan assets
IV. the composition of plan assets
V. the discount rate used
VI. expected long-term rate of return on plan assets
(Multiple Choice)
5.0/5 (80)
(80) If a company uses the indirect method to report cash flows, it
(Multiple Choice)
4.7/5 (72)
(72) Exhibit 19-01
Marley Co. has an underfunded prepaid/accrued pension cost of $2,000 debit balance) at December 31, 2015. The following information pertains to 2016: 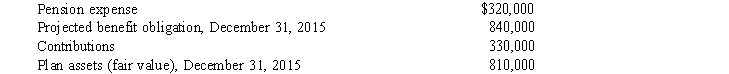 -Refer to Exhibit 19-1. The balance in Prepaid/Accrued Pension Cost at December 31, 2016, should be
 (Multiple Choice)
4.9/5 (84)
(84) Robin Co. has a defined benefit pension plan that has experienced differences between its expected and actual projected benefit obligation. Data on the plan as of January 1, 2016, follow: 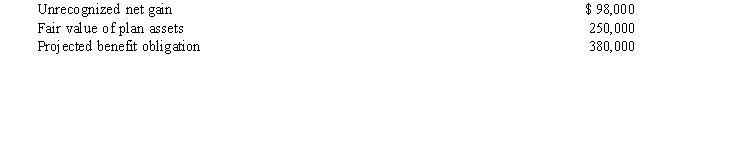 There was no difference between the company's expected and actual return on plan assets during 2016. The average remaining service life of the company's employees is 12 years.
Required:
Determine the amount of the net gain or loss to be included in pension expense for 2016 and indicate whether it is an increase or decrease in the pension expense calculation.
There was no difference between the company's expected and actual return on plan assets during 2016. The average remaining service life of the company's employees is 12 years.
Required:
Determine the amount of the net gain or loss to be included in pension expense for 2016 and indicate whether it is an increase or decrease in the pension expense calculation. (Essay)
4.9/5 (82)
(82) If a pension plan amendment is adopted and retroactive benefits are granted to employees, the amount of the prior service cost at the date of grant is accounted for
(Multiple Choice)
4.9/5 (102)
(102) One type of post-retirement benefit other than pensions is healthcare benefits.
Required:
Discuss the major differences between postretirement healthcare benefits and pensions.
(Essay)
4.8/5 (78)
(78) Current GAAP requires that the net gain or loss from a settlement or curtailment be included in the
(Multiple Choice)
4.8/5 (79)
(79) If an employer were to account for a defined benefit pension plan on the cash basis, it would be a violation of the
(Multiple Choice)
4.9/5 (84)
(84) The following information is related to a company's pension plan: 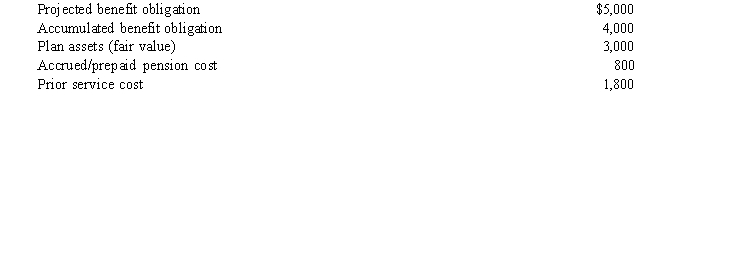 Required:
a. Prepare the adjusting journal entry to update the pension liability.
b. Assume that instead of Accrued/Prepaid Pension Cost having a credit balance of $800, it had a $600 debit balance. Prepare the adjusting journal entry to record the pension liability.
Required:
a. Prepare the adjusting journal entry to update the pension liability.
b. Assume that instead of Accrued/Prepaid Pension Cost having a credit balance of $800, it had a $600 debit balance. Prepare the adjusting journal entry to record the pension liability. (Essay)
4.9/5 (73)
(73) On January 1, 2016, Jackson Hole Company decided to provide a healthcare plan for retired employees. In order for benefits to be determined for each employee, the company gives credit to the date of hire for each employee. This is a retroactive benefit. The following information regarding the plan is as follows:
Accumulated postretirement benefit obligation for employees fully 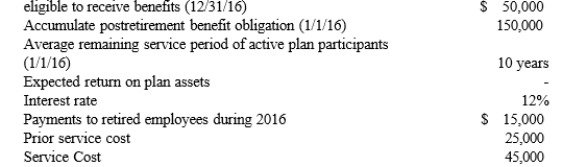 Required:
1) Compute the OPRB expense for 2016 using the average remaining service life to amortize the prior service cost.
2) Prepare all the required journal entries for 2016 if the plan is not funded.
3) Compute the accumulated postretirement benefit obligation.
Required:
1) Compute the OPRB expense for 2016 using the average remaining service life to amortize the prior service cost.
2) Prepare all the required journal entries for 2016 if the plan is not funded.
3) Compute the accumulated postretirement benefit obligation. (Essay)
4.8/5 (68)
(68) The expense for other postretirement benefits, such as health care benefits, dental benefits, and eye care benefits, currently is accounted for
(Multiple Choice)
4.9/5 (76)
(76) The vested benefit obligation is the present value of the benefits the employee is entitled to receive even if the employee is no longer employed by the company.
(True/False)
4.9/5 (65)
(65) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)