



 Chat with AI
Exam 19: Accounting for Post-Retirement Benefits

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


Which of the following is not a component of pension expense to be reported on a company's income statement?
(Multiple Choice)
4.9/5  (77)
(77) ACE has a defined benefit pension plan. ACE is preparing the December 31, 2015 financial statement disclosures related to the plan assets. It should disclose which of the following? I. Expected Return on Plan Assets
II) Actual Return on Plan Assets
(Multiple Choice)
4.9/5 (77)
(77) A pension plan provides for future retirement income based on the employee's earnings and length of service with the company. This type of pension plan is termed a
(Multiple Choice)
4.8/5 (76)
(76) During 2015, the Electric Company experienced a difference between its expected and actual projected benefit obligation. At the beginning of 2016, Electric's actuary notified them of the following accumulated information related to their plan: 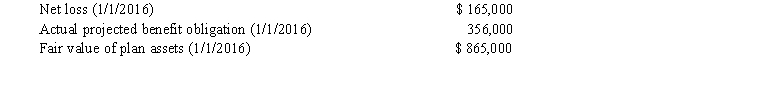 On December 31, 2016, Electric is in the process of calculating the net gain or loss to include in its pension expense for 2016. The average remaining service life of its employees is 10 years and there are no differences between the company's expected and annual rate of return on plan assets in 2016.
Required:
Compute the amount of the net gain or loss to include in the pension expense for 2016. Note whether it is an addition or subtraction to the pension expense.
On December 31, 2016, Electric is in the process of calculating the net gain or loss to include in its pension expense for 2016. The average remaining service life of its employees is 10 years and there are no differences between the company's expected and annual rate of return on plan assets in 2016.
Required:
Compute the amount of the net gain or loss to include in the pension expense for 2016. Note whether it is an addition or subtraction to the pension expense. (Essay)
4.7/5 (89)
(89) The IASB's 2011 amendment to IAS 19 removed the smoothing of devices in pension accounting, which means that companies will have to recognize all changes in their projected benefit obligation and plan assets in the current period. These changes will be recorded in pension expense or other comprehensive income. With this change pension expense will have two components. Indicate that those two components are and provide a brief explanation of each.
(Essay)
4.9/5 (79)
(79) Accounting for prior service cost prospectively would violate the matching concept because all the services performed by the employees were completed in previous periods.
(True/False)
4.8/5 (82)
(82) Which of the following disclosures are required by GAAP for OPEBs?
(Multiple Choice)
4.9/5 (83)
(83) The board of directors of the Vermont Company is going to adopt a defined benefit pension plan for the company's employees. The board is considering granting pension credit for up to ten 10) years of service rendered prior to the date that the plan is adopted. The board desires to grant the retroactive credit in order to provide equity to employees for their previous years of service. The board has hired an actuary to determine the cost of granting the retroactive credit. The actuary has calculated the cost of the retroactive benefits to be approximately one million dollars. The board has asked the company's controller to explain how the cost of the prior service credit would be accounted for in the financial statements.
Required:
a. According to current GAAP, the cost of any prior service credit granted to employees is recognized as a liability and reduces other comprehensive income, and it then amortized as a component of pension expense over the current and future periods. The liability is reduced and other comprehensive income is
a. Describe the GAAP that would be required by Vermont Company if prior service credit is granted to its employees.
b. Many people have argued that the method adopted by the FASB to account for prior service costs has several conceptual flaws. Briefly discuss the flaws of the approach adopted by the FASB for prior service costs.
c. The textbook discusses three other approaches that might have been used to account for prior service costs. Describe these three alternative approaches.
(Essay)
4.8/5 (91)
(91) Teresa Company had the following information related to its pension plan: 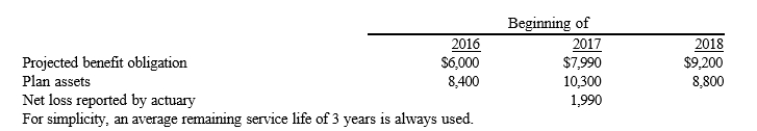 An additional net loss of $1,990 was reported as of January 1, 2017 see table). This amount has been included in the
January 1, 2017, projected benefit obligation balance.
Required:
Compute the amount of loss that should be included in pension expense in:
a. 2017
b. 2018
An additional net loss of $1,990 was reported as of January 1, 2017 see table). This amount has been included in the
January 1, 2017, projected benefit obligation balance.
Required:
Compute the amount of loss that should be included in pension expense in:
a. 2017
b. 2018 (Essay)
4.9/5 (82)
(82) In 2016, the Ballaster Company decided to amend its defined benefit pension plan. The amendment gave 7 employees the right to receive future benefits based upon their prior service. Ballaster's actuary determined that the prior service cost for this amendment amounts to $550,000. One employee will retire in 1 year, 2 expect to retire in 2 years,1 in three years, 1 in 4 years, and 2 in five years.
Required:
Using the straight line method
1)compute the remaining service life round to 5 decimals)
2) prepare an amortization schedule to amortize the prior service cost
(Essay)
4.8/5 (77)
(77) Other postretirement benefits are provided to former employees after employment.
(True/False)
4.9/5 (92)
(92) An Internal Revenue Code rule that impacts the design of pension plans is that:
(Multiple Choice)
5.0/5 (73)
(73) Benefits for which the employee's right to receive a present or future pension benefit is no longer contingent on remaining in the service of the employer are called
(Multiple Choice)
4.9/5 (81)
(81) GAAP for pension plans requires companies with defined benefit pension plans to
(Multiple Choice)
4.8/5 (78)
(78) In 2016, the Electrician Company decided to amend its defined benefit pension plan. The amendment gave 7 employees the right to receive future benefits based upon their prior service. Electrician's actuary determined that the prior service cost for this amendment amounts to $550,000. Employee A will retire in 1 year, employee's B & C expect to retire in 2 years, employee D in three years, employee E in 4 years, and employee's F & G in five years.
Required:
Using the years-of-future service method, prepare the schedules to determine:
1) the amortization fraction for each year
2) the amortization of the prior service cost
(Essay)
4.8/5 (94)
(94) Given the following information 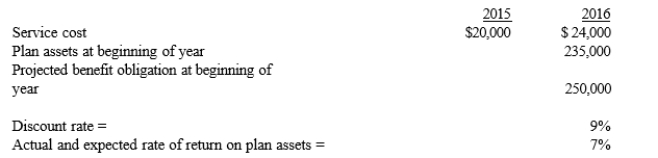 What is pension expense for 2016?
 (Multiple Choice)
4.8/5 (70)
(70) The following information is provided regarding a company's pension plan: 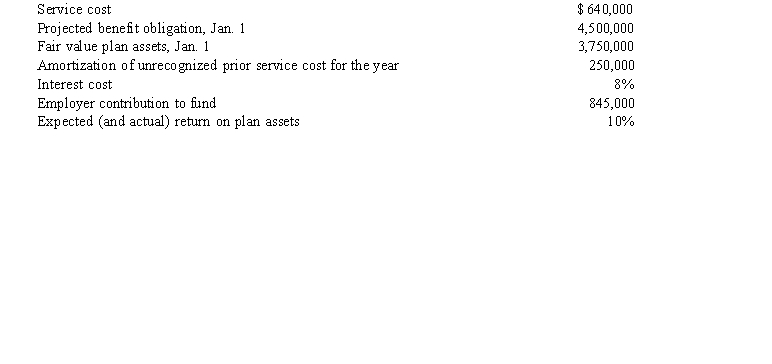 Required:
a. Prepare the December 31 journal entry to record pension expense.
b. Explain the difference between "interest cost" and the "expected return on plan assets."
Required:
a. Prepare the December 31 journal entry to record pension expense.
b. Explain the difference between "interest cost" and the "expected return on plan assets." (Essay)
4.9/5 (70)
(70) Which of the following statements is true concerning prior service cost?
(Multiple Choice)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)