



 Chat with AI
Exam 20: Accounting for Leases

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


On January 1, 2001, Wishful Thinking, a lessor, entered into a direct-financing lease agreement with Lennard Company. The lease agreement required 6 equal annual payments of $50,000 at the end of each year. The leased property had an estimated residual value of $14,000, which was guaranteed by an unrelated third party. Wishful Thinking desired a 10% rate of return. What was the amount that Wishful Thinking recorded as interest revenue on the lease at the end of the year 2002?

Free
(Multiple Choice)
4.8/5  (71)
(71) Correct Answer: Verified
B
Exhibit 20-1
On January 1, 2016, Pearson Company signed a lease agreement requiring six annual payments of $60,000,
beginning December 31, 2016. Pearson's incremental borrowing rate was 9% and the lessor's implicit rate, known by
Pearson, was 10%. The present value factors of an ordinary annuity of $1 for six periods for interest rates of 9%
and 10% are 4.48592 and 4.35526, respectively.
-Refer to Exhibit 20-1. What would be the interest expense for 2016 round answers to the nearest dollar)?
Free
(Multiple Choice)
4.8/5 (98)
(98) Correct Answer:Verified
VerifiedD
Which of the following is not a required disclosure by a lessor of a sales-type lease?
Free
(Multiple Choice)
4.8/5 (84)
(84) Correct Answer:Verified
VerifiedA
Exhibit 20-4
On January 1, 2016, Average Leasing Company entered into a direct financing lease with a lessee, Lenny Company. The lease agreement calls for five equal annual payments of $75,000 at the beginning of each year with the first payment due on January 1, 2016. The leased property has an estimated residual value of $10,000, which Lenny does not guarantee. The property remains the property of Average at the end of the lease term. Average desires a 12% rate of return. Present value factors for a 12% interest rate are as follows: 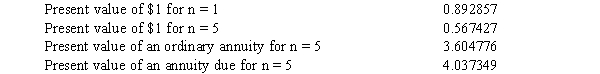 -Refer to Exhibit 20-4. What is the amount of interest revenue that Average should recognize on the lease for the year ended December 31, 2016 round the answer to the nearest dollar)?
 (Multiple Choice)
4.8/5 (72)
(72) TradeWell Company signs a lease agreement for 6 years. The agreement requires an annual payment of $35,750 at the end of each year. The implicit interest rate in the lease is 12%. The estimated residual value of the asset is $42,500. Mu Bank, an unrelated third party, guarantees the residual value. What amount should TradeWell Company debit to Lease Receivable at the inception of the lease?
(Multiple Choice)
4.9/5 (94)
(94) Any initial direct costs incurred by the lessor for a lease agreement that is classified as an operating lease should be
(Multiple Choice)
4.9/5 (68)
(68) A lease must be treated as a direct financing lease by the lessor when at least one of the four basic criteria is met, collectability of the minimum lease payments is reasonably assured, no uncertainties surround the amount of the unreimbursable costs, and
(Multiple Choice)
4.8/5 (65)
(65) The lessee's disclosures should include the future minimum rental payments as of the date of the latest balance sheet presented, in the aggregate and for a certain number of succeeding fiscal years. What is the required number of years?
(Multiple Choice)
4.9/5 (85)
(85) The amount of the lease obligation that is classified as a current liability is the dollar amount of lease payments to be made during the current year.
(True/False)
4.7/5 (86)
(86) A sales-type lease results in a manufacturer's or dealer's profit or loss and meets one or more of the capitalization criteria and both the recognition criteria.
(True/False)
4.8/5 (84)
(84) Which of the following is not a required disclosure by a lessee of an operating lease?
(Multiple Choice)
4.7/5 (72)
(72) Exhibit 20-2
On January 1, 2016, Mary Company leased equipment, signing a five-year lease that requires annual lease payments of $20,000. The lease qualifies as a capital lease. The payments are made at year-end, and the first payment will be made at December 31, 2016. In addition, Mary guarantees the residual value to be $8,000 at the end of the lease term. Mary correctly uses the lessor's implicit interest rate, which is 12%. The present value factors for five periods at 12% are as follows:  -Refer to Exhibit 20-2. What is the interest expense associated with the lease obligation for the year ending December 31, 2017? Round answers to the nearest dollar.)
 (Multiple Choice)
4.9/5 (74)
(74) On January 1, 2010, Magnum Company leased equipment for 8 years. The agreement required annual payments of $65,000 at the end of each year. The cost value and the fair value of the lease equipment were $100,000 and
$291,675.90, respectively. The estimated residual value of the lease equipment was $35,000 at the end of the lease, which was not guaranteed by the lessee. The estimated economic life of the leased equipment was 10 years. The lease payments were determined at an amount such that the lessor earned a 15% annual rate of return over the lease period. The leased equipment was returned to the lessor at the end of the lease. Based on the given information, how should the lease be classified?
(Multiple Choice)
4.8/5 (84)
(84) Which is an advantage of leasing from a lessee's viewpoint?
(Multiple Choice)
4.9/5 (82)
(82) On January 1, 2016, Madison Company signed a four-year lease requiring annual payments of $15,000 with the first payment due on January 1, 2016. The fair value of the equipment leased was $50,000. Madison's incremental borrowing rate was 6%. Actuarial information for 6% follows: 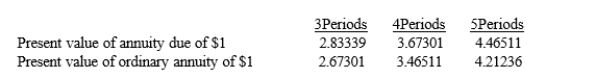 Assuming the lease qualifies as a capital lease, what amount should be recorded as leased equipment under capital leases on January 1, 2016 rounded to the nearest dollar)?
 (Multiple Choice)
4.9/5 (71)
(71) Jennifer, Inc. entered into a five-year capital lease on December 31, 2016. This lease requires five minimum annual lease payments due on December 31 of each year. The first minimum payment was paid on December 31, 2016. This payment included which of the following? 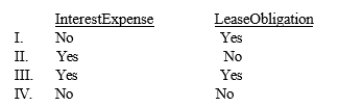
(Multiple Choice)
4.9/5 (79)
(79) Exhibit 20-5
The Baltimore, Inc. entered into a five-year lease with the Waugh Chapel Company on January 1, 2016. Baltimore, the lessor, will require that five equal annual payments of $25,000 be made at the beginning of each year. The first payment will be made on January 1, 2016. The lease contains a bargain purchase option price of $12,000, which the lessee may exercise on December 31, 2020. The lessee pays all executory costs. The cost of the leased property and its normal selling price are $95,000 and $118,236, respectively. Collectibility of the future lease payments is reasonably assured, and the lessor does not expect to incur any future costs related to the lease. Present value factors for a 7% 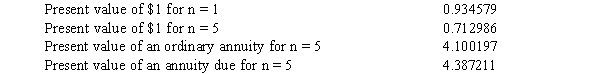 -Refer to Exhibit 20-5. If Baltimore requires a 7% annual return, what is the correct amount that should be credited to Unearned Interest: Leases on January 1, 2016, by Baltimore round the answer to the nearest dollar)?
 (Multiple Choice)
4.9/5 (77)
(77) If a lease is classified as a capital lease because the lease agreement contains a bargain purchase option, the time period to be used by the lessee to amortize the leased property is
(Multiple Choice)
4.8/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)